Greenlam (GREENLAM) Q2 FY27 Profit Falls 23% as Costs Outpace Revenue Growth
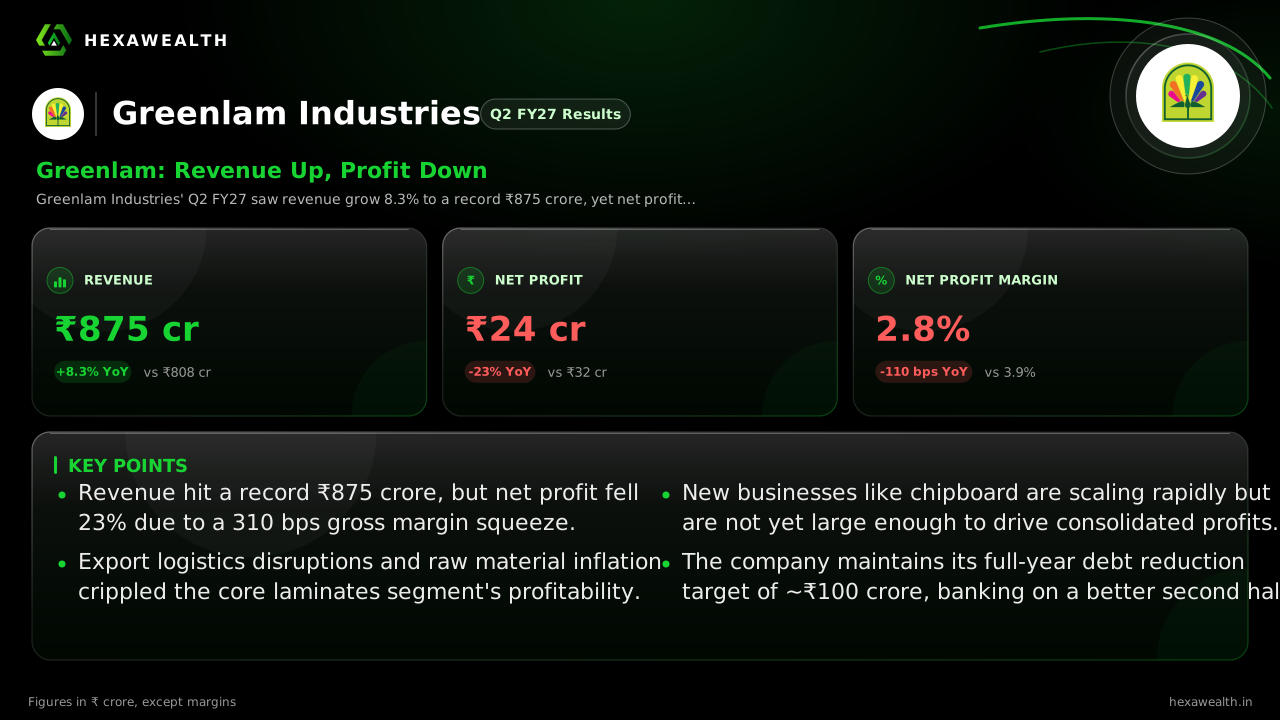
Greenlam Industries posted its highest-ever quarterly revenue of ₹875 crore in Q2 FY27, but net profit fell 23% year-on-year as raw material and freight costs squeezed margins.
Greenlam Industries' Q2 FY27 saw revenue grow 8.3% to a record ₹875 crore, yet net profit fell 22.9% to ₹24.5 crore. The decline was driven by a sharp 310 basis point contraction in gross margin due to input cost pressure and export challenges.
For Greenlam Industries, a record top line this quarter came with a painful catch. The laminates leader posted its highest-ever quarterly revenue, but profits fell sharply as costs rose faster than sales.
The company’s revenue grew 8.3% year-on-year to ₹875.2 crore. Net profit, however, dropped 22.9% to ₹24.5 crore. The net profit margin contracted by 110 basis points to 2.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 875.2YoY +8.3% | 796.7 | 808.3 |
| Profit (₹ Cr) | 24.5YoY -23% | 21.2 | 31.8 |
| Net Profit Margin (%) | 2.8YoY -28% | 2.7 | 3.9 |
Why the record sales didn't reach the bottom line
Management, on the earnings call, called the quarter an “aberration.” The core laminates business saw flat revenue as export sales volumes fell 12% due to container delays and high freight costs. Simultaneously, gross margin fell 310 basis points to 51.5%.
This was driven by volatile raw material prices and an unfavourable product mix. Reports from Ply Reporter in October noted a fresh surge in phenol and kraft paper prices, pressuring laminate producers.
The new engines are starting, but slowly
Growth came from newer segments. The chipboard business more than doubled its revenue year-on-year to ₹107 crore and turned EBITDA positive. The plywood and allied segment also grew, with veneer, flooring, and doors turning EBITDA positive.
Yet these segments are still scaling. The plywood business reported a marginal loss, and chipboard utilization was at 61%. Their contribution wasn't enough to offset the margin pressure in the larger laminates division.
The debt overhang and the road ahead
Net debt stood at ₹922 crore as of September, with interest expense consuming a significant portion of operating profit. Management, according to the AlphaStreet transcript, remains confident in reducing debt by about ₹100 crore this year, aided by better second-half performance.
Guidance for the full year was tempered. The company now expects consolidated revenue growth of 16-18%, down from 18-20% earlier. It refrained from giving a specific margin outlook but believes the second half will be better than the first.
Key Points
- Revenue hit a record ₹875 crore, but net profit fell 23% due to a 310 bps gross margin squeeze.
- Export logistics disruptions and raw material inflation crippled the core laminates segment's profitability.
- New businesses like chipboard are scaling rapidly but are not yet large enough to drive consolidated profits.
- The company maintains its full-year debt reduction target of ~₹100 crore, banking on a better second half.
Hexa Perspective
The quarter reveals a company in transition, caught between a profitable past and a scaled-up future. The core business is facing cyclical cost pressure just as new capacities need time to reach optimal utilization.
The path to better profitability hinges on two factors normalizing: raw material costs and global freight networks. If those stabilize, the operating leverage from record sales and a growing chipboard division could deliver a sharper earnings recovery in the coming quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.