Flomic Global Logistics (FLOMIC) Q1 FY27 Profit Drops 42% Despite Strong Revenue Growth
The logistics firm posted an 18% jump in revenue for Q1 FY27, but a sharp rise in operating expenses pushed profit down sequentially.
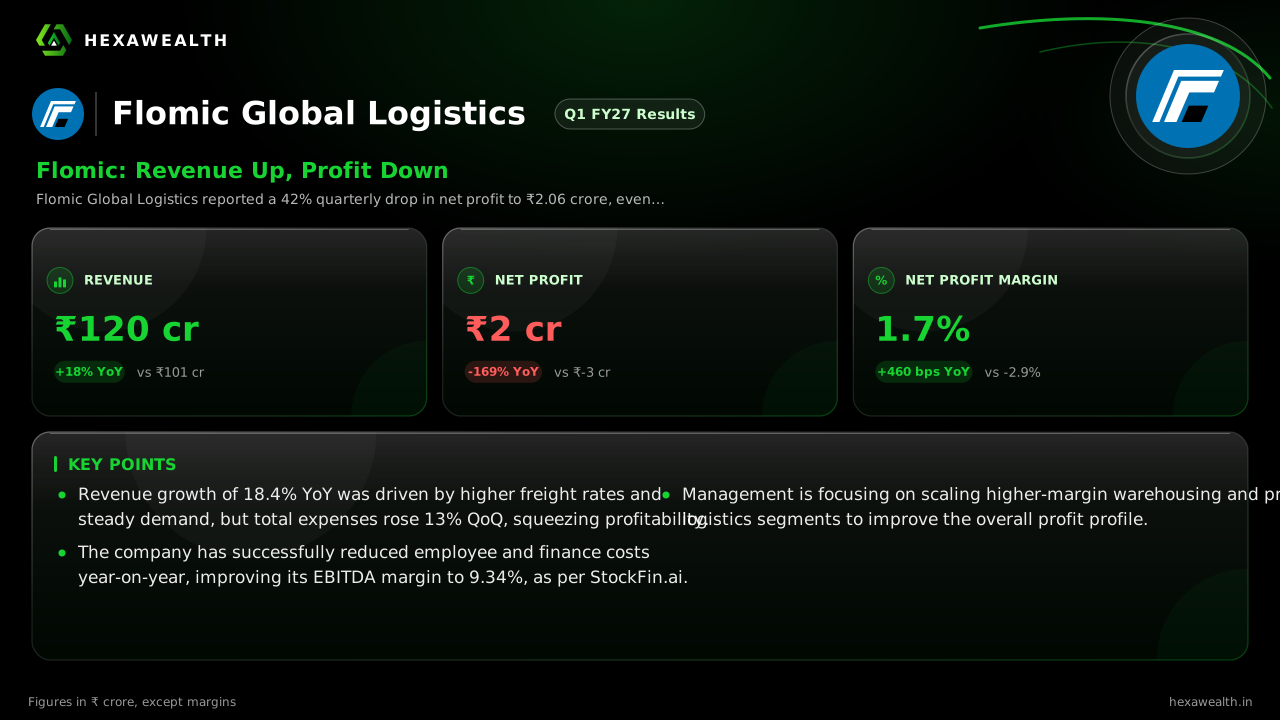
Flomic Global Logistics reported a 42% quarterly drop in net profit to ₹2.06 crore, even as revenue grew 18% year-on-year. The decline was driven by a 13% sequential rise in total expenses, outpacing sales growth.
For Flomic Global Logistics, the first quarter of FY27 was a story of two diverging lines. While freight rates and service demand pushed revenue higher, the cost of delivering that growth squeezed the bottom line, raising questions about the sustainability of its recent return to profitability.
The numbers show the tension. Revenue rose 18.4% year-on-year to ₹120 crore, a solid sequential gain of 11.1%. Yet net profit fell 41.6% from the previous quarter to ₹2.06 crore. The net profit margin contracted 160 basis points to 1.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ1 FY27 (Jun 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 120.00 | 108.02 |
| Profit (₹ Cr) | 2.06 | 3.53 |
| Net Profit Margin (%) | 1.7 | 3.3 |
Why the profit squeeze hit now
The sequential profit drop came as total expenses jumped 13% to ₹117.7 crore, outpacing the 11% revenue growth. According to a report by ScanX, operating expenses rose significantly year-on-year. While the company has cut employee and interest costs over the past year, this quarter’s expense surge eroded those gains.
Management, in its maiden earnings call covered by ScanX, attributed the strong revenue growth to a mix of volume growth (6-7%) and rising freight rates due to geopolitical volatility. They noted that ocean exports became more profitable as rates rose.
The market's cautious read
The stock closed at ₹42.63 on the results date, having fallen over 30% in the past year. MarketsMojo maintained a 'Sell' rating on the stock in mid-August. The lack of institutional holdings, as noted by StockFin.ai, underscores the limited broader investor confidence despite the operational turnaround from last year's losses.
Key Points
- Revenue growth of 18.4% YoY was driven by higher freight rates and steady demand, but total expenses rose 13% QoQ, squeezing profitability.
- The company has successfully reduced employee and finance costs year-on-year, improving its EBITDA margin to 9.34%, as per StockFin.ai.
- Management is focusing on scaling higher-margin warehousing and project logistics segments to improve the overall profit profile.
Hexa Perspective
Flomic's quarter highlights the fragile nature of its profitability recovery. While top-line growth is healthy and operating leverage is improving, the business remains exposed to volatile freight costs and competitive pricing. The strategic shift towards asset-light, high-margin services like warehousing is logical but will take time to materially alter the consolidated earnings mix. For now, the margin trajectory is more indicative of cost discipline than durable pricing power, making sustained profit growth contingent on continued operational efficiency.
Also read
Market Pulse, 7 Nov 2026: A Domestic Bid Meets Global Crosscurrents
DIIs become largest Nifty 50 owners as FPI flows turn tactical
Market News Today, 7 Nov 2026: Oil surplus pulls yields down 22 bps and flips FPI flows to $4.1bn
Finkurve: Growth Soars, Margins Dip
Filmcity Media: Loss Widens, Revenue Zero
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.