Euro Pratik Sales (EUROPRATIK) Q2 FY27 Profit Jumps 31% Sequentially Despite Margin Squeeze
The home decor leader posted record revenue but saw profitability pressured by rising costs and newly acquired, lower-margin businesses.
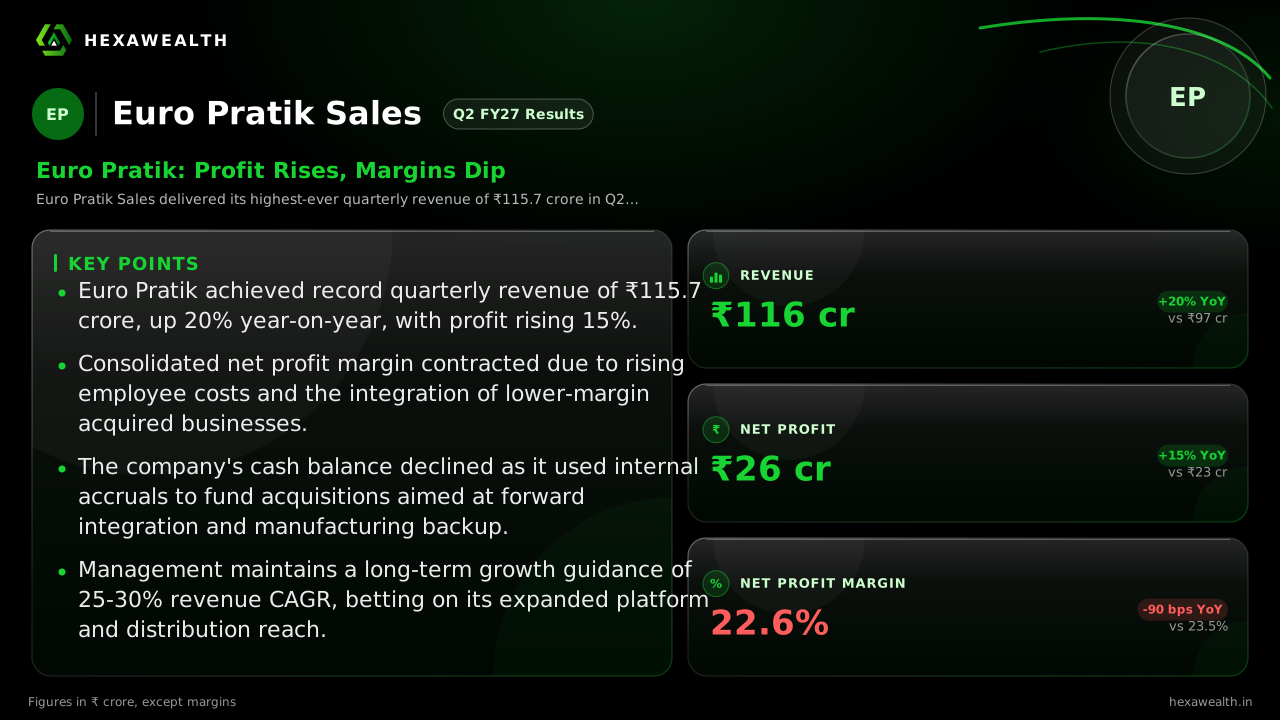
Euro Pratik Sales delivered its highest-ever quarterly revenue of ₹115.7 crore in Q2 FY27, with profit up 15% year-on-year. However, margins contracted as costs rose and recent acquisitions diluted overall profitability.
For Euro Pratik Sales, growth is arriving faster than profits can keep up. The decorative surfaces leader posted its highest-ever quarterly revenue, but the bottom line tells a story of integration costs and a margin squeeze that is reshaping the business.
The numbers show a company accelerating. Revenue rose 20% year-on-year to ₹115.7 crore, while profit grew 15% to ₹26.2 crore. Sequentially, the improvement was sharper, with profit jumping 31% from the June quarter. Yet, the net profit margin slipped 90 basis points from a year ago to 22.6%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 115.73YoY +20% | 103.33 | 96.56 |
| Profit (₹ Cr) | 26.19YoY +15% | 20.05 | 22.69 |
| Net Profit Margin (%) | 22.6YoY -3.8% | 19.4 | 23.5 |
The cost of building a platform
Revenue growth was driven by strong demand across its core wall panel and laminate segments. Management, in an earnings call highlighted by Finance Yahoo, noted that 75% of core business sales come from products launched within the last 14 months. However, this top-line strength was met with a 65% year-on-year surge in employee costs and elevated raw material expenses.
The bigger drag on profitability, however, comes from the company's acquisition spree. The consolidated EBITDA margin declined to 31.4% from 32.5% a year ago. Reports from Multibagg.ai and the earnings call indicate this is partly due to integrating newly acquired entities like Rusty Surfaces, which operate at lower EBITDA margins of 16-17%.
A cash-rich model gets stretched
This strategic shift is visible on the balance sheet. While the company remains nearly debt-free, its cash pile nearly halved to ₹8.4 crore in six months, as per the earnings call. Working capital days have also increased, though management attributes this to the full balance-sheet consolidation of Euro Veneer World.
The market reaction was positive, with the stock closing at ₹201 on results day, up over 7%. This suggests investors are focusing on the growth trajectory. Management has set a bold target, guiding for a 25-30% revenue CAGR over the next three years, driven by portfolio expansion and distribution growth.
Key Points
- Euro Pratik achieved record quarterly revenue of ₹115.7 crore, up 20% year-on-year, with profit rising 15%.
- Consolidated net profit margin contracted due to rising employee costs and the integration of lower-margin acquired businesses.
- The company's cash balance declined as it used internal accruals to fund acquisitions aimed at forward integration and manufacturing backup.
- Management maintains a long-term growth guidance of 25-30% revenue CAGR, betting on its expanded platform and distribution reach.
Hexa Perspective
The quarter underscores a transition from a pure-play, asset-light distributor to an integrated surface solutions platform. The margin compression is a near-term cost of this ambition, as lower-margin acquisitions dilute the stellar profitability of the core Europratik and Glorio brands.
The path ahead hinges on execution. Success means utilizing the spare capacity in acquired units to improve their margins, and successfully replacing third-party products on the shelves of its new retail arms. If these synergies materialize, the current margin sacrifice could pave the way for more resilient, scaled-up growth. If not, the company risks being stuck with a heavier, less profitable structure.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.