Enbee Trade (ENBETRD) Q2 FY27 Profit Jumps 49% as Costs Fall, But Promoters Exit in Mass
The NBFC posted its strongest quarterly profit yet, driven by sharply lower provisions, but a collapse in promoter holding overshadows the operational win.
Enbee Trade & Finance reported a 49% surge in Q2 FY27 net profit to ₹4.1 crore, fueled by a 60% drop in credit costs. However, a dramatic promoter exit and rising interest expenses cast a shadow over the financial performance.
For a small NBFC, a quarter of record profit and expanding margins should be a clear win. For Enbee Trade & Finance, it arrived alongside a crisis of confidence that the numbers cannot explain.
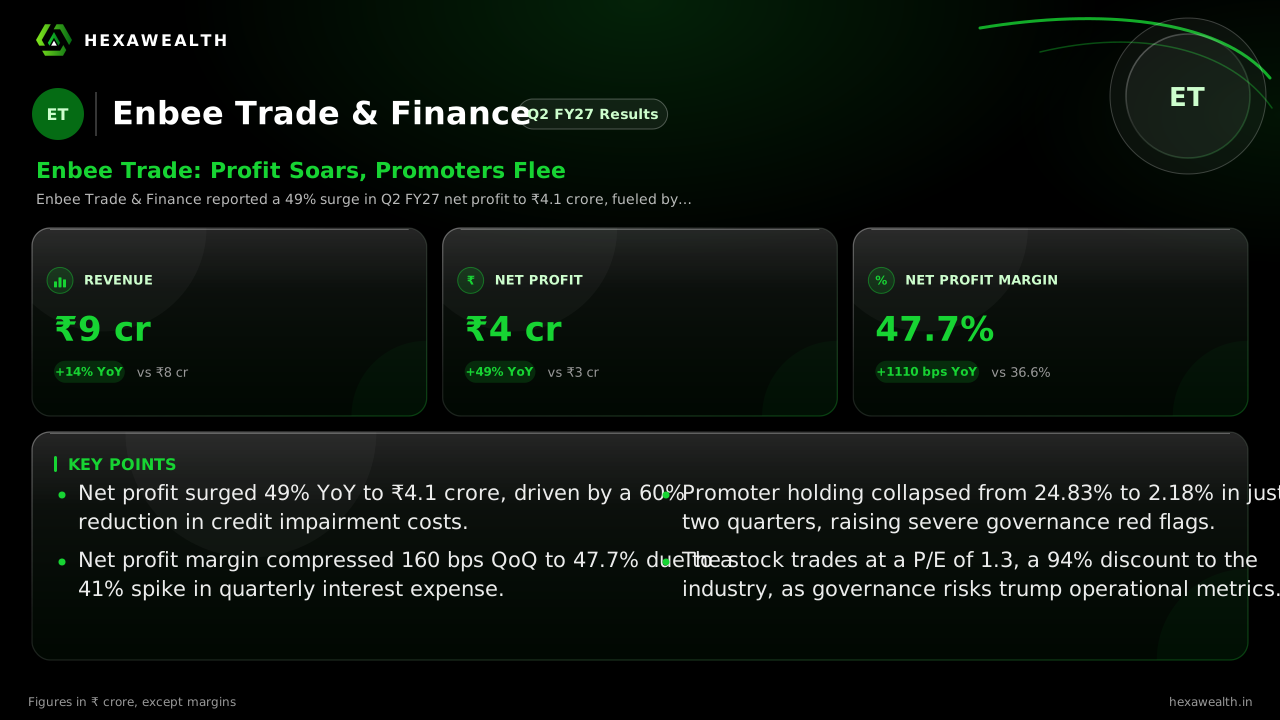
Revenue rose 14% year-on-year to ₹8.59 crore, continuing a steady climb. Net profit jumped 49% to ₹4.1 crore, the highest in recent quarters. The story is in the costs: total expenses fell 22% from a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
Metric
CurrentQ2 FY27
PreviousQ1 FY27
Same quarter LYQ2 FY26
Revenue (₹ Cr)
8.59YoY +14%
8.21
7.53
Profit (₹ Cr)
4.10YoY +49%
4.05
2.75
Net Profit Margin
47.7%YoY +30%
49.3%
36.6%
The engine behind the profit jump
A sharp 60% year-on-year drop in impairment charges was the primary driver, according to a scanx.trade report. This suggests improved asset quality or recoveries. Employee costs and depreciation also fell, helping operating margins expand dramatically.
Yet the profit margin dipped 160 basis points from the previous quarter. A 41% sequential spike in interest expense, to ₹1.43 crore, was the culprit. MarketsMojo notes this points to rising borrowing costs even as the loan book grew.
A governance shadow over the numbers
The operational strength is starkly contradicted by a collapse in promoter holding. From 24.83% in April, it fell to 11.65% in June and then to just 2.18% by September, as per MarketsMojo.
This near-total exit in two quarters while profits hit records has spooked the market. The stock trades at a P/E of 1.3, a 94% discount to the industry, reflecting severe governance concerns that outweigh the valuation math.
The path ahead
The company completed a rights issue, raising ₹12.56 crore to strengthen its equity. Its loan book grew to ₹167.9 crore as of September. However, the promoter exodus creates a credibility gap no quarterly profit can bridge alone.
Future performance hinges on stabilizing funding costs and, more critically, restoring investor trust. The operational momentum is positive, but the governance overhang is profound.
Key Points
Net profit surged 49% YoY to ₹4.1 crore, driven by a 60% reduction in credit impairment costs.
Net profit margin compressed 160 bps QoQ to 47.7% due to a 41% spike in quarterly interest expense.
Promoter holding collapsed from 24.83% to 2.18% in just two quarters, raising severe governance red flags.
The stock trades at a P/E of 1.3, a 94% discount to the industry, as governance risks trump operational metrics.
“
Hexa Perspective
The quarter presents a paradox of peak profitability amid peak skepticism. The sharp drop in provisions is a clear positive, suggesting cleaner assets. Yet the punishing rise in interest costs shows funding pressure is real.
The promoter exit is the dominant theme. It implies undisclosed risks that financial statements do not capture. Until management addresses this credibility crisis, the stock's deep discount is likely to persist, regardless of earnings trajectory.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Enbee Trade & Finance's Q2 FY27 results?
Enbee Trade & Finance reported a standalone net profit of ₹4.10 crore for Q2 FY27 (July-September 2026), a 49% increase from ₹2.75 crore in Q2 FY26. Revenue from operations rose 14% year-on-year to ₹8.59 crore.
The 49% year-on-year profit jump was primarily driven by a sharp 60% reduction in credit costs (impairment on financial instruments), as reported by scanx.trade. Lower employee expenses and depreciation also contributed to the surge.
What caused the 41% QoQ spike in Enbee Trade's interest expense in Q2 FY27?
Enbee Trade's interest expense jumped 41% quarter-on-quarter to ₹1.43 crore in Q2 FY27. MarketsMojo suggests this indicates rising borrowing costs or expanded leverage, which squeezed the net profit margin sequentially.
What is the asset quality trend for Enbee Trade & Finance in Q2 FY27?
Asset quality appears to have improved. According to scanx.trade, impairment on financial instruments dropped 60% year-on-year to ₹47.61 lakh in Q2 FY27, suggesting better asset quality or recovery trends.
What was Enbee Trade & Finance's loan book growth in the September 2026 quarter?
Enbee Trade's loan book expanded to ₹167.91 crore as of September 30, 2026, up from ₹153.17 crore on March 31, 2026, as per scanx.trade. Borrowings decreased over the same period, indicating deleveraging.
What guidance did Enbee Trade & Finance management provide for the rest of FY27?
The company did not provide specific forward guidance in its Q2 FY27 results announcement. The board meeting notice and accompanying financial statement contained no operational outlook, forecasts, or management commentary.
There are no published analyst consensus estimates for this micro-cap NBFC. Flash Finance notes the quarter's profit was 25% below the company's own historical trend, based on its median growth rate.
What are brokerages saying about Enbee Trade & Finance stock after Q2 FY27 results?
MarketsMojo maintains a 'SELL' rating with a score of 43/100, citing the severe governance risk from the promoter exit. It notes the stock's valuation is 'Very Attractive' quantitatively but illusory given the governance overhang.
How did Enbee Trade & Finance stock price react to the Q2 FY27 results?
The stock was trading at ₹0.26 around the results date, down 49% from its 52-week high. MarketsMojo reports it has collapsed 35% over the past year, severely underperforming the broader market despite the strong quarterly profit.
Why is Enbee Trade & Finance trading at a significant discount to the industry PE?
Enbee Trade trades at a P/E of 1.3, a 94% discount to the industry average of 20.6. The discount reflects severe perceived risks, primarily the catastrophic collapse in promoter holding from 24.83% to 2.18% in two quarters.
Are there any recent corporate actions by Enbee Trade & Finance?
Yes. During H1 FY27, Enbee Trade completed a rights issue, allotting 12.56 crore equity shares at ₹1 per share, raising ₹12.56 crore to strengthen its equity base, as reported by scanx.trade.
Enbee Trade Q2 profit drop
Enbee Trade & Finance did not experience a profit drop in Q2 FY27. Its net profit actually increased by 49% year-on-year to ₹4.10 crore. However, profit growth was only 1.2% quarter-on-quarter.
Enbee Trade Q2 FY27 results order book
Enbee Trade & Finance's loan book stood at ₹167.91 crore as of September 30, 2026, according to scanx.trade. This was up from ₹153.17 crore on March 31, 2026, indicating growth in its lending portfolio.