Elin Electronics (ELIN) Q2 FY27 Profit Dives 72% as Costs Outpace Revenue
The electronics manufacturer saw revenue rise 10% year-on-year, but net profit collapsed due to raw material inflation and an adverse sales mix.
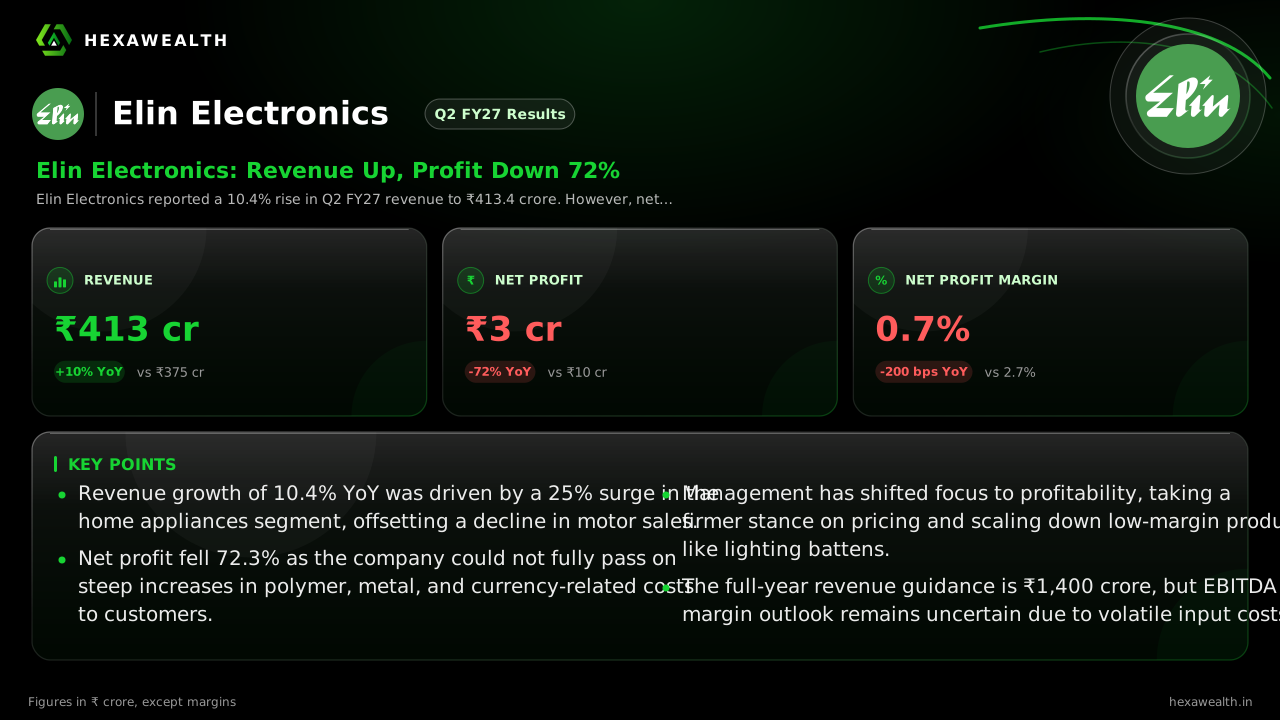
Elin Electronics reported a 10.4% rise in Q2 FY27 revenue to ₹413.4 crore. However, net profit fell sharply by 72.3% to ₹2.85 crore as higher polymer and metal costs could not be fully passed on to customers.
For an electronics manufacturer, a growing top line should signal healthy demand. For Elin Electronics, the September quarter delivered that growth but left profitability severely wounded. Revenue climbed 10.4% year-on-year, yet net profit collapsed by 72.3%, a stark reminder that in a volatile cost environment, sales alone do not guarantee earnings.
The numbers tell a story of divergence. Revenue reached ₹413.4 crore, a solid sequential jump from the ₹362.8 crore reported in Q1. Net profit, however, was a mere ₹2.85 crore, down from ₹10.3 crore a year ago. The net profit margin compressed to 0.7%, a 200-basis-point drop from the same quarter last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 413.37 | 362.80 |
| Profit (₹ Cr) | 2.85 | -21.41 |
| Net Profit Margin (%) | 0.7 | -5.9 |
Why the profit vanished
Growth came from the home appliances segment, where revenue surged about 25% year-on-year to ₹175.7 crore, according to a report by Multibagg.ai. This gain, however, was overshadowed by a sharp decline in the higher-margin fractional horsepower motors business. Management, in the earnings call transcribed by AlphaStreet, attributed the profit squeeze to a perfect storm of cost inflation. Polymer prices rose about 30% on average, while metals like steel and copper also saw sharp increases. A depreciating rupee added to import costs. Crucially, the company said it could not fully pass these higher raw material costs to customers, a point echoed in the Multibagg.ai analysis.
A strategic shift in priorities
The pressure has forced a clear change in strategy. Management stated it is now prioritizing profitability over revenue, taking a firmer stance on pricing with customers. This includes discussions to pass on not just material costs but also assembly costs linked to a recent minimum wage hike. The early effect of this shift was visible as the EBITDA margin improved to 3.4% in Q2 from 1.1% in the disastrous first quarter. The company also scaled down production of low-margin lighting battens to avoid losses.
The path ahead and market reaction
Outlook remains cautious. Management provided revenue guidance of ₹1,400 crore (±3%) for FY27 but refrained from giving a firm EBITDA margin forecast due to raw material volatility. They indicated Q3 margins could be similar to Q2's 3.4%, with a variation of 0.5%. The market reaction was negative, with the stock closing at ₹75.43 on November 6, down over 60% in the past year. The company's valuation, at a P/E of 20.4, trades at a 54.5% discount to the industry average, reflecting deep skepticism about a near-term earnings recovery.
Key Points
- Revenue growth of 10.4% YoY was driven by a 25% surge in the home appliances segment, offsetting a decline in motor sales.
- Net profit fell 72.3% as the company could not fully pass on steep increases in polymer, metal, and currency-related costs to customers.
- Management has shifted focus to profitability, taking a firmer stance on pricing and scaling down low-margin products like lighting battens.
- The full-year revenue guidance is ₹1,400 crore, but EBITDA margin outlook remains uncertain due to volatile input costs.
Hexa Perspective
Elin's quarter underscores the fragile state of margins in the electronics manufacturing services sector when input costs spike. The company's move to prioritize profitability is a necessary corrective, but its success hinges on customer acceptance of price hikes in a competitive market. The guidance suggests management expects only a stabilization, not a dramatic recovery, in margins for the rest of the year. With the stock's steep decline already pricing in deep concerns, the investment case now rests on whether this new pricing discipline can sustainably lift margins back above 3% before the next cost shock arrives.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.