Eiko Lifesciences (EIKO) Q2 FY27 Profit Growth Lags Behind 52% Revenue Surge
Eiko Lifesciences posted a 52% YoY revenue jump in Q2 FY27, but profit grew just 22% as costs rose faster, squeezing margins.
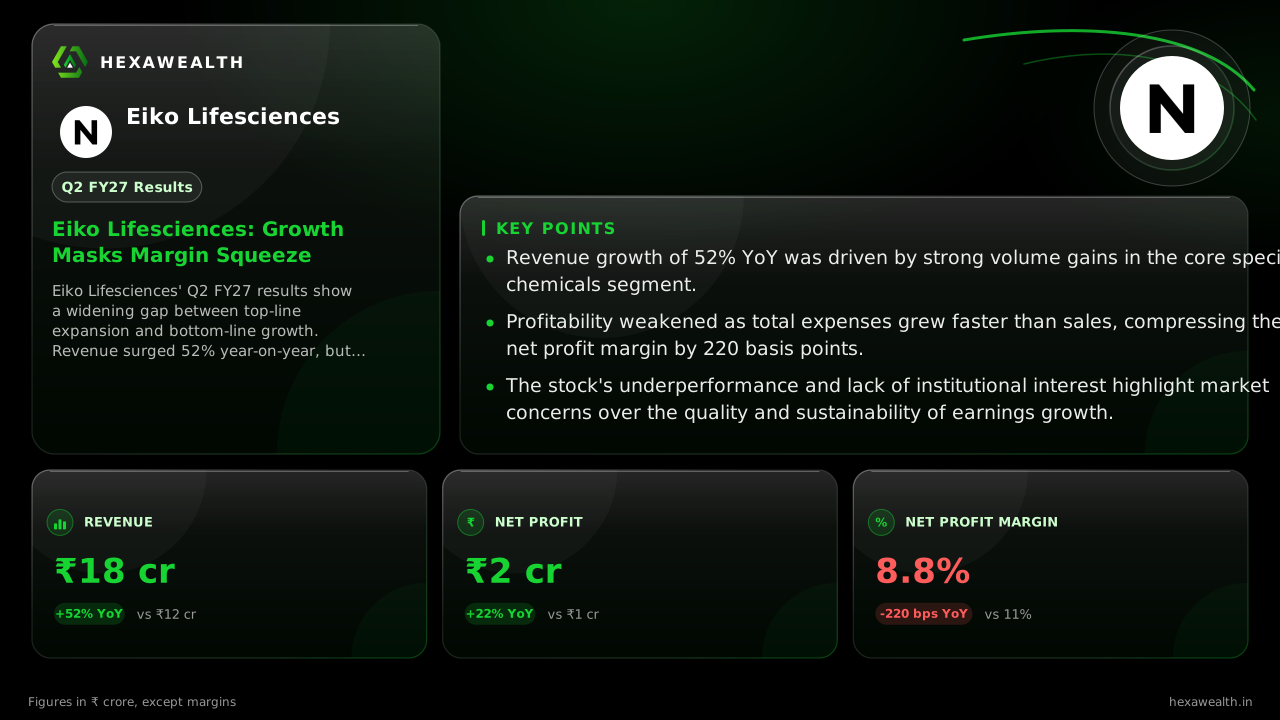
Eiko Lifesciences' Q2 FY27 results show a widening gap between top-line expansion and bottom-line growth. Revenue surged 52% year-on-year, but profit growth lagged at 22% as total expenses outpaced sales, compressing margins.
For a specialty chemicals firm in a pivot, growth is the test. Eiko Lifesciences passed that part in the September quarter, with revenue surging 52% from a year ago. Yet the profit that followed tells a more complicated story of costs rising even faster.
The numbers show the strain. Revenue reached ₹17.72 crore, up 5.8% from the June quarter. Profit grew a more modest 3.3% sequentially to ₹1.56 crore. The real tension is in the margins: the net profit margin fell 220 basis points year-on-year to 8.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 17.72YoY +52% | 16.75 | 11.67 |
| Profit (₹ Cr) | 1.56YoY +22% | 1.51 | 1.28 |
| Net Profit Margin (%) | 8.8YoY -20% | 9.0 | 11.0 |
Why the profit didn't keep up
Strong volume growth in the specialty chemicals segment drove the sales jump, according to a scanx.trade report. But total expenses grew 54.9% year-on-year, outpacing the 51.8% revenue rise. MarketsMojo notes this signals rising cost pressures that eroded profitability despite the scale expansion.
Interest expense rose 60% from a year ago, though from a low base. Other income, which provided a cushion last quarter, fell 42% sequentially. The result is a business growing sales rapidly but seeing little operating leverage.
A market waiting for quality
Investors have been skeptical. The stock has underperformed the sector over the past year, MarketsMojo reports, and carries a 'Sell' rating from that platform. A key concern is the near-total absence of institutional shareholders, which the outlet suggests reflects professional doubts about return ratios and margin sustainability.
Management has not provided explicit growth or margin targets, StockFin.ai notes. The focus appears to be on operational stability rather than aggressive expansion.
Key Points
- Revenue growth of 52% YoY was driven by strong volume gains in the core specialty chemicals segment.
- Profitability weakened as total expenses grew faster than sales, compressing the net profit margin by 220 basis points.
- The stock's underperformance and lack of institutional interest highlight market concerns over the quality and sustainability of earnings growth.
Hexa Perspective
The quarter confirms Eiko Lifesciences can generate impressive top-line momentum in its new chemical avatar. The worry is what comes next.
For the growth to create value, margins must stabilize and expand. That requires either pricing power, which is constrained in a competitive sector, or sharper cost control. With no clear guidance on capacity expansion or strategic initiatives, the path to improved returns remains uncertain. The valuation discount reflects this wait-and-see reality.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.