Enviro Infra Engineers (EIEL) Q2 FY27 Profit Drops 20% Despite 60% Revenue Surge
The water and renewable EPC firm posted a sharp 60% jump in quarterly revenue, but higher costs and interest expenses dragged net profit down by a fifth.
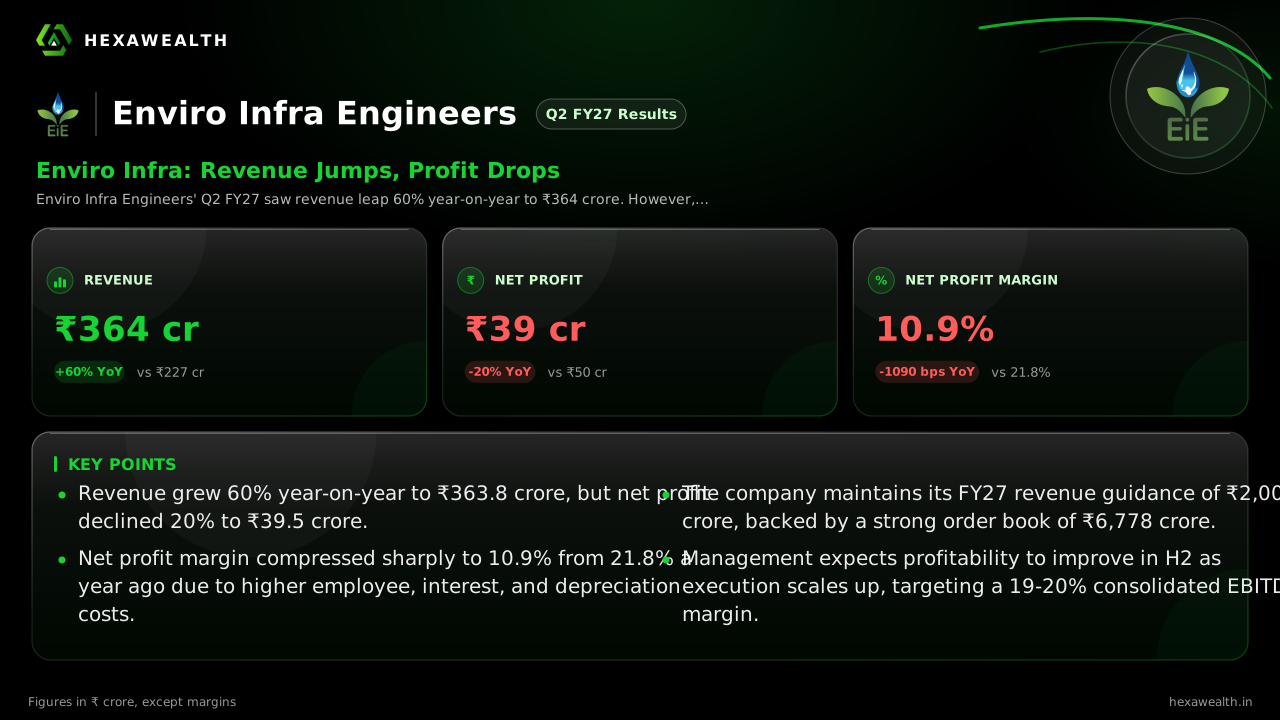
Enviro Infra Engineers' Q2 FY27 saw revenue leap 60% year-on-year to ₹364 crore. However, net profit fell 20% to ₹39.5 crore as project mix changes and a surge in interest and employee costs compressed margins.
For Enviro Infra Engineers, the September quarter was a story of scale arriving before profitability. The company’s consolidated revenue surged 60% year-on-year, crossing ₹363 crore. Yet, net profit fell 20% to ₹39.5 crore, revealing the cost of that rapid expansion.
The numbers show a clear divergence. Revenue growth was robust, but the net profit margin nearly halved to 10.9% from 21.8% a year ago. Sequentially, profit also fell 13% even as revenue inched up 1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 363.77YoY +60% | 359.18 | 227.35 |
| Profit (₹ Cr) | 39.49YoY -20% | 45.21 | 49.50 |
| Net Profit Margin | 10.9%YoY -50% | 12.6% | 21.8% |
Why Margins Collapsed Under Growth
The profit squeeze came from three fronts. First, employee costs more than doubled year-on-year as project execution ramped up. Second, interest expense jumped 144% to ₹18 crore, driven by higher borrowings for new projects and the acquisition of Suyog Urja.
Third, the project mix shifted. The faster-growing renewable energy segment, which contributed 29% of H1 revenue, operates at lower margins than the core water business. Management also cited accounting entries for the Suyog acquisition and profit reversals in IPP projects as temporary margin drags.
The Outlook Hinges on Execution
Management, in its earnings call covered by AlphaStreet, held its full-year sales guidance of ₹2,000 crore. It expects a significant revenue acceleration in the second half. The consolidated order book stands at a healthy ₹6,778 crore, providing clear visibility.
The key will be converting this backlog without further margin erosion. The company guided for a consolidated EBITDA margin of 19-20% for FY27, below the 28.6% seen in Q2 last year but an improvement from the current 20.6%.
Key Points
- Revenue grew 60% year-on-year to ₹363.8 crore, but net profit declined 20% to ₹39.5 crore.
- Net profit margin compressed sharply to 10.9% from 21.8% a year ago due to higher employee, interest, and depreciation costs.
- The company maintains its FY27 revenue guidance of ₹2,000 crore, backed by a strong order book of ₹6,778 crore.
- Management expects profitability to improve in H2 as execution scales up, targeting a 19-20% consolidated EBITDA margin.
Hexa Perspective
The quarter underscores the transition pains of a traditional EPC player scaling into capital-intensive renewables. Revenue momentum is undeniable, and the order book is strong. However, the margin profile has reset at a lower level, at least for this cycle.
The investment case now hinges on management's ability to execute the large backlog efficiently. Stabilising interest costs and improving the mix of revenue recognition in the coming quarters will be critical to see if the current valuation discount to the industry persists.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.