Emami (EMAMILTD) Q2 FY27's Revenue Surges 36% but Profit Stalls on Cost Squeeze
Emami's Q2 FY27 saw a 36% revenue surge driven by strong domestic volumes, but net profit slipped as input costs and a normalized tax rate squeezed margins.
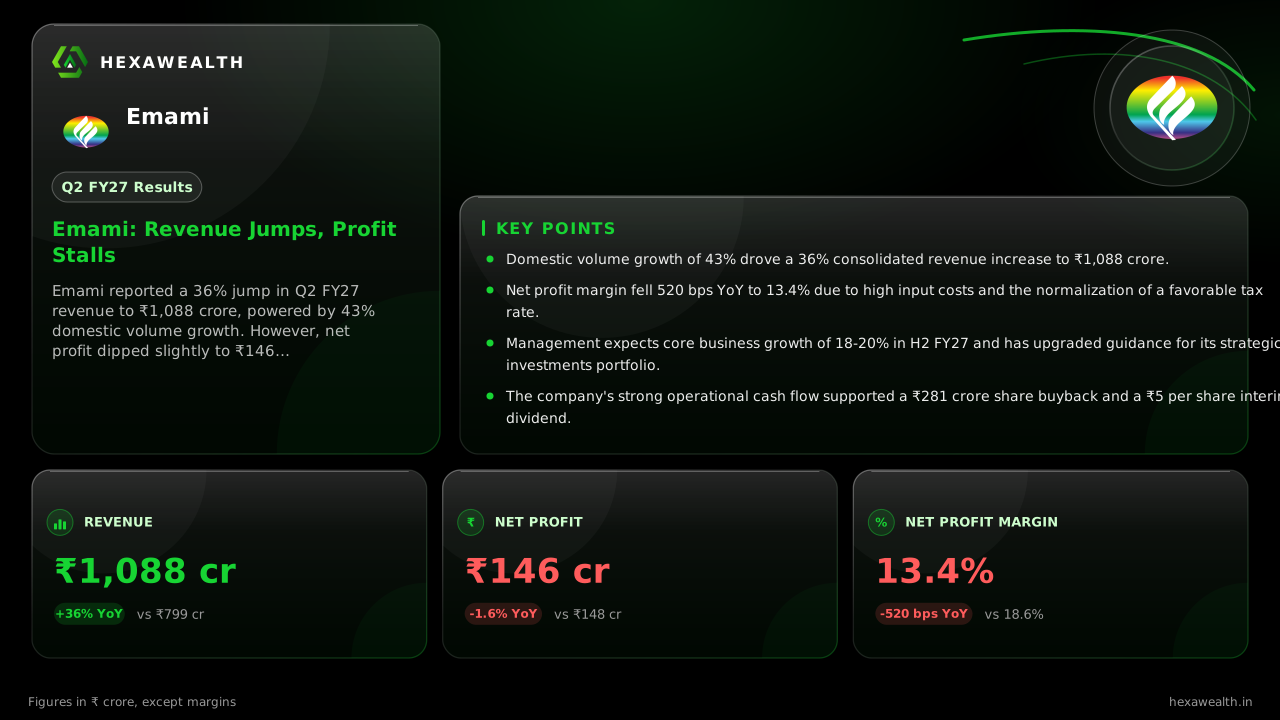
Emami reported a 36% jump in Q2 FY27 revenue to ₹1,088 crore, powered by 43% domestic volume growth. However, net profit dipped slightly to ₹146 crore as elevated input costs and the phase-out of a key tax benefit compressed margins.
Emami’s September quarter delivered the kind of top-line growth that defines a market leader, but the bottom line told a more complicated story of cost pressures catching up. Revenue surged 36% year-on-year to ₹1,088 crore, yet net profit inched down 1.6% to ₹146 crore, revealing a significant margin squeeze just as sales accelerated.
The numbers show a clear divergence. While revenue climbed sharply, the net profit margin contracted by 520 basis points to 13.4% compared to the same quarter last year. Sequentially, performance was steadier, with both revenue and profit growing around 5% from the June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1088.0YoY +36% | 1039.2 | 798.5 |
| Profit (₹ Cr) | 146.0YoY -1.6% | 138.9 | 148.4 |
| Net Profit Margin (%) | 13.4YoY -28% | 13.4 | 18.6 |
Why the profit didn't follow sales
The revenue engine was firing. According to ETRetail, domestic business grew 49%, powered by a remarkable 43% volume increase. Core brands like BoroPlus and Navratna oils led growth in skincare and haircare, while the strategic investments portfolio surged 73%.
Yet, this growth came at a cost. Total expenses rose 37% year-on-year. Business Standard reported that elevated input costs, particularly for raw materials, were a key pressure. Furthermore, the effective tax rate normalized after the phase-out of fiscal benefits at its Assam unit, which had flattered profits in the year-ago period.
The outlook and the market's read
Management, in its earnings call, expressed confidence. They guided for 18-20% core business growth in the second half of FY27 and raised the revenue target for strategic investments to ₹800-850 crore for the full year. The company expects to benefit from input cost corrections ahead.
The stock market offered a vote of cautious confidence. According to BusinessToday, Emami's share price rose 3% following the results announcement, buoyed by the strong revenue beat and a declared interim dividend of ₹5 per share.
Key Points
- Domestic volume growth of 43% drove a 36% consolidated revenue increase to ₹1,088 crore.
- Net profit margin fell 520 bps YoY to 13.4% due to high input costs and the normalization of a favorable tax rate.
- Management expects core business growth of 18-20% in H2 FY27 and has upgraded guidance for its strategic investments portfolio.
- The company's strong operational cash flow supported a ₹281 crore share buyback and a ₹5 per share interim dividend.
Hexa Perspective
Emami’s quarter underscores a transition. The company is successfully building new growth engines and gaining volume share, as evidenced by the stellar domestic performance. However, profitability is in a reset phase, caught between commodity inflation and a changing business mix toward newer, digital-first brands.
The path forward hinges on two factors: the expected easing of input costs and the company's ability to improve the margin profile of its high-growth strategic portfolio. If commodity trends cooperate and execution remains sharp, the current revenue momentum could start translating more fully to the bottom line in the coming quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.