Entero Healthcare (ENTERO) Q2 FY27 Profit Jumps 66% as Scale Outpaces Soaring Interest Costs
Entero Healthcare's Q2 FY27 profit surged 66% YoY to ₹60.7 crore, driven by 33% revenue growth, but a near-doubling of interest expense highlights the cost of its acquisition-led expansion.
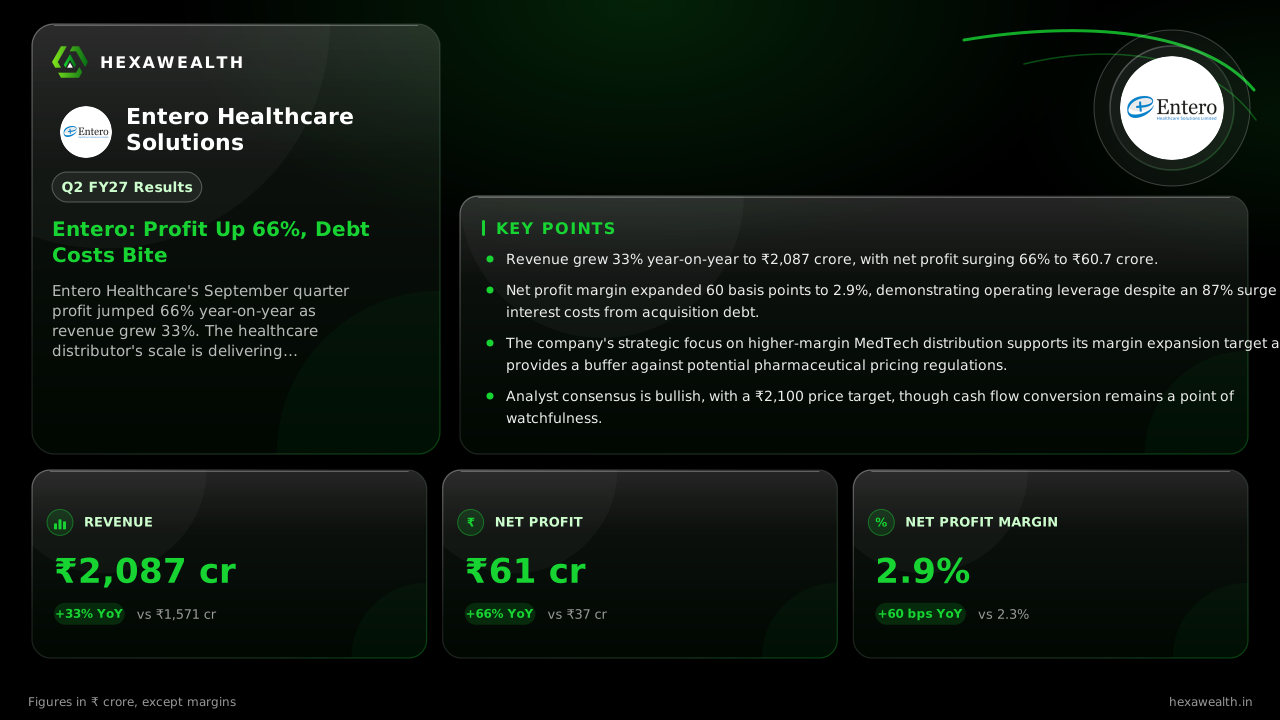
Entero Healthcare's September quarter profit jumped 66% year-on-year as revenue grew 33%. The healthcare distributor's scale is delivering margin gains, but interest costs have nearly doubled due to acquisition debt.
For Entero Healthcare, the story is one of scale finally paying off. The healthcare distributor's September quarter shows revenue growth translating into profit at a faster clip, even as the cost of funding its aggressive expansion lands on the income statement.
Revenue rose 33% year-on-year to ₹2,087 crore, while net profit jumped 66% to ₹60.7 crore. The net profit margin expanded to 2.9%, up 60 basis points from a year ago. This marks a steady climb in profitability over the past five quarters.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,087.07YoY +33% | 1,940.49 | 1,570.95 |
| Profit (₹ Cr) | 60.74YoY +66% | 52.05 | 36.60 |
| Net Profit Margin | 2.9%YoY +26% | 2.7% | 2.3% |
The margin gain that beat the interest surge
Profit growth far outpaced revenue, pointing to operating leverage. According to Quartr, gross margin expanded 147 basis points year-on-year in the previous quarter, a trend that likely continued. This efficiency gain was enough to offset a major headwind: interest expense surged 87% year-on-year to ₹23.1 crore.
Management had flagged this increase in the Q1 call, attributing it to the full-quarter impact of a ₹200 crore debt taken for an acquisition late in the prior fiscal year. Executives said on the earnings call that interest costs are now expected to stay broadly stable, according to InvestorStack.
The MedTech pivot and a watchful market
The strategic push into higher-margin medical technology distribution is central to the margin story. Management targets over ₹1,000 crore in MedTech revenue this fiscal year, as noted by Quartr. This shift helps insulate the business from potential regulatory pressure on pharmaceutical trade margins, a topic under Supreme Court scrutiny.
Analyst sentiment remains positive. Sharpely data shows a consensus target price of ₹2,100, implying significant upside, with all three covering analysts having a Buy or Strong Buy rating. The market will watch for any guidance upgrade after this strong quarter, as management had hinted it might do.
Key Points
- Revenue grew 33% year-on-year to ₹2,087 crore, with net profit surging 66% to ₹60.7 crore.
- Net profit margin expanded 60 basis points to 2.9%, demonstrating operating leverage despite an 87% surge in interest costs from acquisition debt.
- The company's strategic focus on higher-margin MedTech distribution supports its margin expansion target and provides a buffer against potential pharmaceutical pricing regulations.
- Analyst consensus is bullish, with a ₹2,100 price target, though cash flow conversion remains a point of watchfulness.
Hexa Perspective
Entero's quarter confirms the model: revenue scale is driving margin improvement. The 60-basis-point yearly margin expansion, even with interest costs nearly doubling, shows underlying operating strength.
The catch is that this growth has been debt-funded. While interest costs are now expected to plateau, the balance sheet has taken on leverage to acquire scale. The next test is converting this earnings growth into consistent operating cash flow, which was negative in the first half according to TradingView. If cash generation aligns with profits, the rerating case strengthens. If not, the high P/E of 47, a 24% premium to the industry, will face scrutiny.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.