All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 14 November 20262 min read

EverestIMS (EIMS) Q2 FY25 Profit Margin Narrows in a Growing IT Services Market

The IT infrastructure management firm posted a net profit margin of 17.4% for the September quarter, below its annual average, as expenses rose.

By Anant Kacholia, HexaWealth Research · Created 14 November 2026

EverestIMS Technologies reported a net profit of ₹4 crore on revenue of ₹23 crore for Q2 FY25. The net profit margin of 17.4% reflects a squeeze compared to the annual figure, amidst a robust domestic IT services market.

For EverestIMS Technologies, a specialist in IT infrastructure and service management software, the September quarter presented a mixed picture. The company reported steady revenue but saw profitability compress, a trend that underscores the cost pressures of scaling in a competitive sector.

The half-year ended September 2024 saw revenue of ₹23 crore and a net profit of ₹4 crore. This translates to a net profit margin of 17.4%, notably below the 20.2% margin the company achieved for the full year ended March 2026.

Period (Half-Year Ended)Revenue (₹ Cr)Net Profit (₹ Cr)Net Profit Margin
Sep 202423.04.017.4%

The Margin Pressure Behind the Numbers

The quarter's margin dip points to rising operational costs. Screener.in data shows operating expenses for the half-year stood at ₹16 crore. This kept the operating profit margin healthy at 31%, but depreciation and taxes ultimately narrowed the bottom line.

A key factor is the company's strategic shift toward larger corporate contracts. As noted in an IPO analysis by ipovista.com, this move has extended payment cycles, tying up more working capital. Trade receivables days stretched to 249 in FY26, pressuring cash conversion.

Growth Levers in a Supportive Market

Despite near-term pressures, the fundamental demand environment is strong. IDC reports India's domestic IT services market grew 7.2% in 2024, with managed services leading at 7.4%. EverestIMS's Infraon suite, targeting this very segment, is positioned in a market projected to grow at a 10% CAGR.

Live Chart

· EIMS

(BSE)

ISIN: INE0YUW01020

The company's order book, reported at ₹39.1 crore as of August 2026 by newboard.in, provides visibility. However, revenue remains highly concentrated, with the top five customers accounting for 76% of FY26 sales, a risk factor highlighted in the company's prospectus.

Key Points

  • EverestIMS reported a net profit margin of 17.4% for H1 FY25, below its annual average of 20.2%.
  • The margin compression is linked to higher operational expenses and elongated working capital cycles from large contracts.
  • The company operates in a growing domestic IT services market, with its order book offering near-term revenue visibility.
  • High customer concentration remains a significant business risk.

Hexa Perspective

This quarter highlights the execution challenge for EverestIMS: converting top-line opportunity into sustained bottom-line growth. The margin squeeze is not from a weak market but from the costs of pursuing it—longer receivables and the investments needed to serve large clients.

The path forward hinges on whether operational leverage kicks in as these large contracts mature and revenue scales. Investors are weighing the company's solid market positioning against these profitability and concentration risks, reflected in its stock trading at a discount to the industry PE.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
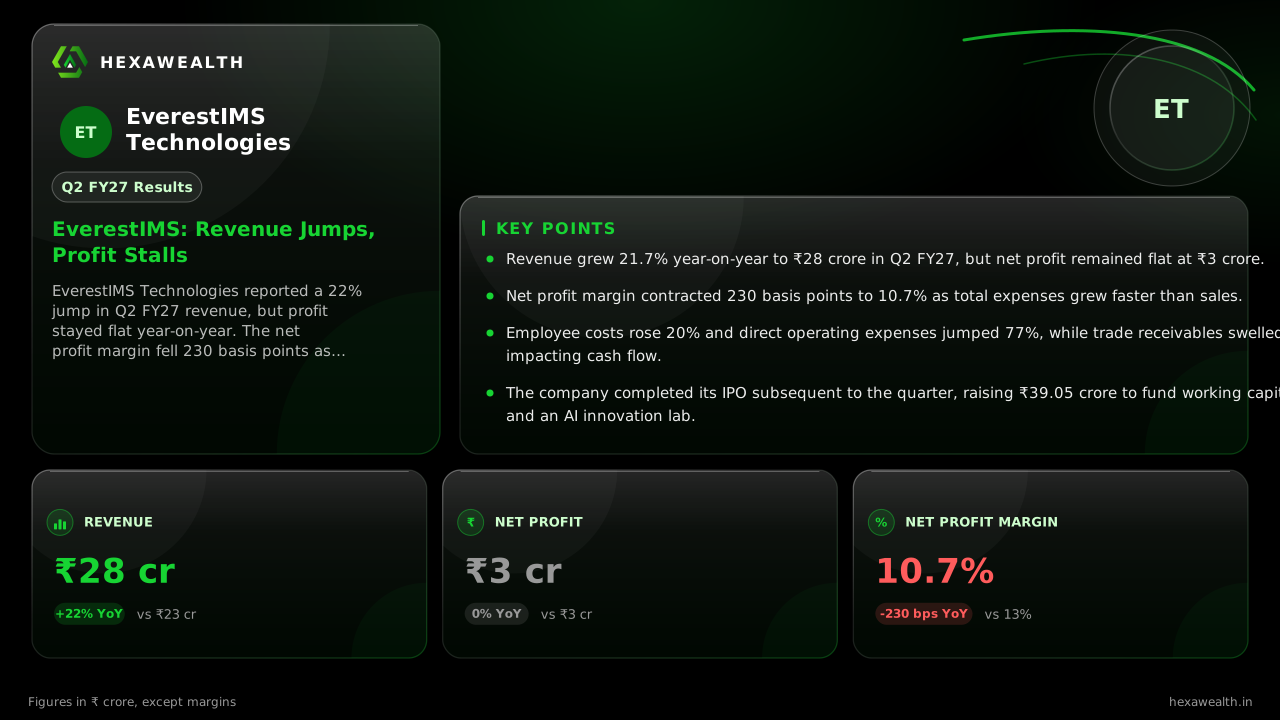
EverestIMS Technologies (EIMS) Q2 FY25 results, revenue and profits.

Frequently asked questions

What were EverestIMS Technologies' Q2 FY25 results?
For the half-year ended September 2024 (Q2 FY25), EverestIMS Technologies reported revenue of ₹23 crore and a net profit of ₹4 crore. The company's net profit margin for the period was 17.4%.
Why did EverestIMS Technologies' net profit margin decline to 17.4% in Q2 FY25?
EverestIMS's net profit margin of 17.4% for H1 FY25 was below its annual average due to higher operational expenses. The company's strategic shift to larger contracts has also extended payment cycles, increasing working capital requirements and pressuring profitability.
Did EverestIMS Technologies' Q2 FY25 profit include any one-time items?
Based on financial data from newboard.in, the profit for the period does not appear to include significant exceptional items. The profit before tax of ₹5 crore flowed from operating income, with no other income reported.
What is the growth outlook for EverestIMS Technologies' Infraon product suite?
The Infraon suite operates in the growing IT infrastructure management segment. IDC reports India's managed services market, a key segment for Infraon, grew 7.4% in 2024 and is projected for strong growth, driven by digital transformation and cloud adoption.
What were the order inflows and backlog for EverestIMS Technologies in Q2 FY25?
While specific Q2 inflows are not detailed, the company's order book stood at ₹39.1 crore as of August 31, 2026, as reported by newboard.in. This provides revenue visibility but is considered relatively thin at 0.6 times FY26 revenue.
What are EverestIMS Technologies' planned capital expenditures for FY25?
As per its IPO plans, a significant portion of capital is earmarked for working capital requirements (₹24 crore). The company also plans to spend ₹6 crore to set up an Artificial Intelligence Innovation and Experience Laboratory.
What are the key client concentration risks for EverestIMS Technologies?
Client concentration is a major risk. According to IPO analysis, the top five customers contributed 76.1% of FY26 revenue, and the largest single customer accounted for 29.6%. This makes the business vulnerable to the loss of any key account.
Did EverestIMS Technologies' Q2 FY25 results beat analyst estimates?
Available research from sources like Moneycontrol indicates no specific analyst estimates or beats/misses data were published for EverestIMS's Q2 FY25 results at the time of the announcement.
Have any major brokerages changed their rating for EverestIMS after Q2 results?
There is no information in the research about major brokerages issuing or changing ratings or target prices for EverestIMS Technologies following the Q2 FY25 results announcement.
Did institutional investors increase their stake in EverestIMS in Q2 FY25?
Shareholding data shows Foreign Institutional Investors (FIIs) held a 1.70% stake as of October 2026, a new entry since the previous quarter. Domestic Institutional Investors (DIIs) held 12.10%, while promoter holding remained steady at 58.98%.
EverestIMS Technologies Q2 FY25 results August 2026
EverestIMS Technologies announced its results for the half-year ended September 2024 (Q2 FY25) in November 2024. The company reported revenue of ₹23 crore and a net profit of ₹4 crore for the period.
Why did EverestIMS Technologies profits?
EverestIMS Technologies reported a net profit of ₹4 crore on revenue of ₹23 crore for H1 FY25. The net profit margin of 17.4% was below its annual average, reflecting pressure from operational expenses and elongated working capital cycles.