Eppeltone Engineers (EEPL) Q2 FY27 Profit Slips 13% as Revenue Growth Stalls
Eppeltone Engineers posted a 13% drop in quarterly profit as a sharp revenue contraction and rising costs squeezed margins, despite a small year-on-year sales gain.
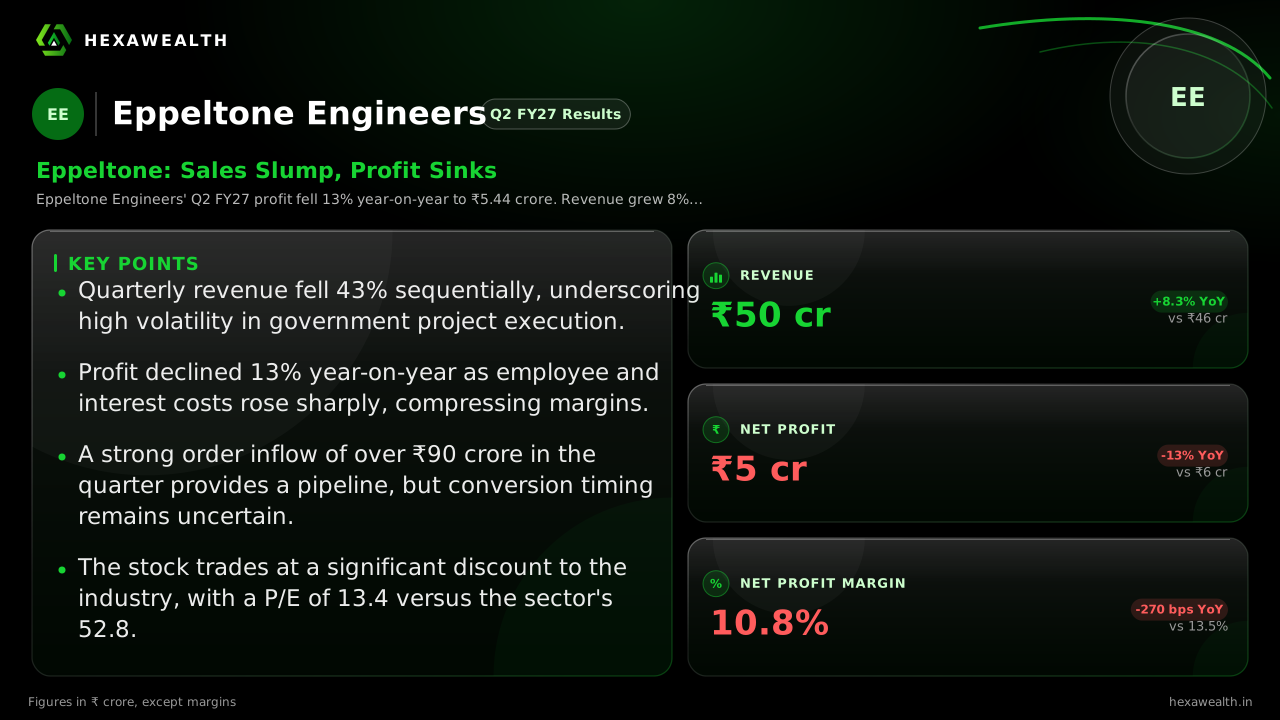
Eppeltone Engineers' Q2 FY27 profit fell 13% year-on-year to ₹5.44 crore. Revenue grew 8% but collapsed 43% from the prior quarter, highlighting volatile execution in its government-driven smart meter business.
For a company built on government tenders, quarterly revenue can swing wildly with project timing. Eppeltone Engineers’ September quarter showed that volatility in full force, with sales plunging from a March-quarter peak and leaving profit lower despite a small year-on-year gain.
The numbers tell a story of a sharp sequential slowdown. Revenue of ₹50.14 crore was up 8.3% from a year ago but collapsed 43.3% from the ₹88.47 crore posted in Q4 FY26. Profit followed, falling 13.1% year-on-year to ₹5.44 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 46.28
- Revenue (₹ Cr), Q4 FY26: 88.47
- Revenue (₹ Cr), Q2 FY27: 50.14
- Profit (₹ Cr), Q2 FY26: 6.26
- Profit (₹ Cr), Q4 FY26: 6.12
- Profit (₹ Cr), Q2 FY27: 5.44
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 46.28
- Revenue (₹ Cr), Q4 FY26: 88.47
- Revenue (₹ Cr), Q2 FY27: 50.14
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 6.26
- Profit (₹ Cr), Q4 FY26: 6.12
- Profit (₹ Cr), Q2 FY27: 5.44
Net Profit Margin %
- Net Profit Margin %, Q2 FY26: 13.5
- Net Profit Margin %, Q4 FY26: 6.9
- Net Profit Margin %, Q2 FY27: 10.8
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 50.14YoY +8.3% | 46.28 |
| Profit (₹ Cr) | 5.44YoY -13% | 6.26 |
| Net Profit Margin % | 10.8YoY -20% | 13.5 |
Why margins tightened on both sides
Profitability was squeezed from above and below. The net profit margin of 10.8% improved from the prior quarter but remained 270 basis points lower than a year ago. A 27% jump in employee costs and an 86% surge in interest expense, as reported by Stockscans, ate into earnings.
These rising costs reflect investment for future growth. The company is staffing up and funding a new 60,000 sq. ft. automated plant, expected operational by mid-FY27. Interest costs have risen with borrowings for this expansion.
The order book versus revenue recognition
A robust order pipeline offers a counter-narrative. According to ScanX, Eppeltone secured ₹92.93 crore of orders in Q2 FY27, following ₹118.50 crore in Q1. Yet trailing revenue appears disconnected, a gap the company attributes to the lumpy nature of government project execution and recognition.
Live Chart
· EEPL
(BSE)
ISIN: INE11HF01010
This execution volatility is a known risk. Management has previously cited monsoon-related delays, and the business model involves long working capital cycles with government clients. The current quarter’s slump appears to be a timing issue within that cycle.
Key Points
- Quarterly revenue fell 43% sequentially, underscoring high volatility in government project execution.
- Profit declined 13% year-on-year as employee and interest costs rose sharply, compressing margins.
- A strong order inflow of over ₹90 crore in the quarter provides a pipeline, but conversion timing remains uncertain.
- The stock trades at a significant discount to the industry, with a P/E of 13.4 versus the sector's 52.8.
Hexa Perspective
The quarter highlights the core tension in Eppeltone’s model: a promising order book backed by India’s smart meter push, versus erratic quarterly revenue and rising fixed costs. The 86% jump in interest and 27% rise in employee costs are not transient; they are the price of capacity built for a larger future.
Investors are weighing whether the current slump is a pause before the new plant comes online and order conversion accelerates, or a sign of persistent execution drag. The valuation discount suggests the market is pricing in the latter, awaiting more consistent proof that orders translate smoothly into sales and that margins can hold.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.