Conart Engineers (CONART) Q2 FY27 Profit Rises 39% on 71% Revenue Surge, But Margins Narrow
The construction firm's quarterly revenue hit a record high, though profitability was tempered by rising costs and a sharp drop in other income.
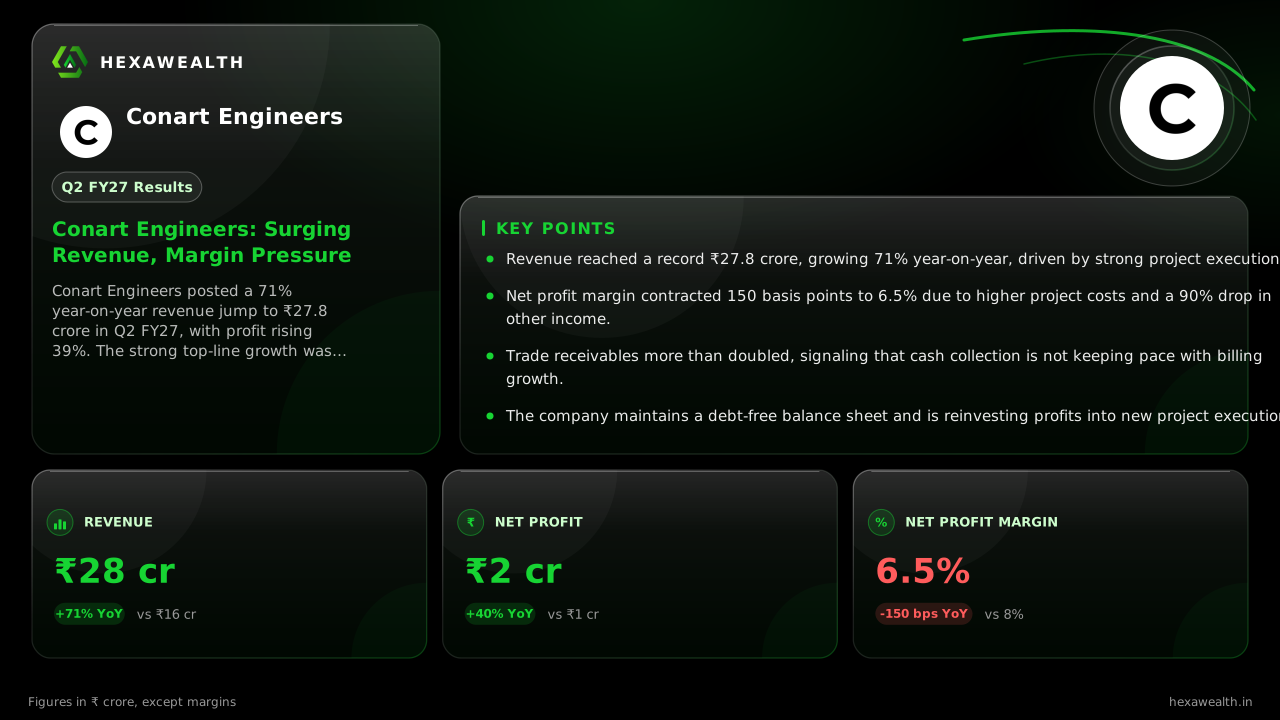
Conart Engineers posted a 71% year-on-year revenue jump to ₹27.8 crore in Q2 FY27, with profit rising 39%. The strong top-line growth was offset by a 150-basis-point contraction in net profit margin.
For Conart Engineers, a micro-cap construction specialist, growth is measured in project completions and cash collection. The September quarter delivered a powerful surge in the first, with revenue hitting a record ₹27.8 crore, a 71% leap from a year ago. Yet, the profitability story was more nuanced, as margins narrowed despite the operational scale.
The numbers tell a story of accelerating momentum with a cost. Profit after tax grew 39% year-on-year to ₹1.8 crore, but the net profit margin contracted by 150 basis points to 6.5%. Sequentially, the rebound from a soft Q1 was dramatic, with profit soaring 157% on a 38% revenue increase.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 27.80YoY +71% | 20.08 | 16.23 |
| Profit (₹ Cr) | 1.80YoY +40% | 0.70 | 1.29 |
| Net Profit Margin (%) | 6.5YoY -19% | 3.5 | 8.0 |
Why the profit lagged behind sales
Two forces held back the bottom line. First, other income collapsed by 90% year-on-year, removing a ₹0.41 crore tailwind from the year-ago quarter. Second, project costs rose sharply. According to a scanx.trade report, construction expenses and material costs jumped in line with revenue, pressuring margins.
The quarter's strength came from robust project execution, as noted by MarketsMojo. This operational leverage helped operating margin expand nearly 500 basis points sequentially to 9.46%. However, the year-on-year comparison shows that pure project economics are running leaner than before.
The cash collection challenge
A critical footnote to the revenue surge is working capital. Trade receivables more than doubled to ₹20.29 crore since March, reports scanx.trade. This indicates cash collection is lagging far behind billing, a typical stress point when a construction firm scales quickly.
Despite this, the balance sheet remains a fortress with virtually no debt, a point highlighted by MarketsMojo. The company is funding this growth internally, which provides stability but puts the onus on converting sales into cash.
The road ahead
Management has signaled a reinvestment phase, prioritizing project execution and working capital over dividends. Recent order wins, including a ₹15.41 crore contract from Apothecon Pharmaceuticals and a ₹49 crore order from Hindalco, provide near-term visibility.
The stock reacted positively, rising 6.4% to ₹94 following the results, notes MarketsMojo. Investors are betting the margin recovery from Q1 is sustainable. The coming quarters will test whether this revenue momentum and cash conversion can align.
Key Points
- Revenue reached a record ₹27.8 crore, growing 71% year-on-year, driven by strong project execution.
- Net profit margin contracted 150 basis points to 6.5% due to higher project costs and a 90% drop in other income.
- Trade receivables more than doubled, signaling that cash collection is not keeping pace with billing growth.
- The company maintains a debt-free balance sheet and is reinvesting profits into new project execution.
Hexa Perspective
This quarter marks an inflection in scale for Conart Engineers, but the quality of that growth is mixed. The record revenue and sequential margin rebound show operational leverage is working. Yet, the year-on-year margin squeeze and ballooning receivables introduce execution risk.
The valuation at a P/E of 14.9, a 46% discount to the industry, prices in this uncertainty. The outlook hinges on sustaining this execution pace while improving cash flow. If receivables stabilize and margins hold near current levels, the discount could narrow. If not, the strain from funding rapid growth will become the dominant story.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.