Centum Electronics (CENTUM) Q2 FY27 Profit Returns to Earth as Revenue Surges
The September quarter saw a 442% yearly profit jump, but a sharp sequential drop as a large one-off gain from Q1 faded into the background.
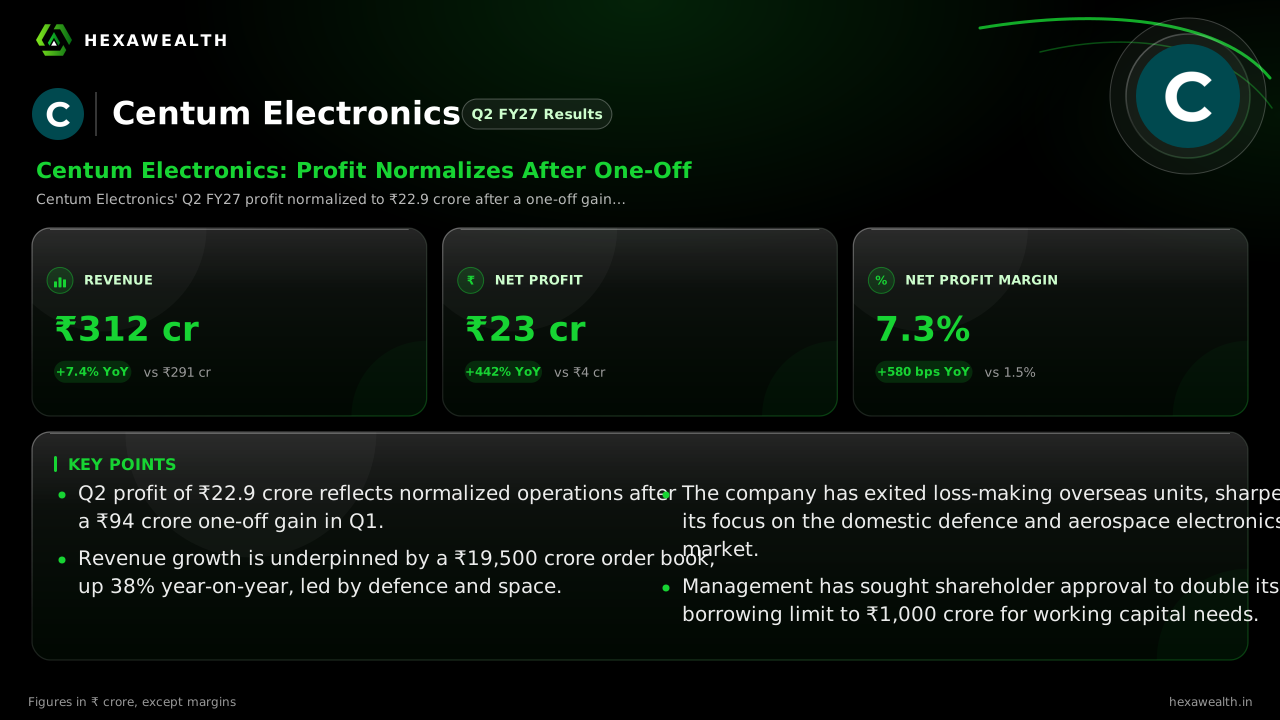
Centum Electronics' Q2 FY27 profit normalized to ₹22.9 crore after a one-off gain inflated the previous quarter. Revenue grew 7.4% yearly, supported by a robust ₹19,500 crore order book in defence and aerospace.
For Centum Electronics, the September quarter was about separating a one-time strategic gain from its underlying operating momentum. The company delivered solid revenue growth on the back of a surging order book, but its profit story is now defined by what came before.
The numbers show a business in transition. Revenue rose 7.4% year-on-year to ₹312.1 crore. Profit, however, tells two different tales: a 442% surge from a low base last year, but a steep 78% drop from the prior quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 312.06 | 204.15 |
| Profit (₹ Cr) | 22.93 | 105.50 |
| Net Profit Margin | 7.3% | 51.7% |
Why Q1's Profit Was an Outlier
The extreme margin in the June quarter was not from operations. According to reports from Multibagg.ai and others, it was primarily driven by a one-time ₹94 crore gain from the deconsolidation of overseas subsidiaries. This strategic exit cleared the decks but also set an impossible comparison for Q2, where the net profit margin normalized to 7.3%.
The Real Engine: Defence and Aerospace Demand
Strip away the one-off, and the core story is strong demand. The company's investor presentation, cited by Arthneeti.com, shows a standalone order book of ₹19,522 crore as of September, up 38% year-on-year. The Build-to-Specification segment, serving defence and space, saw Q2 revenue jump 84% yearly.
This growth is feeding through. Employee costs fell 56% year-on-year, partly due to the overseas exit, while interest expenses dropped 36%. The company's board has also proposed raising its borrowing limit to ₹1,000 crore to fund working capital for this expanding order pipeline.
A Focused Future on Home Turf
With the overseas restructuring complete, the focus is squarely on high-reliability electronics for Indian defence and global OEMs. Management had earlier guided for roughly 25% revenue growth this year, as noted in a Q1 call summary from Finance Yahoo. The current order book, with execution periods stretching over 2.5 years for some projects, provides clear visibility.
The path ahead hinges on converting this backlog smoothly. The company will need to manage the lumpy revenue recognition typical of large defence projects while navigating any supply chain pressures for critical components.
Key Points
- Q2 profit of ₹22.9 crore reflects normalized operations after a ₹94 crore one-off gain in Q1.
- Revenue growth is underpinned by a ₹19,500 crore order book, up 38% year-on-year, led by defence and space.
- The company has exited loss-making overseas units, sharpening its focus on the domestic defence and aerospace electronics market.
- Management has sought shareholder approval to double its borrowing limit to ₹1,000 crore for working capital needs.
Hexa Perspective
The quarter confirms Centum's strategic pivot is bearing fruit. The exit from overseas subsidiaries has removed a drag and cleaned up the cost structure, evident in the sharply lower employee and interest expenses. The real test now is execution.
The massive order book de-risks the top line but introduces the challenge of phased revenue recognition and working capital intensity. Investors are left weighing the certainty of long-term growth against the quarterly volatility inherent in this business model. The next few quarters will show if operating margins can stabilize in the double digits as project execution ramps up.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.