Bosch (BOSCHLTD) Q2 FY27 Profit Growth Trails a 60% Revenue Surge as Margins Narrow
Bosch's Q2 revenue jumped nearly 60% year-on-year, but profit growth of 52% and shrinking margins reveal the cost of rapid expansion.
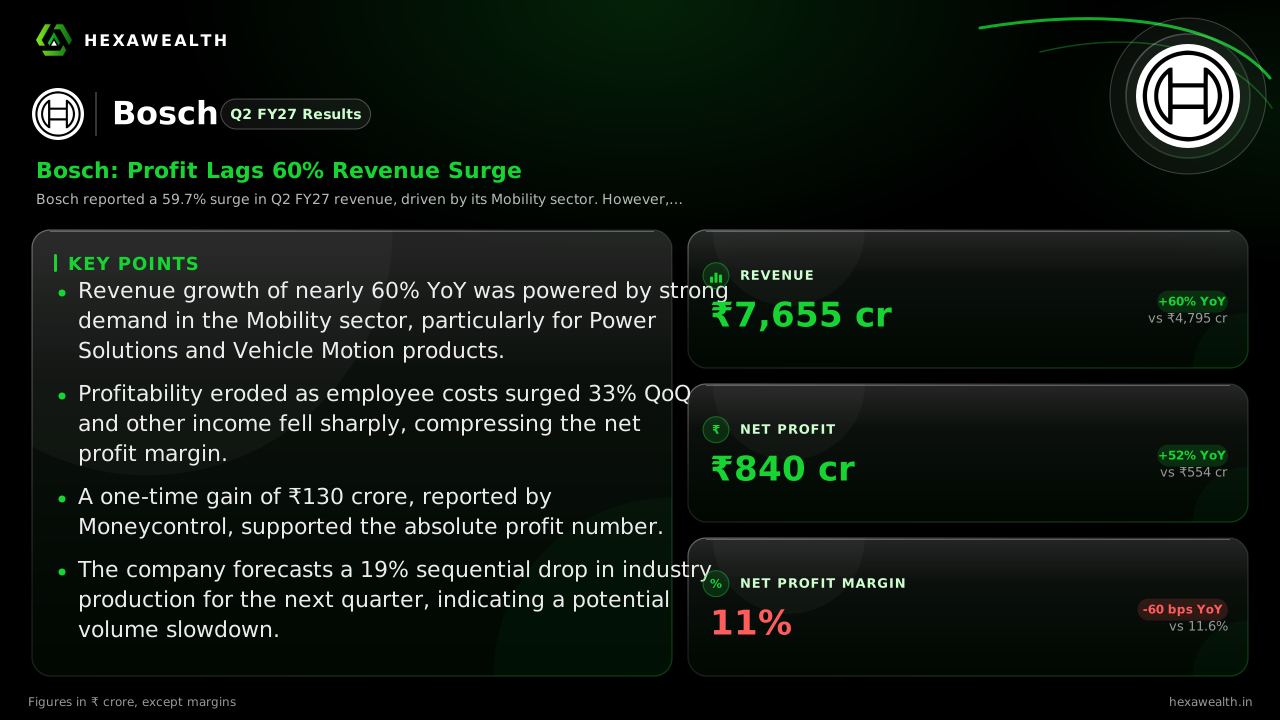
Bosch reported a 59.7% surge in Q2 FY27 revenue, driven by its Mobility sector. However, net profit grew at a slower 51.6% as margins contracted, weighed down by rising employee costs and lower other income.
For an auto components leader like Bosch, a quarter of explosive growth is a test of operating leverage. The September quarter delivered a top-line surge well ahead of the broader industry, but profitability told a more complex story.
Revenue soared 59.7% year-on-year to ₹7,655.1 crore, with profit after tax rising 51.6% to ₹840.5 crore. Sequentially, sales grew 31% from the June quarter, though profit grew only 19%. The net profit margin contracted 110 basis points from last quarter to 11.0%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 4,794.8
- Revenue (₹ Cr), Q3 FY26: 4,885.6
- Revenue (₹ Cr), Q4 FY26: 5,566.7
- Revenue (₹ Cr), Q1 FY27: 5,841.9
- Revenue (₹ Cr), Q2 FY27: 7,655.1
- Profit (₹ Cr), Q2 FY26: 554.5
- Profit (₹ Cr), Q3 FY26: 532.6
- Profit (₹ Cr), Q4 FY26: 570.0
- Profit (₹ Cr), Q1 FY27: 706.1
- Profit (₹ Cr), Q2 FY27: 840.5
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 4,794.8
- Revenue (₹ Cr), Q3 FY26: 4,885.6
- Revenue (₹ Cr), Q4 FY26: 5,566.7
- Revenue (₹ Cr), Q1 FY27: 5,841.9
- Revenue (₹ Cr), Q2 FY27: 7,655.1
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 554.5
- Profit (₹ Cr), Q3 FY26: 532.6
- Profit (₹ Cr), Q4 FY26: 570.0
- Profit (₹ Cr), Q1 FY27: 706.1
- Profit (₹ Cr), Q2 FY27: 840.5
Net Profit Margin
- Net Profit Margin, Q2 FY26: 11.6%
- Net Profit Margin, Q3 FY26: 10.9%
- Net Profit Margin, Q4 FY26: 10.2%
- Net Profit Margin, Q1 FY27: 12.1%
- Net Profit Margin, Q2 FY27: 11.0%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 7,655.1YoY +60% | 5,841.9 | 4,794.8 |
| Profit (₹ Cr) | 840.5YoY +52% | 706.1 | 554.5 |
| Net Profit Margin | 11.0%YoY -5.2% | 12.1% | 11.6% |
Why Profit Couldn't Keep Pace
The revenue engine was led by the Mobility Solutions division, where sales grew 29.8% year-on-year to ₹6,813 crore, according to a Multibagg.ai report. Power Solutions and Vehicle Motion grew over 34%, fueled by passenger car and commercial vehicle demand. Yet, this volume-driven expansion came with higher costs.
Employee expenses jumped 33.2% quarter-on-quarter, far outpacing revenue growth. This spike, alongside a 54% year-on-year plunge in other income, squeezed the bottom line. Moneycontrol noted the quarter included a one-time gain of ₹130 crore, which flatters the reported profit figure.
The Outlook Hinges on Volume
Management, cited by Multibagg.ai, pointed to pre-festive OEM demand and a favorable product mix for the quarter's strength. However, the near-term signal has turned. The company's own industry production forecast for Q3 FY27 is 2.299 million units, a 19% sequential drop from Q2.
Live Chart
· BOSCHLTD
(BSE)
ISIN: INE323A01026
This suggests the exceptional volume tailwind may be fading. The company's guidance, as per a pre-results note, was to sustain an EBITDA margin around 14%, a level the Q2 print did not reach.
Key Points
- Revenue growth of nearly 60% YoY was powered by strong demand in the Mobility sector, particularly for Power Solutions and Vehicle Motion products.
- Profitability eroded as employee costs surged 33% QoQ and other income fell sharply, compressing the net profit margin.
- A one-time gain of ₹130 crore, reported by Moneycontrol, supported the absolute profit number.
- The company forecasts a 19% sequential drop in industry production for the next quarter, indicating a potential volume slowdown.
Hexa Perspective
The quarter showcases Bosch's dominant positioning to capture automotive upcycles, with revenue growth dramatically outpacing the sector. Yet, the margin compression reveals the costs of scaling rapidly, including integration of newly consolidated units like Bosch Chassis Systems India.
The critical question is sustainability. With a forecast for lower industry production and persistent cost pressures, the impressive top-line growth may normalize. Investors are weighing this potential moderation against the company's strategic investments in EV and hydrogen technologies for the long term.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.