BASF India Q2 FY27 Profit Plunges 42% as Costs Overwhelm Sales Growth
The chemicals giant posted a 24% revenue jump in Q2 FY27, but net profit fell sharply as expenses surged and three of its six segments reported losses.
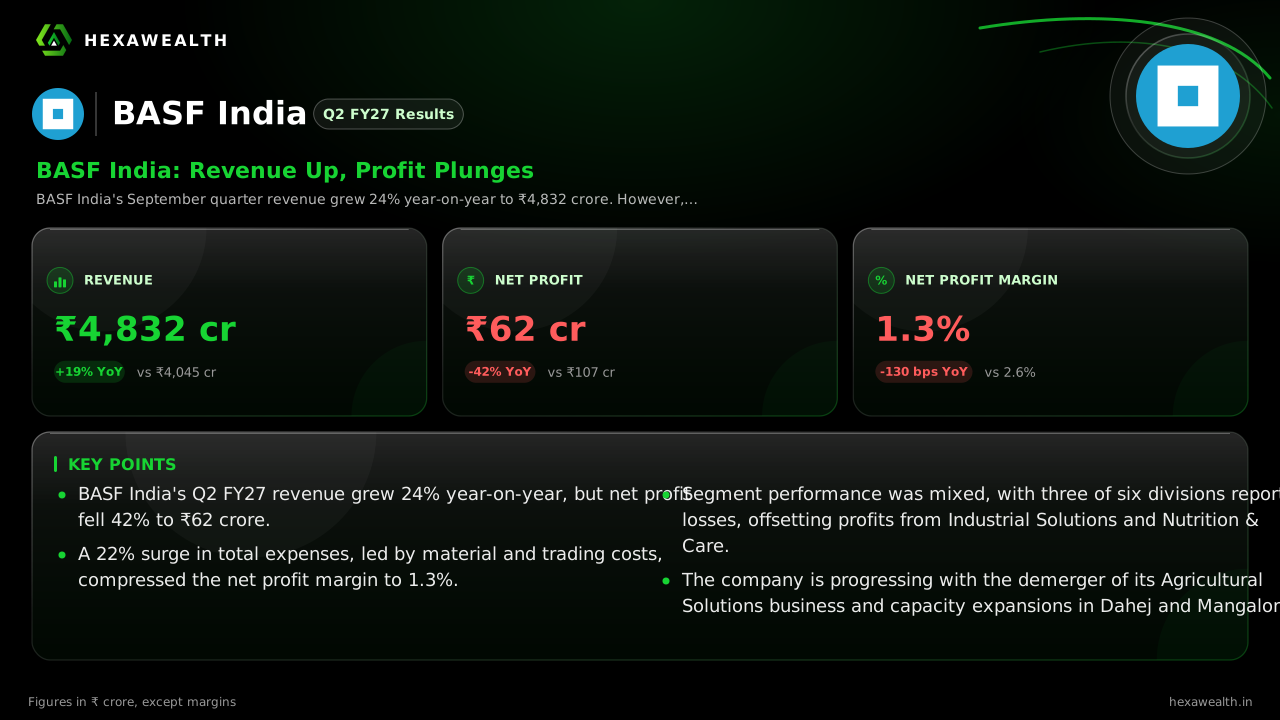
BASF India's September quarter revenue grew 24% year-on-year to ₹4,832 crore. However, net profit plunged 42% to ₹62 crore as total expenses rose faster than income, highlighting significant margin pressure.
For a diversified chemical company, a strong top line often signals healthy demand. BASF India's September quarter delivered that, with revenue up 24% year-on-year. Yet the bottom line tells a story of costs that raced ahead, leaving profit sharply lower and margins squeezed.
The numbers show a clear divergence. Revenue reached ₹4,832 crore, but net profit contracted to just ₹62 crore. This pushed the net profit margin down to 1.3%, a drop of 130 basis points from last year and a steep 620-point fall from the previous quarter. The half-year picture is brighter, with profit at ₹422 crore, but the quarterly swing is stark.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 4,832.0 | 4,824.3 |
| Net Profit (₹ Cr) | 62.0 | 360.3 |
| Net Profit Margin (%) | 1.3 | 7.5 |
Where the Profit Disappeared
The profit drop was not due to one-off items but a broad-based cost surge. According to reports from AngelOne and Multibagg.ai, total expenses jumped 22% year-on-year to ₹4,782 crore. This was driven by a ₹1,722 crore cost for materials consumed and ₹2,522 crore for purchases of stock-in-trade. Essentially, the company sold more, but it cost significantly more to make and source those goods.
A Split Segment Story
Revenue growth was led by the Materials and Nutrition & Care segments, reports AngelOne. However, profitability was deeply uneven. Only Industrial Solutions (₹84 crore) and Nutrition & Care (₹66 crore) reported a segment profit. The Materials, Agricultural Solutions, and Chemicals segments all posted losses, dragging down the consolidated result.
The Agricultural Solutions business, which is being demerged into a separate listed company, recorded a loss of ₹29 crore. Management has previously pointed to a volume recovery in the upcoming Rabi season, according to an earnings-call transcript cited by Arthneeti.
The Market's Measured Reaction
There was no specific management guidance with the results. The market reaction on the day, as per AngelOne, was a 1.64% share price increase to ₹3,189.50. The stock had already declined 33% over the past year, as of November 4, reflecting broader sector pressures and anticipation of this margin squeeze.
Key Points
- BASF India's Q2 FY27 revenue grew 24% year-on-year, but net profit fell 42% to ₹62 crore.
- A 22% surge in total expenses, led by material and trading costs, compressed the net profit margin to 1.3%.
- Segment performance was mixed, with three of six divisions reporting losses, offsetting profits from Industrial Solutions and Nutrition & Care.
- The company is progressing with the demerger of its Agricultural Solutions business and capacity expansions in Dahej and Mangalore.
Hexa Perspective
This quarter underscores the volatility in chemical sector earnings, where top-line growth does not automatically translate to the bottom line. The margin compression appears structural, linked to input cost dynamics and an unfavourable product mix, rather than a one-time event. The path forward hinges on whether the company can exercise pricing power or achieve operational efficiencies to protect margins. With key expansions underway and the agricultural demerger pending, BASF India is betting on strategic moves to unlock long-term value, but near-term profitability remains under clear pressure.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.