Azad Engineering (AZAD) Q2 FY27 Profit Falls as Expansion Costs Bite
The precision components maker posted record revenue but saw profit decline as heavy investment in new capacity and higher working capital costs hit the bottom line.
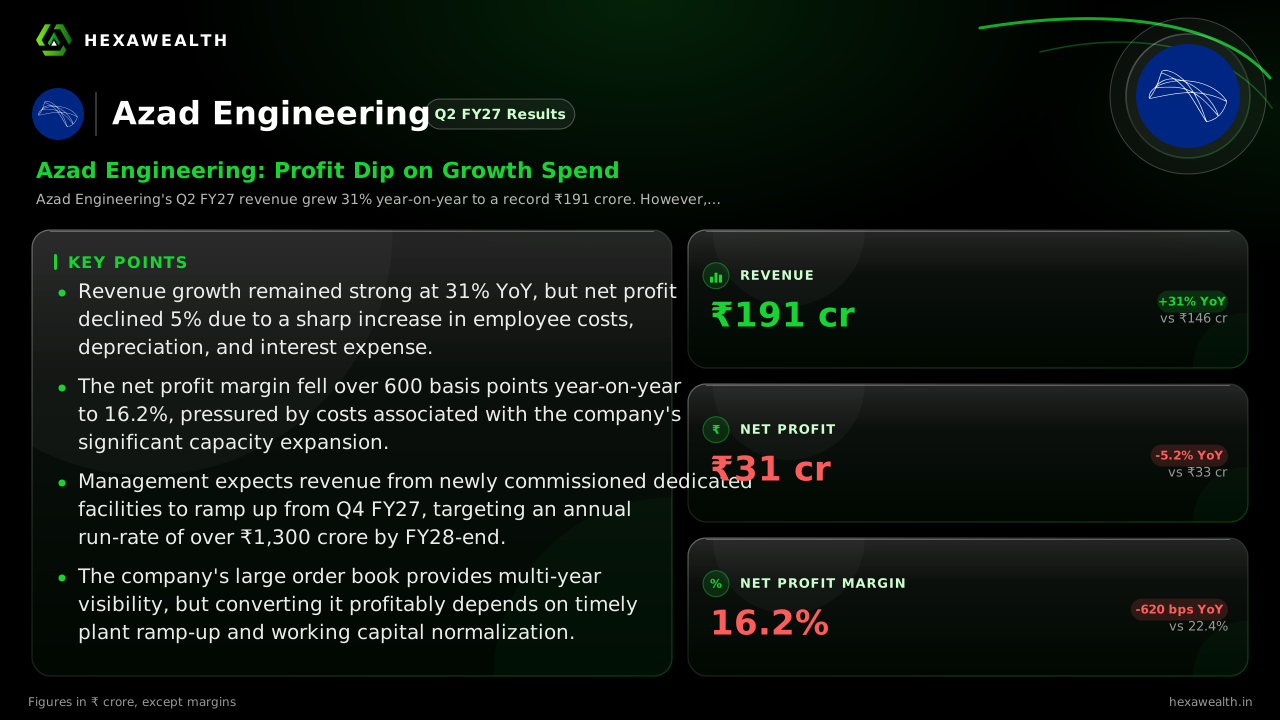
Azad Engineering's Q2 FY27 revenue grew 31% year-on-year to a record ₹191 crore. However, net profit fell 5% as a sharp rise in employee costs, depreciation, and interest expenses, tied to its capacity expansion, squeezed margins.
For Azad Engineering, the September quarter was a story of building for the future while paying for it today. The maker of mission-critical components for global giants like GE and Rolls-Royce delivered record revenue, but the profit that reached shareholders shrank as the bill for its aggressive capacity build-out came due.
Revenue rose 31% year-on-year to ₹191 crore, continuing a strong sequential climb. Yet net profit slipped 5% to ₹31 crore. This divergence is stark in the margin: the operating (EBITDA) margin expanded to 37.5%, but the net profit margin contracted by over 6 percentage points to 16.2%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 190.94YoY +31% | 172.60 | 145.62 |
| Profit (₹ Cr) | 30.93YoY -5.2% | 35.16 | 32.61 |
| Net Profit Margin | 16.2%YoY -28% | 20.4% | 22.4% |
The Costs That Ate the Profit
The profit squeeze came from three sources below the operating line, as reported by multibagg.ai. Employee costs surged 54% year-on-year as the company hired ahead of the revenue ramp. Depreciation nearly doubled with new facilities being capitalised, and finance costs jumped 86% on additional working-capital loans.
At the same time, other income fell 66%. The company attributed this to deploying IPO and QIP funds into capex, ending a period of high treasury income that had flattered profits a year ago.
A Revenue Pivot Awaits
Management, cited in reports, calls this the expected lag between investment and revenue. The company has inaugurated six customer-dedicated facilities, with the latest two for GE Vernova opened in September. The energy and oil & gas segment, contributing over 80% of revenue, remains the anchor.
The payoff is anticipated soon. Management expects throughput from the new plants to begin in Q3 FY27, with a revenue ramp from Q4. The target is an annual revenue run-rate exceeding ₹1,300 crore by the end of FY28.
The Market's Bet on Execution
Despite the profit dip, the stock has gained nearly 60% over the past year. Analysts like ICICI Securities maintain a buy rating, seeing the new capacity as addressing the principal constraint on growth against a robust order book reportedly over ₹6,500 crore. The valuation at a P/E of 72 reflects a premium for the anticipated execution.
The quarter confirms the investment phase is in full swing. The coming quarters will test if the revenue acceleration can outrun the rising cost curve, turning capacity into cash.
Key Points
- Revenue growth remained strong at 31% YoY, but net profit declined 5% due to a sharp increase in employee costs, depreciation, and interest expense.
- The net profit margin fell over 600 basis points year-on-year to 16.2%, pressured by costs associated with the company's significant capacity expansion.
- Management expects revenue from newly commissioned dedicated facilities to ramp up from Q4 FY27, targeting an annual run-rate of over ₹1,300 crore by FY28-end.
- The company's large order book provides multi-year visibility, but converting it profitably depends on timely plant ramp-up and working capital normalization.
Hexa Perspective
Azad Engineering's quarter lays bare the financial mechanics of a high-growth capex cycle. Operating efficiency is improving, but the P&L is absorbing the full cost of new plants before they contribute meaningfully to sales. The guidance for a second-half revenue inflection is now critical.
The investment case hinges on execution. If the new facilities ramp as planned, operating leverage should kick in, easing the margin pressure. The risk is that any delay in customer qualifications or working capital remaining elevated could prolong the profit squeeze, testing the market's patience with a rich valuation.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.