Avanti Feeds (AVANTIFEED) Q2 FY27 Profit Plunges 56% as Surging Feed Costs Crush Margins
The aquaculture leader's revenue grew 9% in Q2 FY27, but a 35% spike in raw material expenses led to a severe margin squeeze and a sharp profit decline.
Avanti Feeds reported a 56% drop in net profit for Q2 FY27 despite higher revenue. The collapse was driven by a severe margin squeeze, with raw material costs surging 35% year-on-year, far outpacing sales growth.
For India's leading shrimp feed maker, the September quarter was a story of costs overwhelming demand. Avanti Feeds managed to grow its top line, but the bottom line was gutted by a historic surge in raw material prices.
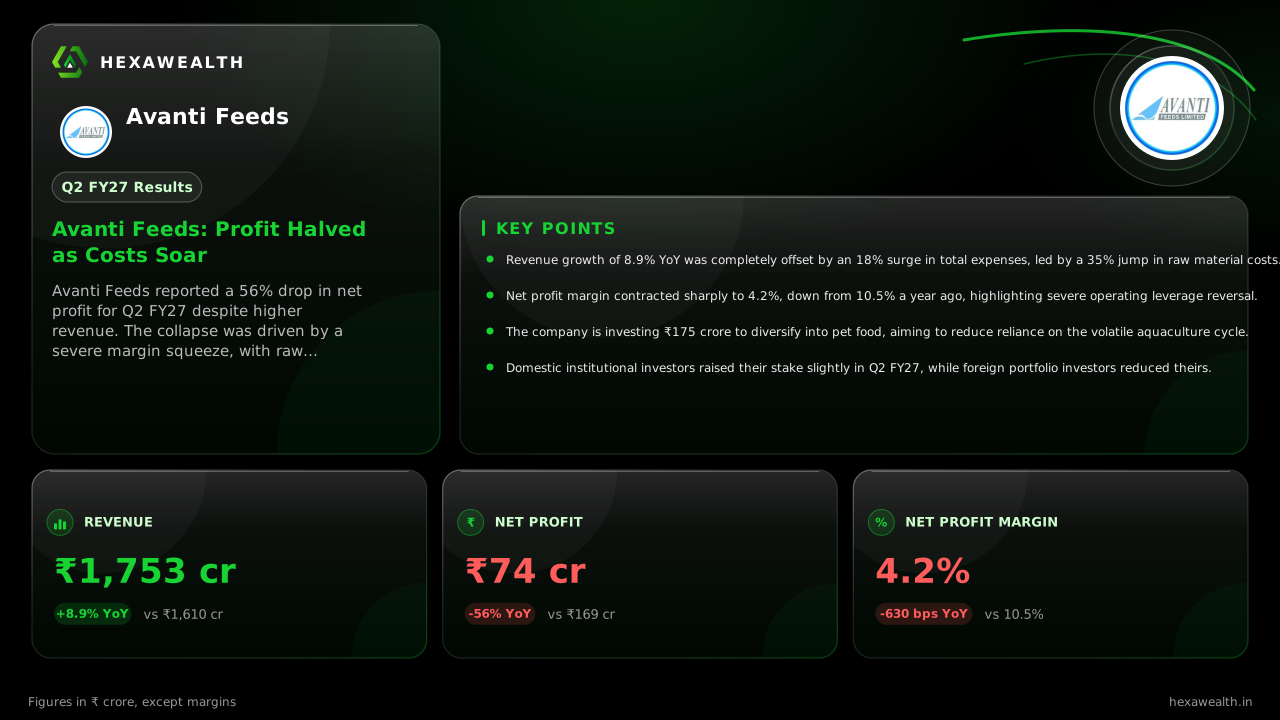
The numbers show a stark divergence. Revenue for Q2 FY27 rose 8.9% year-on-year to ₹1,752.52 crore. Net profit, however, collapsed by 56.2% to ₹73.92 crore. The net profit margin shrank to 4.2%, down 630 basis points from a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1,609.69
- Revenue (₹ Cr), Q3 FY26: 1,383.52
- Revenue (₹ Cr), Q4 FY26: 1,467.72
- Revenue (₹ Cr), Q1 FY27: 1,899.87
- Revenue (₹ Cr), Q2 FY27: 1,752.52
- Profit (₹ Cr), Q2 FY26: 168.79
- Profit (₹ Cr), Q3 FY26: 163.47
- Profit (₹ Cr), Q4 FY26: 138.86
- Profit (₹ Cr), Q1 FY27: 116.31
- Profit (₹ Cr), Q2 FY27: 73.92
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1,609.69
- Revenue (₹ Cr), Q3 FY26: 1,383.52
- Revenue (₹ Cr), Q4 FY26: 1,467.72
- Revenue (₹ Cr), Q1 FY27: 1,899.87
- Revenue (₹ Cr), Q2 FY27: 1,752.52
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 168.79
- Profit (₹ Cr), Q3 FY26: 163.47
- Profit (₹ Cr), Q4 FY26: 138.86
- Profit (₹ Cr), Q1 FY27: 116.31
- Profit (₹ Cr), Q2 FY27: 73.92
Net Profit Margin
- Net Profit Margin, Q2 FY26: 10.5%
- Net Profit Margin, Q3 FY26: 11.8%
- Net Profit Margin, Q4 FY26: 9.5%
- Net Profit Margin, Q1 FY27: 6.1%
- Net Profit Margin, Q2 FY27: 4.2%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,752.52YoY +8.9% | 1,899.87 | 1,609.69 |
| Profit (₹ Cr) | 73.92YoY -56% | 116.31 | 168.79 |
| Net Profit Margin | 4.2%YoY -60% | 6.1% | 10.5% |
Why margins collapsed
The profit plunge was not due to weak sales. According to reports from scanx.trade, the cost of materials consumed soared 35% year-on-year, far faster than revenue growth. This was driven by steep inflation in key ingredients like fish meal and soybean meal, a pressure management had flagged earlier.
A one-time charge of ₹1.71 crore for an Anti-Dumping Duty liability revision in a subsidiary also weighed on profit. The core issue, however, was an 18% jump in total expenses, which consumed nearly all the quarter's revenue gains.
The industry-wide cost crunch
This is not a company-specific problem. A report in The HinduBusinessLine notes shrimp feed prices have risen sharply due to El Niño affecting raw material availability. Farmers are spending more on feed without seeing better shrimp prices, squeezing the entire chain.
Live Chart
· AVANTIFEED
(BSE)
ISIN: INE871C01038
Feed manufacturers like Avanti are caught in the middle, unable to fully pass on costs. The company implemented a price hike in June, but it was insufficient to protect margins this quarter.
The path ahead and market reaction
Management's focus is on its diversification into pet food to reduce cyclicality. The company has guided for ₹175 crore in capital expenditure for a new plant, funded internally. Domestic institutional investors increased their stake slightly in the September quarter, as per shareholding data.
The stock's one-year return is negative 3.9%, reflecting the margin pressure. With a P/E of 26.3, it trades at a discount to the industry average, pricing in the current challenges.
Key Points
- Revenue growth of 8.9% YoY was completely offset by an 18% surge in total expenses, led by a 35% jump in raw material costs.
- Net profit margin contracted sharply to 4.2%, down from 10.5% a year ago, highlighting severe operating leverage reversal.
- The company is investing ₹175 crore to diversify into pet food, aiming to reduce reliance on the volatile aquaculture cycle.
- Domestic institutional investors raised their stake slightly in Q2 FY27, while foreign portfolio investors reduced theirs.
Hexa Perspective
The quarter confirms that input cost inflation, not demand, is the defining challenge for Avanti Feeds. The margin compression is severe and sequential, indicating pricing power remains weak.
The pet food expansion is a sensible long-term hedge, but it does not solve the near-term margin squeeze. Profitability recovery hinges on a sustained moderation in fish meal and soybean meal prices, which reports suggest may ease with fresh crop arrivals. Until then, earnings will remain under pressure.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.