Omara Ventures (OMARA) Q2 FY27 Profit Dives 36% as Costs Surge
The jeweller's September quarter revenue grew 28% year-on-year, but a sharp rise in expenses and interest costs pushed net profit down by over a third.
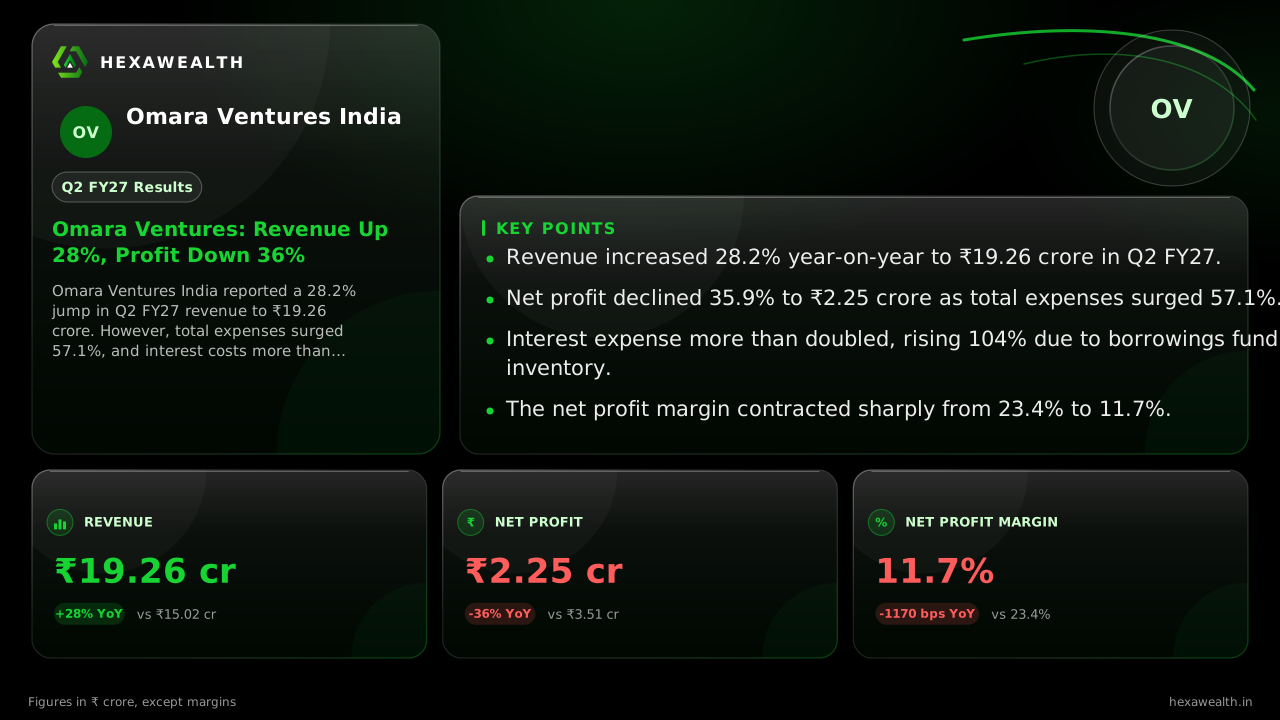
Omara Ventures India reported a 28.2% jump in Q2 FY27 revenue to ₹19.26 crore. However, total expenses surged 57.1%, and interest costs more than doubled, leading to a 35.9% decline in net profit to ₹2.25 crore.
For a jeweller that grew profit by riding an inventory build, the September quarter shows what happens when the funding for that stock comes due. Omara Ventures posted stronger sales but saw its bottom line squeezed by costs that grew twice as fast as revenue.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 15.02
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 19.26
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.51
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.25
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 15.02
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 19.26
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.51
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.25
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 23.4%
- Net Profit Margin, Q2 FY27 (Sep 2026): 11.7%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ2 FY26 (Sep 2025) |
|---|---|---|
| Revenue (₹ Cr) | 19.26 | 15.02 |
| Profit (₹ Cr) | 2.25 | 3.51 |
| Net Profit Margin | 11.7% | 23.4% |
Revenue rose 28.2% year-on-year, but profit fell 35.9%. The net profit margin halved, dropping nearly 12 percentage points from the same period last year.
The Cost of Carrying Inventory
A 57% surge in total expenses was the primary driver. Reports from Multibagg.ai and IPO analysis note the company's business model relies heavily on building inventory, which is funded by debt. This quarter, that reliance showed in a 104% year-on-year jump in interest cost to ₹1.06 crore.
The inventory strategy that boosted margins in FY26 is now pressuring profitability through higher finance charges. With a debt-to-equity ratio of 1.49, the cost of carrying that stock is a persistent headwind.
Live Chart
· OMARA
(BSE)
ISIN: INE1IA801011
A Crowded Festive Season
Industry reports suggest the broader jewellery sector saw a shift in demand this quarter. According to a New Indian Express report, the festive season was delayed, pushing major sales into Q3. While organised players like Titan and Kalyan Jewellers reported strong growth, they did so by selling higher-value, studded pieces.
For a single-boutique player like Omara, competing in this environment while managing high inventory costs is a challenge. The company is using IPO proceeds to renovate its Chandigarh store and fund marketing, as noted by Multibagg.ai, but near-term profitability remains under pressure.
Market Reaction and the Path Ahead
The stock fell 2.7% the day after the results, according to StockFin.ai, reflecting investor concern over the margin squeeze. With the company planning to deploy ₹10 crore from its IPO into working capital, the focus is on turning over its inventory faster.
The key test will be the festive Q3. Success depends on liquidating stock at healthy margins to offset the high cost of capital. Until then, profit growth is likely to remain subdued.
Key Points
- Revenue increased 28.2% year-on-year to ₹19.26 crore in Q2 FY27.
- Net profit declined 35.9% to ₹2.25 crore as total expenses surged 57.1%.
- Interest expense more than doubled, rising 104% due to borrowings funding inventory.
- The net profit margin contracted sharply from 23.4% to 11.7%.
Hexa Perspective
The quarter reveals the flip side of Omara's growth model. Its impressive FY26 profit leap was supported by an inventory build that is now financed on the balance sheet. The resulting interest cost is eroding margins faster than sales can grow. This squeeze is structural, tied to its debt-funded inventory strategy. Relief hinges on two factors: successful festive season sales to accelerate stock turnover and the effective deployment of IPO funds to retire expensive debt. The next quarter will show if top-line momentum can finally translate to the bottom line.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.