Ashnoor Textile Mills (ASHNOOR) Q1 FY27 Profit Jumps 113% as One-Off Gain Masks Core Weakness
A massive surge in other income drove a 113% YoY profit jump, but core terry towel revenue fell 14%, highlighting a reliance on non-operational gains.
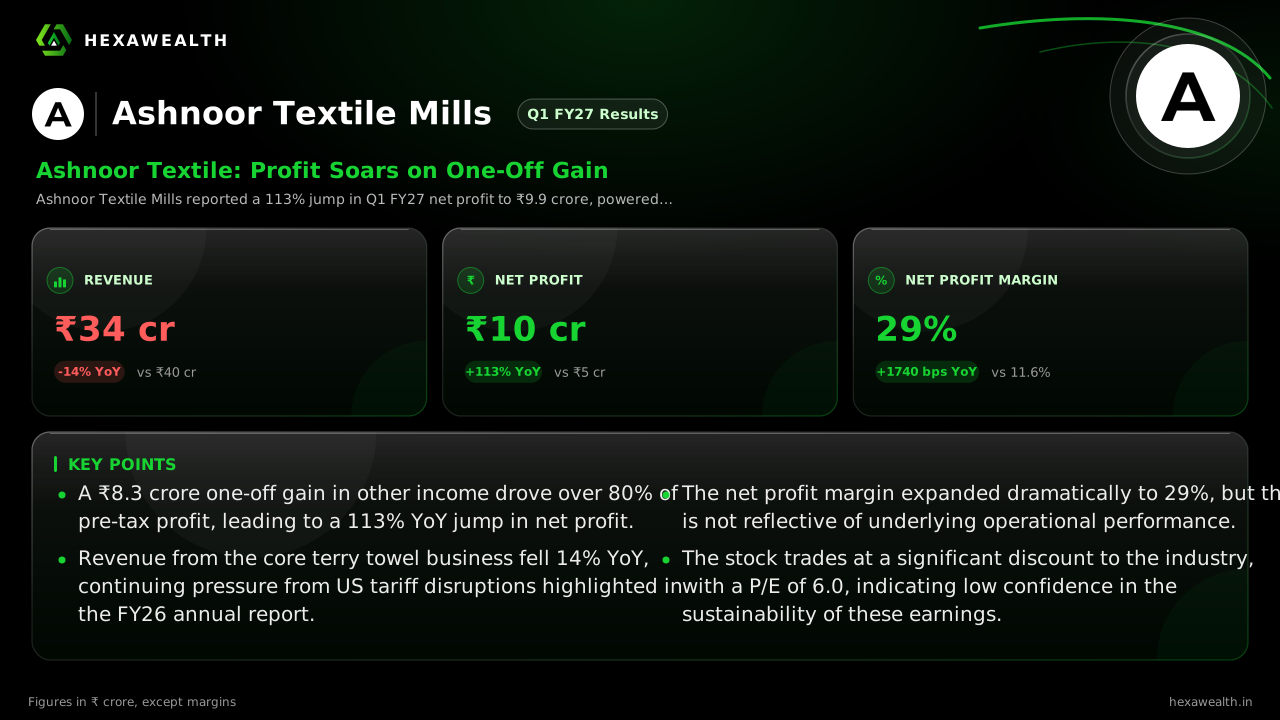
Ashnoor Textile Mills reported a 113% jump in Q1 FY27 net profit to ₹9.9 crore, powered by a ₹8.3 crore one-off gain. However, revenue from its core terry towel business fell 14% year-on-year, underscoring persistent operational challenges.
For Ashnoor Textile Mills, a specialist in terry towels for American hotels, the story this quarter splits in two. A headline profit surge masks a continued slide in the core business that pays the bills.
Net profit jumped 113% year-on-year to ₹9.9 crore, while revenue from operations fell 14% to ₹34.2 crore. The quarter-on-quarter picture is even starker, with profit up 574% on a 33% revenue rise. The net profit margin expanded to 29%, a dramatic leap from 5.7% last quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ1 FY27 | PreviousQ4 FY26 | Same quarter LYQ1 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 34.18YoY -14% | 25.77 | 39.84 |
| Profit (₹ Cr) | 9.90YoY +113% | 1.47 | 4.64 |
| Net Profit Margin | 29.0%YoY +150% | 5.7% | 11.6% |
The one-off that explains everything
The profit explosion was almost entirely due to a ₹8.3 crore surge in other income, a 272% jump from last year. According to a report by scanx.trade, this non-operating gain constituted 84% of the pre-tax profit. This more than compensated for the contraction in towel sales and a modest decline in total expenses.
The nature of this one-off income is not detailed in filings, but its scale transforms the bottom line. It follows a quarter where other income was negative ₹3.69 crore, creating a volatile base for comparison.
A core business under pressure
The 14% yearly drop in revenue points to deeper challenges. The company's annual report for FY26, cited by investywise.com, blamed "unprecedented tariff-related disruptions" affecting exports to the USA, its principal market. This suggests the core export engine is still sputtering.
Operational improvements were minor. Employee costs fell 7% yearly, and interest expense dropped 30%. Yet these savings are a footnote against the dominant narrative of a top-line decline cushioned by a financial windfall.
What comes after the windfall?
The outlook hinges on whether this other income is repeatable, which seems unlikely. The company's business remains concentrated on US hospitality distributors, a channel vulnerable to trade policy shifts. Its valuation, at a P/E of 6.0 against an industry average of 46.5, reflects deep skepticism about sustainable earnings.
Financially, the balance sheet is stable with a debt-to-equity ratio of 0.59. A report by scanx.trade noted the current ratio improved to 2.61, suggesting better short-term liquidity. This provides a buffer but not a growth catalyst.
Key Points
- A ₹8.3 crore one-off gain in other income drove over 80% of pre-tax profit, leading to a 113% YoY jump in net profit.
- Revenue from the core terry towel business fell 14% YoY, continuing pressure from US tariff disruptions highlighted in the FY26 annual report.
- The net profit margin expanded dramatically to 29%, but this is not reflective of underlying operational performance.
- The stock trades at a significant discount to the industry, with a P/E of 6.0, indicating low confidence in the sustainability of these earnings.
Hexa Perspective
The quarter presents a clear dichotomy. The profit surge is a financial event, not an operating turnaround. Investors must separate the transient boost from the persistent weakness in towel exports.
The core issue remains demand recovery in its key US market. Until that shows a sustained rebound, the company's earnings will lack a reliable foundation. The current valuation discount acknowledges this reality, pricing in the operational risk rather than the quarterly profit print.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.