Ashapura Minechem (ASHAPURMIN) Q2 FY27 Profit Dives 34% as High Costs Bite into Bauxite Gains
The miner's September quarter profit fell sharply year-on-year despite higher revenue, as elevated freight and fuel costs squeezed margins from its key Guinea operations.
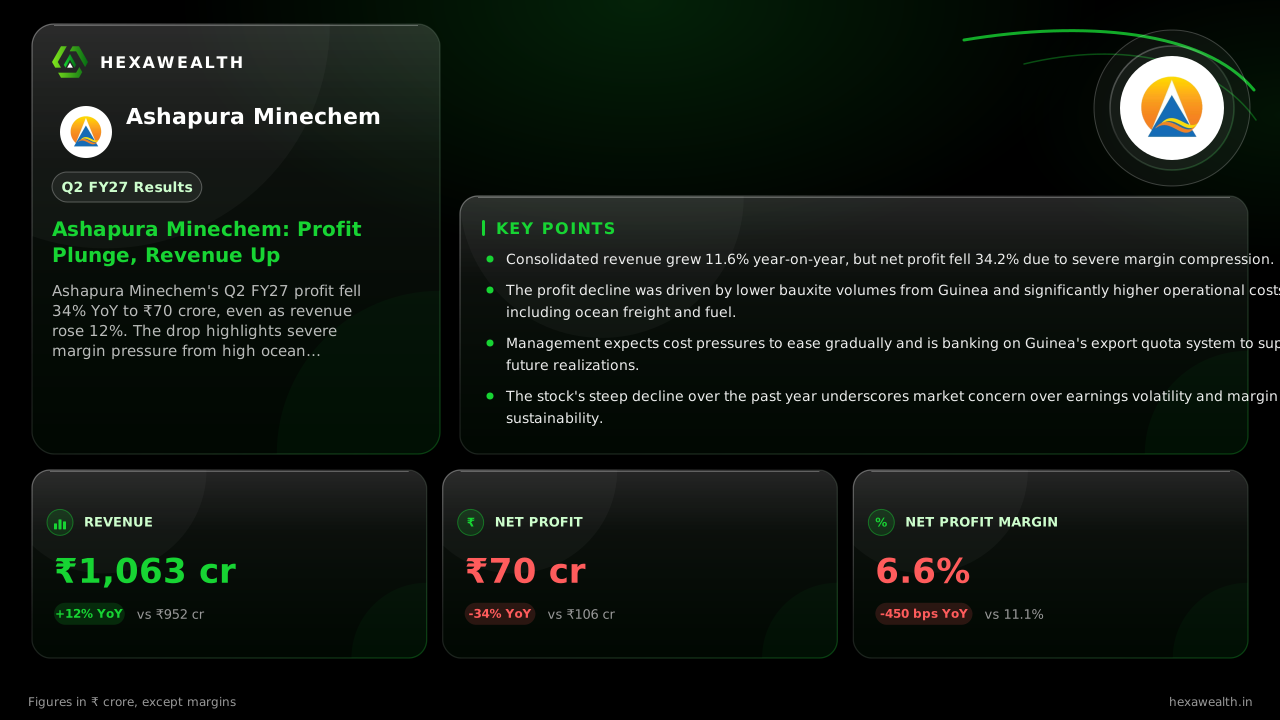
Ashapura Minechem's Q2 FY27 profit fell 34% YoY to ₹70 crore, even as revenue rose 12%. The drop highlights severe margin pressure from high ocean freight and fuel costs impacting its Guinea bauxite exports.
For Ashapura Minechem, the story this quarter is one of top-line growth that never reached the bottom line. Revenue from its Guinea bauxite operations climbed, but a punishing combination of seasonal disruption and soaring costs left profits sharply lower.
The numbers show the split. Consolidated revenue rose 11.6% year-on-year to ₹1,063 crore. Yet net profit fell 34.2% to ₹70 crore, dragging the net profit margin down by 450 basis points to 6.6%. Sequentially, both revenue and profit fell by over a third.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,063.4YoY +12% | 1,616.1 | 952.5 |
| Profit (₹ Cr) | 69.71YoY -34% | 108.31 | 105.98 |
| Net Profit Margin (%) | 6.6YoY -41% | 6.7 | 11.1 |
Why the Gains Didn't Stick
The profit drop stems from its core Guinea bauxite business. The company, per its filing cited by Blacklitt, said lower dispatches were due to seasonal monsoon conditions, higher ocean freight, and increased fuel prices. Export volumes fell to 1.21 million tonnes from 2.34 million tonnes in the prior quarter.
Costs rose faster than sales. Employee expenses jumped 26% year-on-year, outpacing revenue growth and pressuring margins, notes MarketsMojo. While operating margin improved slightly from the June quarter, it remained below the sector median. Interest costs also crept up nearly 9% sequentially.
A Waiting Game on Costs and Quotas
The outlook hinges on two external factors. Management expects cost conditions to stabilise gradually, according to StockFin.ai. The bigger potential catalyst is Guinea's planned bauxite export quota system, which could improve realizations by curbing supply.
Until then, profitability remains under a cloud. The company has revised its FY27 bauxite volume target to 9-11 million tonnes, as reported by SAHI, while holding to a 15 million tonne goal for FY28. The stock, trading 55% below its 52-week high per MarketsMojo, reflects the deep skepticism.
Key Points
- Consolidated revenue grew 11.6% year-on-year, but net profit fell 34.2% due to severe margin compression.
- The profit decline was driven by lower bauxite volumes from Guinea and significantly higher operational costs, including ocean freight and fuel.
- Management expects cost pressures to ease gradually and is banking on Guinea's export quota system to support future realizations.
- The stock's steep decline over the past year underscores market concern over earnings volatility and margin sustainability.
Hexa Perspective
This quarter underscores Ashapura Minechem's vulnerability to external cost shocks despite its strategic resource base. The 450-basis-point YoY margin contraction is severe, and the path to recovery is not in its hands alone. Investors are weighing the long-term volume ramp-up against near-term profitability that remains hostage to freight rates and regulatory timelines. The stock's valuation at a premium to the industry, despite these pressures, suggests the market is still pricing in the FY28 volume target, but patience is wearing thin.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.