Ashiana Housing (ASHIANA) Q2 FY27 Profit Jumps 85% as Deferred Revenue Flows In
The real estate developer's September quarter revenue surged 248% year-on-year, but profitability per rupee of sales fell sharply as costs rose faster.
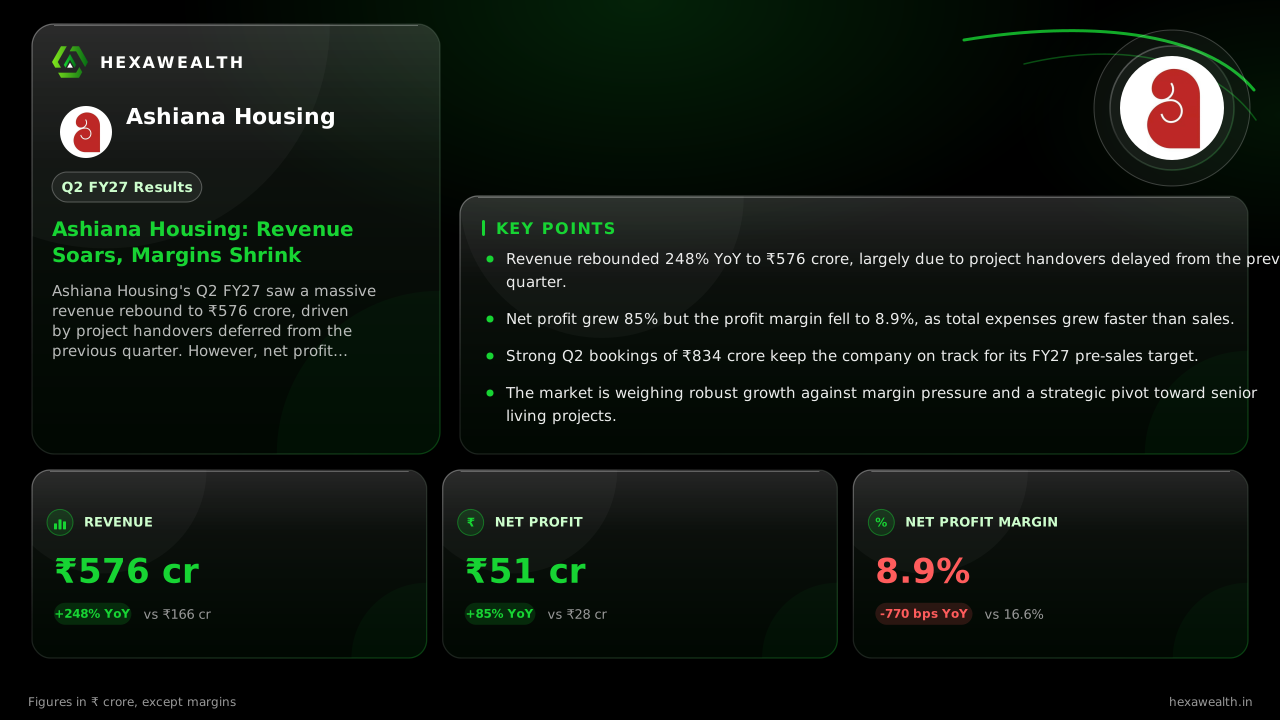
Ashiana Housing's Q2 FY27 saw a massive revenue rebound to ₹576 crore, driven by project handovers deferred from the previous quarter. However, net profit margin compressed to 8.9% as expenses grew even faster.
For Ashiana Housing, the September quarter was always about catching up. After a quiet June period where revenue recognition was delayed, the company’s financials snapped back with force, revealing both the strength of its pipeline and the pressure on its profits.
Revenue leaped to ₹575.7 crore, up 248% from a year ago and a staggering 436% from the prior quarter. Net profit followed, rising 85% year-on-year to ₹51 crore. Yet the net profit margin fell to 8.9%, down sharply from 16.6% a year earlier. This divergence between top-line growth and bottom-line efficiency defines the quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 575.68 | 107.44 |
| Profit (₹ Cr) | 51.03 | 13.11 |
| Net Profit Margin (%) | 8.9 | 12.2 |
Why the profit didn't keep pace
The revenue surge came from handovers deferred from Q1. According to an Investing.com transcript, about ₹532 crore of revenue from projects like Ambience Stage 3 and Ashiana Amara Phase 1 flowed into Q2 after occupancy certificates arrived in mid-July. While this boosted sales, it also brought a heavier cost load. Total expenses soared 271% year-on-year, outpacing revenue growth and compressing margins. A scanx.trade report noted the consolidated EBITDA margin contracted by approximately 717 basis points to 10.41%.
A strong order book meets a strategic shift
Future revenue is underpinned by robust sales. The company reported Q2 bookings worth ₹834.4 crore across 9.46 lakh square feet, as per a multibagg.ai update. This took first-half FY27 bookings to ₹1,192 crore, well on track toward its full-year pre-sales target of ₹2,200 crore. Management, cited in a Yahoo Finance transcript, remains focused on senior living, a segment they see as less cyclical with limited organized supply.
The market's cautious read
The stock reaction was muted relative to the headline growth, reflecting the margin concern. An independent research note from early November, cited by Synergy Infracon, maintained a 'Hold' rating, calling valuation expensive but justifiable. Analysts at Unives.in highlighted volatile quarterly profit and a return on equity below 15% as key risks. Offsetting this, CARE Edge upgraded the company's credit rating to A+ in late October, acknowledging a stronger balance sheet.
Key Points
- Revenue rebounded 248% YoY to ₹576 crore, largely due to project handovers delayed from the previous quarter.
- Net profit grew 85% but the profit margin fell to 8.9%, as total expenses grew faster than sales.
- Strong Q2 bookings of ₹834 crore keep the company on track for its FY27 pre-sales target.
- The market is weighing robust growth against margin pressure and a strategic pivot toward senior living projects.
Hexa Perspective
This quarter confirms Ashiana Housing’s execution capability and strong demand for its projects, particularly in the senior living niche it dominates. The margin compression, however, is a clear headwind. It suggests the current phase of deliveries carries a different, likely higher, cost structure than past quarters. The path forward hinges on whether operating leverage from its growing senior living portfolio can restore profitability as revenue scales, or if elevated costs are a new normal for this cycle. Investors are left balancing a strong order book and credit upgrade against thinner margins.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.