Anand Rayons (ARL) Q2 FY27 Profit More Than Doubles on Revenue Rebound
The yarn trader's September quarter profit soared over 100% year-on-year, but a margin squeeze highlights the volatile cost environment for textiles.
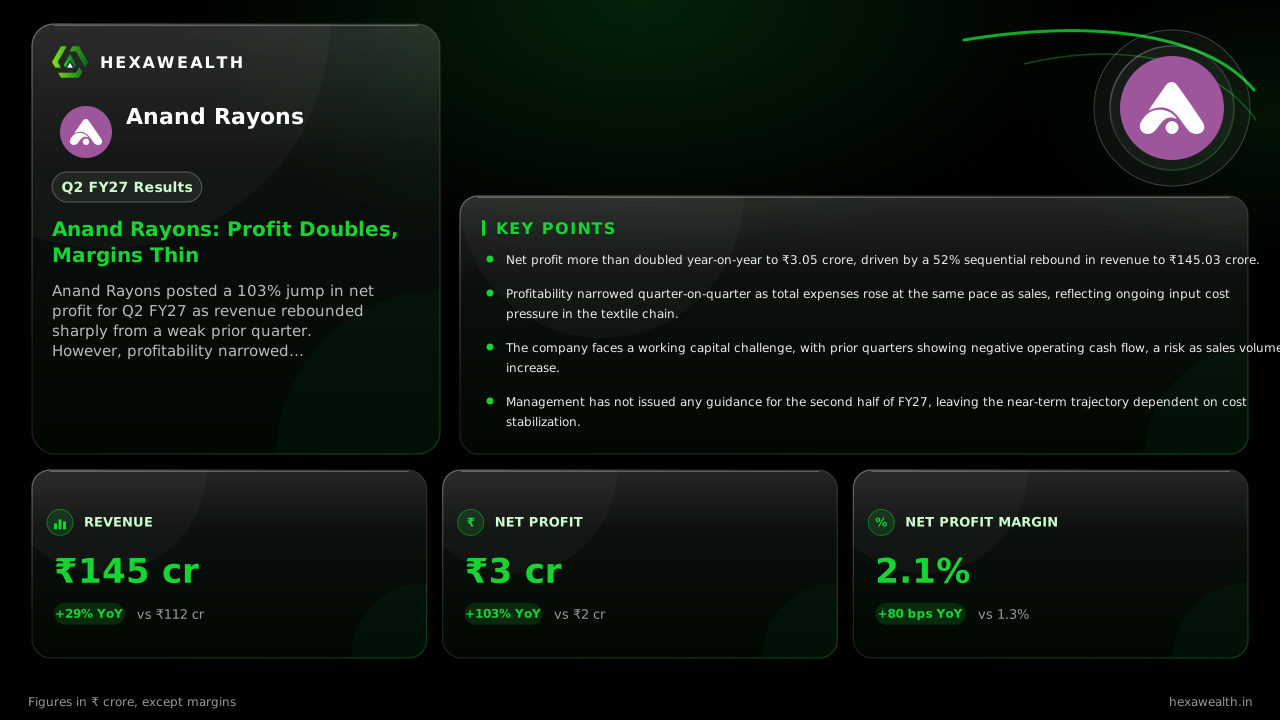
Anand Rayons posted a 103% jump in net profit for Q2 FY27 as revenue rebounded sharply from a weak prior quarter. However, profitability narrowed sequentially as expenses kept pace with sales growth.
For a yarn trader like Anand Rayons, the quarter is a story of raw material prices and working capital. After a sharp dip in June, the September quarter saw a powerful revenue rebound, lifting profit more than 100% from a year ago. Yet the margin story tells a different tale, one of costs rising just as fast as sales.
Revenue for the quarter ended September 2026 came in at ₹145.03 crore, a 29% jump from the same period last year and a 52% surge from the prior quarter. Net profit more than doubled year-on-year to ₹3.05 crore. The company's trailing-twelve-month net profit margin stands at 2.6%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 145.03 | 95.58 |
| Net Profit (₹ Cr) | 3.05 | 2.32 |
| Net Profit Margin (%) | 2.1 | 2.4 |
Why the rebound didn't lift margins
The profit surge was driven by the top line, not operating leverage. Total expenses rose in lockstep with revenue, up 52% quarter-on-quarter. This kept the net profit margin at 2.1%, a 30 basis-point drop from the June quarter.
Industry reports point to a volatile cost environment. A report from Fashionating World notes that domestic polyester melt prices rose through September, squeezing downstream fabric manufacturers. While yarn prices were reported as soft due to weak demand, the underlying feedstock cost pressure from crude oil remains.
The cash conversion challenge
A key concern is cash generation. Analysis by StockFin.ai notes that operating cash flow turned negative at ₹-11 crore in the March 2026 quarter, suggesting challenges in converting sales to cash. With the recent revenue surge likely tying up more capital in working capital, this remains a critical metric to watch for sustainability.
Management has not provided any forward guidance, according to the same StockFin.ai report. The board meeting on November 4 was focused solely on result approval, with no commentary on strategy or projections for the coming half-year.
Key Points
- Net profit more than doubled year-on-year to ₹3.05 crore, driven by a 52% sequential rebound in revenue to ₹145.03 crore.
- Profitability narrowed quarter-on-quarter as total expenses rose at the same pace as sales, reflecting ongoing input cost pressure in the textile chain.
- The company faces a working capital challenge, with prior quarters showing negative operating cash flow, a risk as sales volumes increase.
- Management has not issued any guidance for the second half of FY27, leaving the near-term trajectory dependent on cost stabilization.
Hexa Perspective
This quarter is a recovery from a low base, not a breakout. The year-on-year profit jump looks impressive but is measured against a very weak Q2 FY26. The more telling trend is the sequential margin compression, which aligns with broader industry reports of squeezed conversion margins for polyester products.
The path ahead hinges on two volatile factors: crude oil-driven input costs and the company's ability to manage receivables. Without pricing power in a saturated market, Anand Rayons remains a volume-driven trader exposed to every swing in the commodity cycle. The lack of institutional interest and management guidance adds to the uncertainty, making this a story of operational execution over strategic vision.
Also read
IRCON: Revenue Up, Profit Down
Market Pulse, 5 Nov 2026: Earnings Upgrades Meet Unwinding Leverage
Gold ETF inflows choked as AMCs suspend fund-of-funds route
Market News Today, 5 Nov 2026: Corporate bond rush hits ₹17,000 crore as yields ease, but NBFCs see funding costs rise
Balrampur Chini: Profit Doubles on Sugar Spike
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.