Alkosign (ALKOSIGN) Q4 FY26's Q4 Loss Widens to ₹5.15 Crore After Luggage Division Closure
The stationery maker's annual revenue halved after shutting its loss-making luggage unit, leading to a deep quarterly net loss as restructuring costs hit.
Alkosign reported a net loss of ₹5.15 crore in Q4 FY26 as revenue fell 26% year-on-year. The company's full-year revenue halved after closing its luggage division, which had contributed nearly 43% of turnover.
For Alkosign, the March quarter was about the aftermath of a strategic retreat. The company had just shut its polycarbonate luggage unit in February, a division that once drove nearly half its sales but had become a persistent drag. The result is a financial statement split between a shrunken core business and the final costs of exit.
The numbers show a company in transition. Revenue for Q4 FY26 fell to ₹11.08 crore, down 26% from the same quarter last year and 58% from the September quarter. The net loss deepened to ₹5.15 crore, swinging from a profit of ₹0.46 crore a year ago. For the full year, revenue nearly halved to ₹26.7 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 27.90
- Revenue (₹ Cr), Q3 FY25: 11.19
- Revenue (₹ Cr), Q4 FY25: 14.95
- Revenue (₹ Cr), Q2 FY26: 26.34
- Revenue (₹ Cr), Q4 FY26: 11.08
- Profit (₹ Cr), Q2 FY25: 3.31
- Profit (₹ Cr), Q3 FY25: 0.94
- Profit (₹ Cr), Q4 FY25: 0.46
- Profit (₹ Cr), Q2 FY26: 0.39
- Profit (₹ Cr), Q4 FY26: -5.15
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 27.90
- Revenue (₹ Cr), Q3 FY25: 11.19
- Revenue (₹ Cr), Q4 FY25: 14.95
- Revenue (₹ Cr), Q2 FY26: 26.34
- Revenue (₹ Cr), Q4 FY26: 11.08
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 3.31
- Profit (₹ Cr), Q3 FY25: 0.94
- Profit (₹ Cr), Q4 FY25: 0.46
- Profit (₹ Cr), Q2 FY26: 0.39
- Profit (₹ Cr), Q4 FY26: -5.15
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 11.08YoY -26% | 14.95 |
| Profit (₹ Cr) | -5.15YoY -1220% | 0.46 |
| Net Margin (%) | -46.5YoY -1600% | 3.1 |
The Cost of Exiting Luggage
The sharp margin collapse to -46.5% was not from operations. According to data from LAX - Stock Market Analysis, the quarter included a ₹5 crore exceptional item linked to the luggage division closure. This one-off charge, reflected in a negative other income of ₹4.47 crore, turned what was a modestly profitable core operation into a deep loss.
MarketPing reports the discontinued luggage unit racked up a loss of ₹6.02 crore in FY26. Its closure on February 2 removed a major revenue stream but also a consistent loss-maker, as competition from cheaper polypropylene bags and in-house OEM production made the business unviable.
A Slimmer, Focused Future
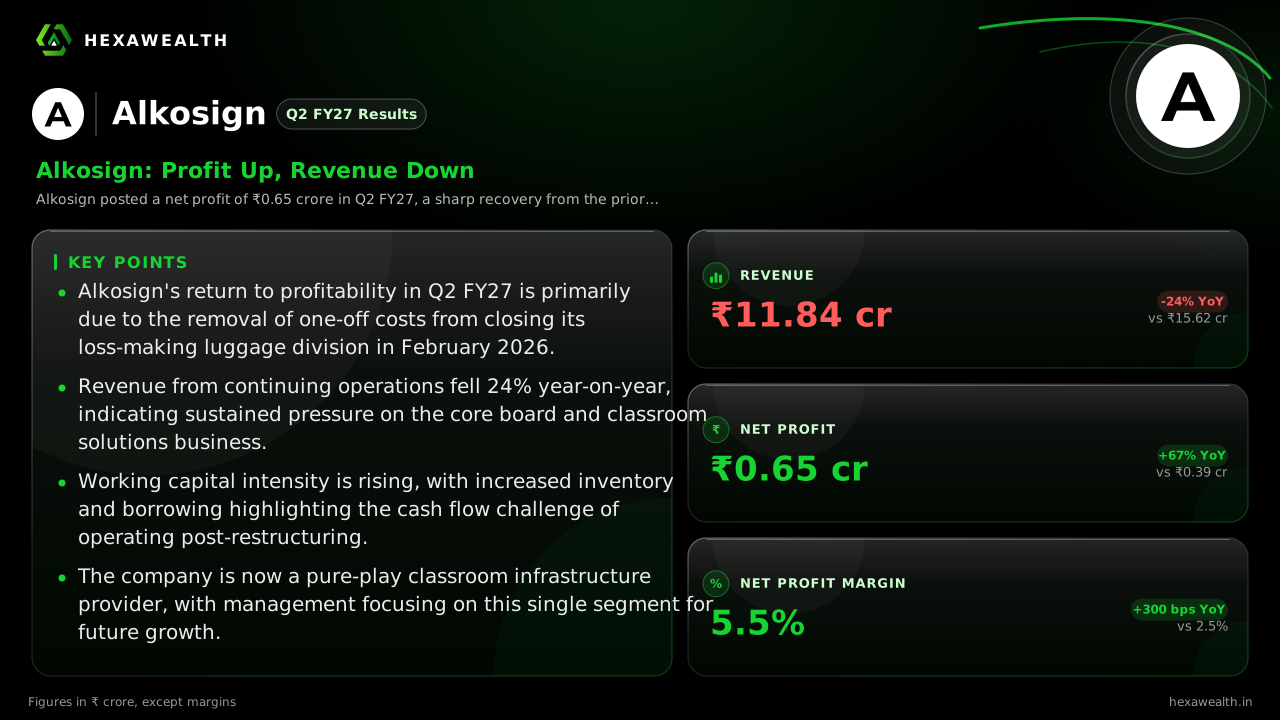
The company is now a single-segment manufacturer of writing boards, display systems, and classroom furniture. Management has signaled a refocus on this core, with the board reappointing key executives. A glimpse of the post-exit reality came with H1 FY27 results, where Alfafinder reported a net profit of ₹0.6 crore on revenue of ₹11.8 crore.
Live Chart
· ALKOSIGN
(BSE)
ISIN: INE0KA601012
Working capital remains a watchpoint. Data from Newboard.in shows debtor days stretched to 176 in FY26, tying up cash. However, the balance sheet is not under acute stress, with a debt-to-equity ratio of 0.47 and positive operating cash flow of ₹1.63 crore for the year.
Key Points
- Alkosign's Q4 FY26 net loss of ₹5.15 crore was driven by exceptional costs of around ₹5 crore from shutting its luggage division.
- Full-year revenue halved to ₹26.7 crore after the exit, which removed a unit contributing 43% of prior-year turnover but was deeply loss-making.
- The company is now a pure-play classroom solutions provider, with H1 FY27 results showing a return to profitability at the operating level.
- Customer payments are slowing, with debtor days extending to 176, pressuring working capital despite a manageable debt load.
Hexa Perspective
The quarter closes a painful, necessary chapter. Alkosign's future hinges entirely on its ability to grow its core stationery and classroom furniture business, which must now compensate for the lost luggage revenue. The initial H1 FY27 profit is a positive step, but it comes from a much smaller base.
The valuation, at a 57% discount to the industry PE, reflects the uncertainty of this rebuild. Success depends on gaining market share in a competitive, price-sensitive industry where input costs like paper are volatile. The restructuring is complete, but the turnaround is just beginning.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.