Zinema (ZINEMA) Q4 FY26's FY26 Revenue Soars, but Profit Margins Collapse
Zinema Media & Entertainment's revenue surged over 900% YoY in Q4, but a sharp rise in costs and interest caused its net profit margin to fall from 73% to 9%.
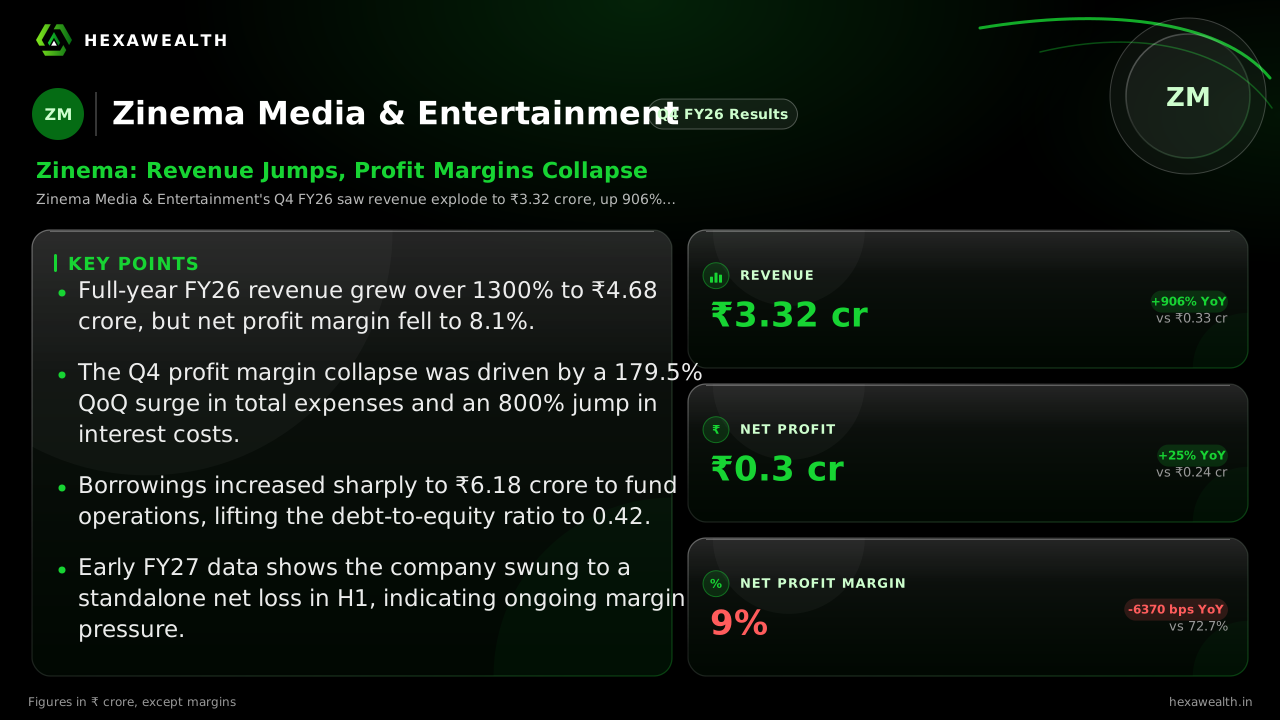
Zinema Media & Entertainment's Q4 FY26 saw revenue explode to ₹3.32 crore, up 906% year-on-year. However, profitability was severely squeezed, with net profit margin collapsing from 72.7% to just 9% due to surging expenses and interest costs.
For a company newly venturing into media, Zinema's FY26 was a story of explosive top-line growth colliding with the hard costs of building a business. The headline was a revenue surge, but the real story was a dramatic collapse in profitability as the company scaled.
The numbers show the tension clearly. Revenue for the March quarter hit ₹3.32 crore, a staggering 906% jump from the year-ago period. For the full year, revenue soared to ₹4.68 crore from just ₹0.33 crore in FY25. Yet, net profit for the quarter grew only 25% YoY to ₹0.30 crore, and the net profit margin plummeted from 72.7% to 9.0%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.00
- Revenue (₹ Cr), Q2 FY25: 0.00
- Revenue (₹ Cr), Q4 FY25: 0.33
- Revenue (₹ Cr), Q2 FY26: 1.36
- Revenue (₹ Cr), Q4 FY26: 3.32
- Profit (₹ Cr), Q4 FY24: 0.28
- Profit (₹ Cr), Q2 FY25: 0.05
- Profit (₹ Cr), Q4 FY25: 0.24
- Profit (₹ Cr), Q2 FY26: 0.21
- Profit (₹ Cr), Q4 FY26: 0.30
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.00
- Revenue (₹ Cr), Q2 FY25: 0.00
- Revenue (₹ Cr), Q4 FY25: 0.33
- Revenue (₹ Cr), Q2 FY26: 1.36
- Revenue (₹ Cr), Q4 FY26: 3.32
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 0.28
- Profit (₹ Cr), Q2 FY25: 0.05
- Profit (₹ Cr), Q4 FY25: 0.24
- Profit (₹ Cr), Q2 FY26: 0.21
- Profit (₹ Cr), Q4 FY26: 0.30
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY24: -
- Net Profit Margin (%), Q2 FY25: -
- Net Profit Margin (%), Q4 FY25: 72.7
- Net Profit Margin (%), Q2 FY26: 15.4
- Net Profit Margin (%), Q4 FY26: 9.0
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 3.32YoY +906% | 0.33 |
| Profit (₹ Cr) | 0.30YoY +25% | 0.24 |
| Net Profit Margin (%) | 9.0YoY -88% | 72.7 |
Why the profit margin collapsed
A breakdown from the newboard report shows the pressure points. Operating profit margin fell sharply from 42.9% in H2 FY25 to just 4.4% in H2 FY26. Total expenses surged 179.5% quarter-on-quarter, far outpacing revenue growth. A major new cost was interest, which jumped 800% QoQ to ₹0.18 crore.
This interest spike reflects a significant increase in borrowings to fund growth. According to newboard, total borrowings stood at ₹6.18 crore at the end of FY26, up from just ₹0.19 crore a year earlier. The debt-to-equity ratio is now 0.42.
The path ahead looks challenging
Early signs for FY27 suggest the profitability squeeze is intensifying. The company reported a standalone net loss of ₹1.05 crore for the half-year ended September 2026, according to a stockfin.ai report. While revenue continued to grow, rising costs led to a loss compared to a profit in the same period last year.
Live Chart
· ZINEMA
(BSE)
ISIN: INE641Q01019
The media environment itself adds pressure. A Storyboard18 analysis notes that while digital ad spending is growing, the market is fragmented and pricing is competitive. For a small player building scale, achieving pricing power will be a long-term challenge.
Key Points
- Full-year FY26 revenue grew over 1300% to ₹4.68 crore, but net profit margin fell to 8.1%.
- The Q4 profit margin collapse was driven by a 179.5% QoQ surge in total expenses and an 800% jump in interest costs.
- Borrowings increased sharply to ₹6.18 crore to fund operations, lifting the debt-to-equity ratio to 0.42.
- Early FY27 data shows the company swung to a standalone net loss in H1, indicating ongoing margin pressure.
Hexa Perspective
Zinema's year demonstrates the classic growth trap: revenue can be bought, but profitability must be earned. The company paid for its scale with heavy borrowing and operating costs, erasing the super-normal margins of its smaller past. The question is whether this is a temporary investment phase or a structural shift to lower returns.
The surge in debt and the reported H1 FY27 loss suggest the investment phase is ongoing. For the growth to justify the valuation—a P/E of 32, above the industry average of 26.5—Zinema must now demonstrate it can convert its new revenue base into sustainable, leveraged earnings. The next few quarters will be about cost control and proving the business model works at this new scale.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.