Binayak Tex Processors (ZBINTXPP) Q2 FY27 Profit Surges 179% Despite Lower Revenue
A sharp recovery in margins drove a massive profit jump, but revenue fell 5.7% YoY and debt rose to fund operations after a fire.
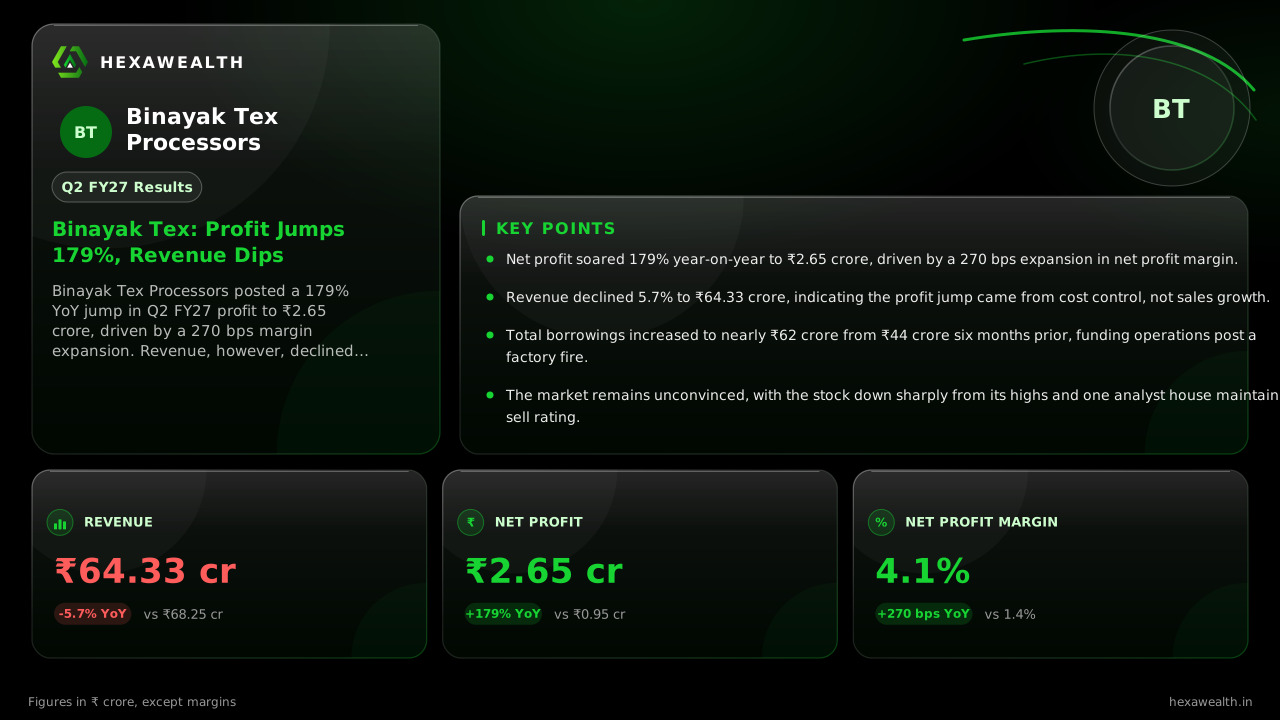
Binayak Tex Processors posted a 179% YoY jump in Q2 FY27 profit to ₹2.65 crore, driven by a 270 bps margin expansion. Revenue, however, declined 5.7% to ₹64.33 crore, and total debt increased to nearly ₹62 crore.
For a textile processor like Binayak Tex, the story is usually told in sales volumes and fabric prices. This quarter rewrote it in margins. The company posted a net profit of ₹2.65 crore for the September 2026 quarter, a massive 179% leap from a year ago, even as its revenue shrank 5.7%.
The numbers reveal a sharp operational pivot. Revenue of ₹64.33 crore was down from ₹68.25 crore in Q2 FY26 but marked a 20% sequential recovery from a weak June quarter. The real story is the net profit margin, which expanded 270 basis points year-on-year to 4.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 68.25
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 72.19
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 62.61
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 53.68
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 64.33
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.95
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 1.83
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -0.95
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.38
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.65
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 68.25
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 72.19
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 62.61
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 53.68
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 64.33
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.95
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 1.83
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -0.95
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.38
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 2.65
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 1.4%
- Net Profit Margin, Q3 FY26 (Dec 2025): 2.5%
- Net Profit Margin, Q4 FY26 (Mar 2026): -1.5%
- Net Profit Margin, Q1 FY27 (Jun 2026): 0.7%
- Net Profit Margin, Q2 FY27 (Sep 2026): 4.1%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 64.33 | 53.68 |
| Profit (₹ Cr) | 2.65 | 0.38 |
| Net Profit Margin | 4.1% | 0.7% |
Efficiency, Not Growth, Drove the Win
The profit surge was powered by operational efficiency, not a one-off gain. According to MarketsMojo, the operating margin hit 8.49%, its highest in at least seven quarters. This came from better cost management, with total expenses down 8.5% year-on-year and interest costs falling 17%.
The quarter was not without disruption. The company disclosed a fire on August 27, 2026, that damaged plant and inventory. It has filed an ₹8.97 crore insurance claim for the inventory loss, which it recognises as a receivable, as reported by mCapital.
The Debt-Fueled Balance Sheet
Funding operations after the fire and building inventory lifted borrowings. Total debt stood at approximately ₹61.9 crore at the end of September, up from ₹44 crore at the end of March 2026, according to the same mCapital analysis. This rise in leverage tempers the earnings upside.
Live Chart
· ZBINTXPP
(BSE)
ISIN: INE626H01019
Markets have viewed the results with deep scepticism. The stock, despite a 4.3% gain on the results date, remains down 45% from its 52-week high. MarketsMojo maintains a 'Strong Sell' rating, citing weak long-term return metrics and quarterly volatility.
Key Points
- Net profit soared 179% year-on-year to ₹2.65 crore, driven by a 270 bps expansion in net profit margin.
- Revenue declined 5.7% to ₹64.33 crore, indicating the profit jump came from cost control, not sales growth.
- Total borrowings increased to nearly ₹62 crore from ₹44 crore six months prior, funding operations post a factory fire.
- The market remains unconvinced, with the stock down sharply from its highs and one analyst house maintaining a sell rating.
Hexa Perspective
The quarter demonstrates Binayak Tex's ability to sharply improve profitability from a low base through cost discipline. Yet, the sustainability of these margins is the critical question, given the company's history of quarterly volatility and a top line that is still contracting.
The rising debt load to fund working capital introduces financial risk. For the recovery narrative to hold, the company must show it can grow revenue while maintaining these new efficiency levels, a test the next quarter will immediately pose.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.