WISEC Global Q2 FY27's Revenue Plunges 95% as Grocery Business Stalls
WISEC Global's quarterly revenue fell to ₹0.22 crore, a 95% sequential drop, as its brief grocery segment surge proved fleeting and expenses remained elevated.
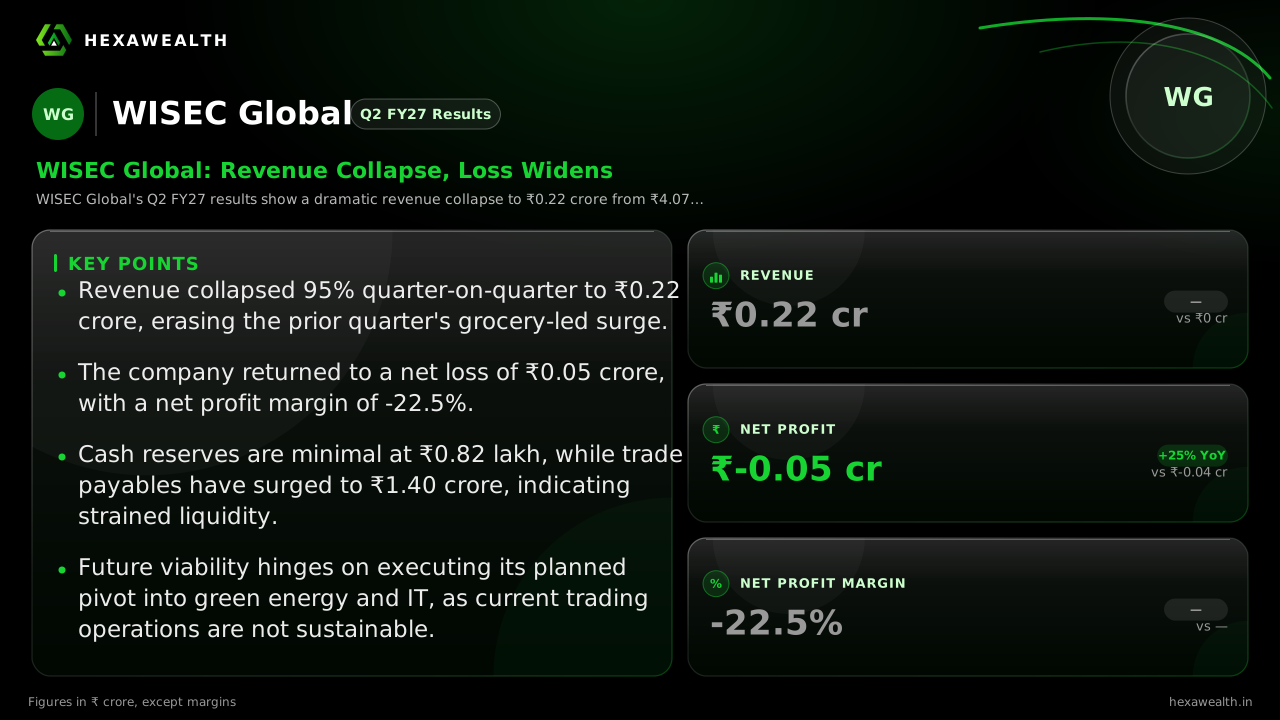
WISEC Global's Q2 FY27 results show a dramatic revenue collapse to ₹0.22 crore from ₹4.07 crore last quarter. The company slipped back into a loss, highlighting the unsustainability of its recent grocery segment performance.
For WISEC Global, a company in the midst of a strategic realignment, the September quarter was a stark return to reality. After a surprising profit in June driven by a grocery segment contract, revenue collapsed by 95% sequentially, pushing the company back into the red.
The numbers tell a story of extreme volatility. Revenue plummeted to ₹0.22 crore from ₹4.07 crore in the prior quarter. This resulted in a net loss of ₹0.05 crore, a sharp reversal from the ₹0.11 crore profit posted in Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.00
- Revenue (₹ Cr), Q3 FY26: 0.01
- Revenue (₹ Cr), Q4 FY26: 0.02
- Revenue (₹ Cr), Q1 FY27: 4.07
- Revenue (₹ Cr), Q2 FY27: 0.22
- Profit (₹ Cr), Q2 FY26: -0.04
- Profit (₹ Cr), Q3 FY26: -0.09
- Profit (₹ Cr), Q4 FY26: -0.04
- Profit (₹ Cr), Q1 FY27: 0.11
- Profit (₹ Cr), Q2 FY27: -0.05
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.00
- Revenue (₹ Cr), Q3 FY26: 0.01
- Revenue (₹ Cr), Q4 FY26: 0.02
- Revenue (₹ Cr), Q1 FY27: 4.07
- Revenue (₹ Cr), Q2 FY27: 0.22
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: -0.04
- Profit (₹ Cr), Q3 FY26: -0.09
- Profit (₹ Cr), Q4 FY26: -0.04
- Profit (₹ Cr), Q1 FY27: 0.11
- Profit (₹ Cr), Q2 FY27: -0.05
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: —
- Net Profit Margin (%), Q3 FY26: —
- Net Profit Margin (%), Q4 FY26: —
- Net Profit Margin (%), Q1 FY27: 2.7
- Net Profit Margin (%), Q2 FY27: -22.5
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 0.22 | 4.07 | 0.00 |
| Profit (₹ Cr) | -0.05YoY -25% | 0.11 | -0.04 |
| Net Profit Margin (%) | -22.5 | 2.7 | — |
Why the grocery boom was a flash in the pan
The prior quarter's profit was driven almost entirely by its Groceries segment, which contributed ₹4.05 crore of the total ₹4.07 crore revenue, according to a report by Scanx.trade. This appears to have been a one-off contract, not a sustainable business line. The subsequent quarter's near-zero revenue confirms the segment lacks recurring momentum.
A balance sheet under strain
With core operations generating minimal income, the company's financial health is under pressure. A report from Multibagg.ai notes cash reserves dwindled to ₹0.82 lakh by September end. More strikingly, trade payables ballooned to ₹1.40 crore, suggesting the company is funding itself by delaying payments to creditors.
The long road of strategic realignment
Management's stated plan is to pivot toward green energy and IT services, as outlined in its FY26 annual report cited by StockFin. However, the current quarter shows no progress from these nascent plans. The standalone entity continues to rely on sporadic trading income while its subsidiary, Garg Acrylics Ltd, drives consolidated profits.
Live Chart
· WISEC
(BSE)
ISIN: INE638C01015
Key Points
- Revenue collapsed 95% quarter-on-quarter to ₹0.22 crore, erasing the prior quarter's grocery-led surge.
- The company returned to a net loss of ₹0.05 crore, with a net profit margin of -22.5%.
- Cash reserves are minimal at ₹0.82 lakh, while trade payables have surged to ₹1.40 crore, indicating strained liquidity.
- Future viability hinges on executing its planned pivot into green energy and IT, as current trading operations are not sustainable.
Hexa Perspective
This quarter underscores the fundamental challenge for WISEC Global: its standalone business lacks a durable revenue model. The grocery segment's brief success was an anomaly, not a foundation. The company's path forward depends entirely on its ability to generate real traction in its new focus areas—green energy and IT services. Until tangible revenue emerges from these initiatives, the financials will likely continue to reflect the volatility and weakness seen in Q2. Investors are left weighing the promise of a strategic pivot against the stark reality of a balance sheet funded by rising payables.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.