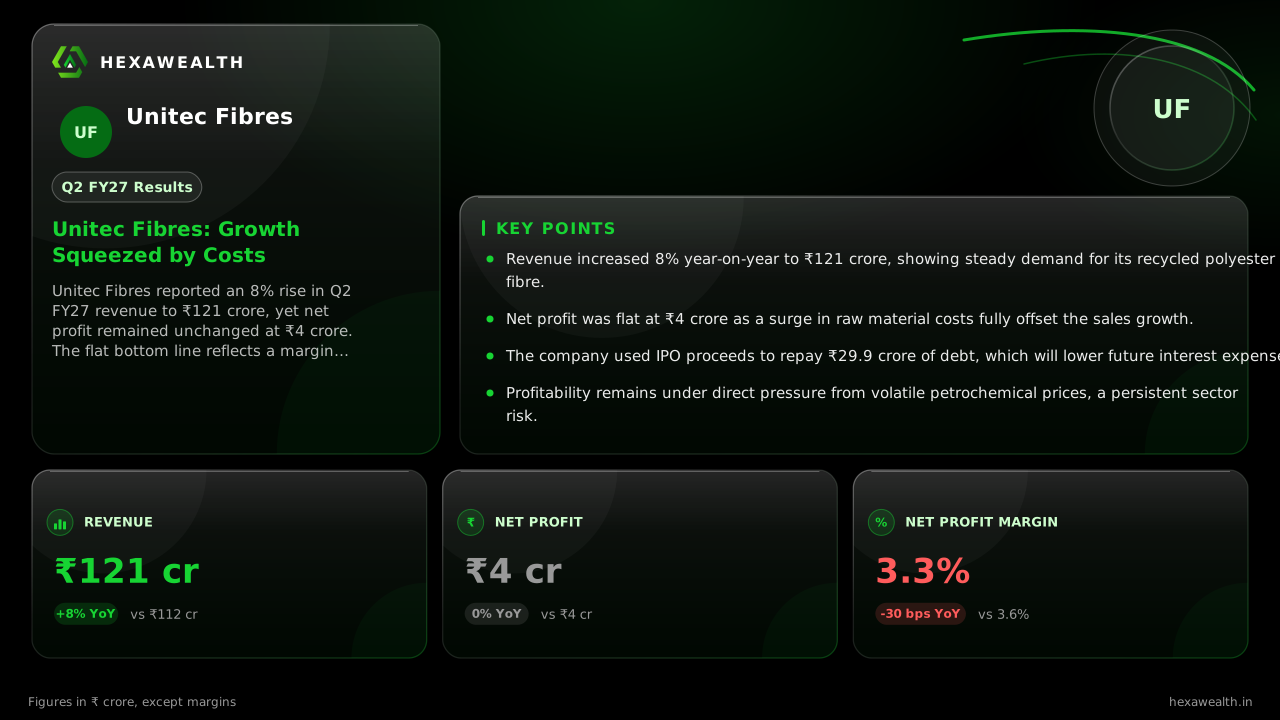
Unitec Fibres (UNITEC) Q2 FY27 Revenue Rises 8% But Profit Stalls on Cost Pressure
The recycled fibre maker posted higher sales, but rising raw material costs kept net profit flat and squeezed margins in the September quarter.
Unitec Fibres reported an 8% rise in Q2 FY27 revenue to ₹121 crore, yet net profit remained unchanged at ₹4 crore. The flat bottom line reflects a margin squeeze from higher input costs, even as the company used its IPO proceeds to cut debt.
For a recycled polyester fibre maker, the quarter was a test of pricing power. Unitec Fibres delivered higher sales but saw all the gains absorbed by rising costs, leaving profitability unchanged.
The numbers show a clear squeeze. Revenue grew 8% year-on-year and sequentially to ₹121 crore. Yet net profit was flat at ₹4 crore, identical to last year. The net profit margin contracted 30 basis points to 3.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 112
- Revenue (₹ Cr), Q2 FY27: 121
- Profit (₹ Cr), Q2 FY26: 4
- Profit (₹ Cr), Q2 FY27: 4
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 112
- Revenue (₹ Cr), Q2 FY27: 121
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 4
- Profit (₹ Cr), Q2 FY27: 4
Net Profit Margin
- Net Profit Margin, Q2 FY26: 3.6%
- Net Profit Margin, Q2 FY27: 3.3%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 121YoY +8% | 112 |
| Profit (₹ Cr) | 4YoY 0% | 4 |
| Net Profit Margin | 3.3%YoY -8.3% | 3.6% |
Why the top line grew but profit didn't
Higher raw material costs were the primary culprit. A report from Multibagg.ai notes the cost of materials consumed surged to ₹83.3 crore for the half-year, up sharply from ₹71.3 crore a year earlier. This ate into the gains from an 8% sales increase.
Finance costs also rose, though the impact was smaller. The company's total expenses climbed 8.4%, exactly matching its revenue growth and explaining the stagnant profit.
A balance sheet reset in the background
The quarter's financial story extends beyond the P&L. Unitec Fibres completed its IPO in September, raising ₹34.5 crore. According to Mcapital, it used ₹29.9 crore of those proceeds in early October to repay a term loan.
Live Chart
· UNITEC
(BSE)
ISIN: INE0WOK01014
This move will sharply reduce net debt and cut future interest costs. It transforms a leveraged balance sheet but does not immediately fix the operating margin pressure from volatile petrochemical prices.
The outlook hinges on cost control
With the debt repayment, the interest burden will ease in coming quarters. However, the core challenge remains. The business is exposed to crude oil-linked input costs, which showed no sign of abating in Q2.
Demand for recycled fibre appears stable, but the ability to pass on cost increases will decide if profit growth resumes. The market reaction was muted, with the stock dipping slightly on results day, as tracked by Marketsmojo.
Key Points
- Revenue increased 8% year-on-year to ₹121 crore, showing steady demand for its recycled polyester fibre.
- Net profit was flat at ₹4 crore as a surge in raw material costs fully offset the sales growth.
- The company used IPO proceeds to repay ₹29.9 crore of debt, which will lower future interest expenses.
- Profitability remains under direct pressure from volatile petrochemical prices, a persistent sector risk.
Hexa Perspective
This quarter underscores a volume-driven business hitting a margin wall. Sales growth is intact, but the lack of operating leverage reveals a vulnerability to input costs that the debt repayment does not solve.
The coming quarters will test whether lower interest costs can provide enough lift to the bottom line, or if softer raw material prices are needed for meaningful profit expansion. Investors are left weighing a stronger balance sheet against still-thin and pressured margins.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.