Ravelcare (RAVEL) Q2 FY27 Profit Doubles, But a One-Off Income Flatters the Result
Ravelcare's Q2 profit surged 97% sequentially, but a large jump in other income accounted for much of the gain, raising questions about core earnings sustainability.
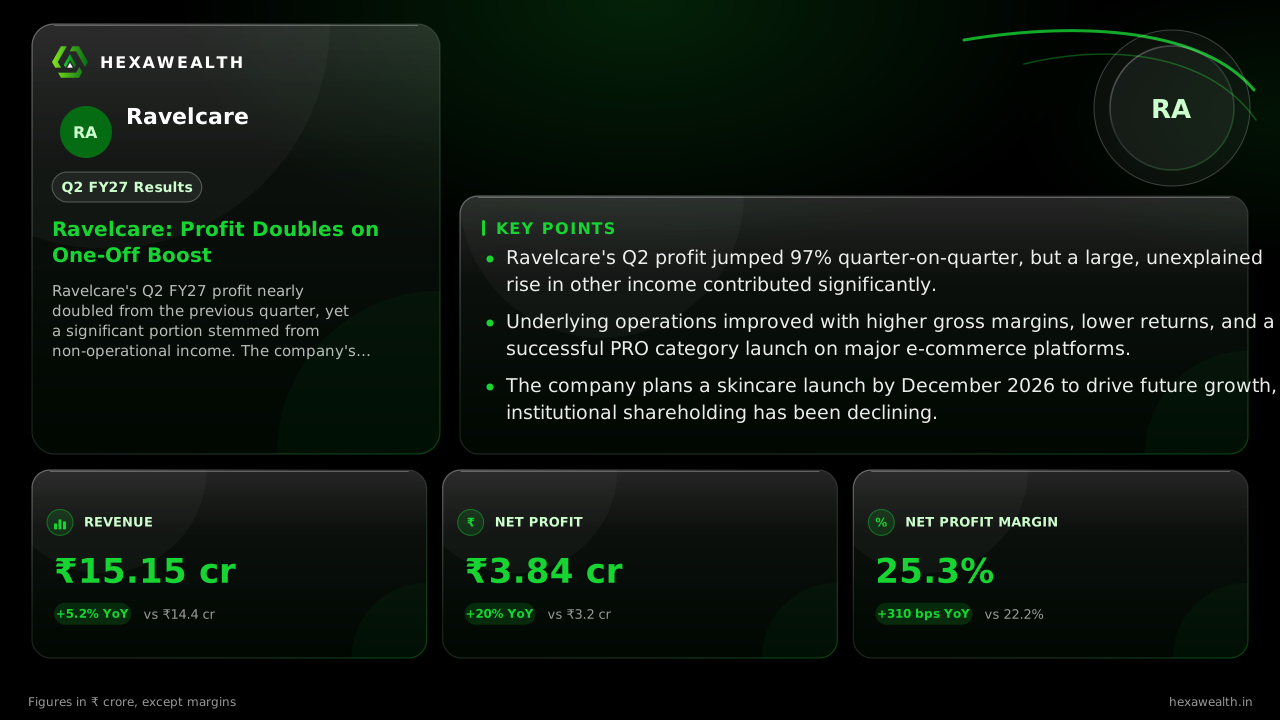
Ravelcare's Q2 FY27 profit nearly doubled from the previous quarter, yet a significant portion stemmed from non-operational income. The company's core revenue growth was steady, while institutional investors continued to reduce their stake.
For Ravelcare, a personal care brand betting on new launches, the September quarter delivered a headline profit surge. Yet the numbers reveal a more nuanced story where a one-time income boost played a starring role.
The company's profit after tax nearly doubled to ₹3.84 crore from the March quarter, on a 20.6% sequential rise in revenue to ₹15.15 crore. Year-on-year, profit grew a solid 20% while revenue was up 5.2%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 14.58
- Revenue (₹ Cr), Q2 FY26: 14.40
- Revenue (₹ Cr), Q4 FY26: 12.56
- Revenue (₹ Cr), Q2 FY27: 15.15
- Profit (₹ Cr), Q4 FY25: 1.50
- Profit (₹ Cr), Q2 FY26: 3.20
- Profit (₹ Cr), Q4 FY26: 1.95
- Profit (₹ Cr), Q2 FY27: 3.84
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 14.58
- Revenue (₹ Cr), Q2 FY26: 14.40
- Revenue (₹ Cr), Q4 FY26: 12.56
- Revenue (₹ Cr), Q2 FY27: 15.15
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 1.50
- Profit (₹ Cr), Q2 FY26: 3.20
- Profit (₹ Cr), Q4 FY26: 1.95
- Profit (₹ Cr), Q2 FY27: 3.84
Net Profit Margin
- Net Profit Margin, Q4 FY25: 10.3%
- Net Profit Margin, Q2 FY26: 22.2%
- Net Profit Margin, Q4 FY26: 15.5%
- Net Profit Margin, Q2 FY27: 25.3%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 15.15YoY +5.2% | 14.40 |
| Profit (₹ Cr) | 3.84YoY +20% | 3.20 |
| Net Profit Margin | 25.3%YoY +14% | 22.2% |
The one-off that lifted profit
The quarter's standout figure was other income, which surged to ₹0.72 crore from just ₹0.04 crore in the previous quarter. According to MarketsMojo, this accounted for a significant portion of the profit before tax of ₹5.17 crore. This non-operational gain, not detailed in filings, flattered the bottom-line growth.
Stripping that out, the underlying operating performance still showed improvement. Gross margin expanded 350 basis points year-on-year to 79.9%, notes Alfafinder. The company also cut product returns by 60% and raised average order value by 9% through website upgrades.
Growth bets and institutional skepticism
Management is upbeat, calling it a “solid first half” and betting on new products. A PRO range for marketplaces is live, and a personalised skincare line is slated for a December 2026 launch, with international expansion planned “soon”.
Live Chart
· RAVEL
(BSE)
ISIN: INE0W4D01018
Yet institutional investors have been pulling back. Data from Screener.in shows their combined stake fell from 11.68% in December 2025 to 5.8% by September 2026. This selling suggests some doubt about the sustainability of current margins or the execution of new launches.
Key Points
- Ravelcare's Q2 profit jumped 97% quarter-on-quarter, but a large, unexplained rise in other income contributed significantly.
- Underlying operations improved with higher gross margins, lower returns, and a successful PRO category launch on major e-commerce platforms.
- The company plans a skincare launch by December 2026 to drive future growth, but institutional shareholding has been declining.
Hexa Perspective
Ravelcare's quarter presents a split screen: strong operational discipline against a profit figure boosted by a one-off. The core business is healthier, with better margins and a new distribution channel gaining traction.
The path forward hinges on converting its product pipeline into consistent, high-margin sales without similar income surprises. The declining institutional interest adds a note of caution, making the coming quarters' pure operating performance critical for investor confidence.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.