Ravelcare (RAVEL) Q4 FY26 Profit Surges 30% Despite a 14% Revenue Drop
The digital-first personal care brand posted a 30% profit jump in Q4 FY26, driven by a sharp drop in expenses, even as revenue declined 14% year-on-year.
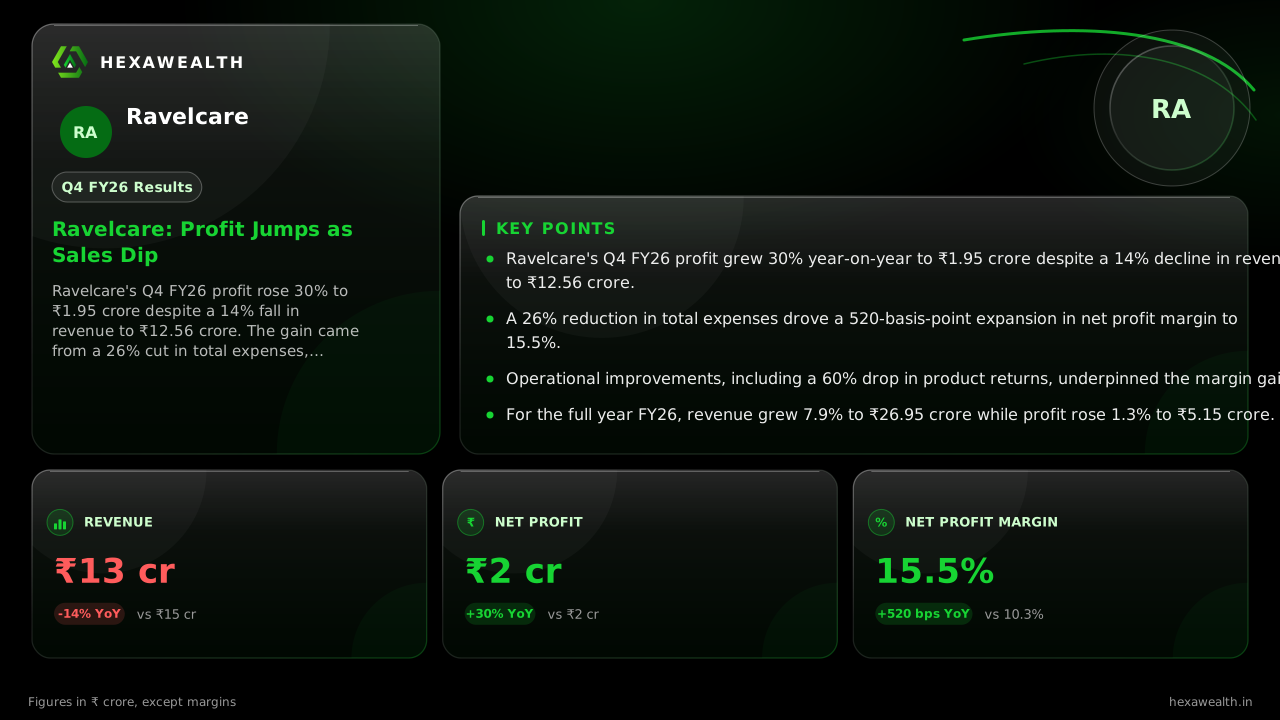
Ravelcare's Q4 FY26 profit rose 30% to ₹1.95 crore despite a 14% fall in revenue to ₹12.56 crore. The gain came from a 26% cut in total expenses, lifting the net profit margin by 520 basis points to 15.5%.
For a digital-first personal care brand, the path to profitability often runs through scaling sales. Ravelcare’s fourth quarter flipped that script, delivering a sharp profit gain on a smaller revenue base. The company’s net profit rose 30% year-on-year even as revenue fell 14%, a result of disciplined cost control.
The numbers tell a story of efficiency over growth. Revenue for the quarter ended March 2026 was ₹12.56 crore, down from ₹14.58 crore a year earlier. Profit, however, climbed to ₹1.95 crore from ₹1.5 crore. This pushed the net profit margin to 15.5%, a 520-basis-point expansion from 10.3% in Q4 FY25.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 14.58
- Revenue (₹ Cr), Q4 FY26: 12.56
- Profit (₹ Cr), Q4 FY25: 1.50
- Profit (₹ Cr), Q4 FY26: 1.95
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 14.58
- Revenue (₹ Cr), Q4 FY26: 12.56
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 1.50
- Profit (₹ Cr), Q4 FY26: 1.95
Net Profit Margin
- Net Profit Margin, Q4 FY25: 10.3%
- Net Profit Margin, Q4 FY26: 15.5%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 12.56YoY -14% | 14.58 |
| Profit (₹ Cr) | 1.95YoY +30% | 1.50 |
| Net Profit Margin | 15.5%YoY +50% | 10.3% |
The Expense Engine Behind the Profit
The profit surge was fueled entirely by a 26% drop in total expenses. According to data from newboard.in, operating profit for the half containing Q4 FY26 (H2 FY26) jumped to ₹2.73 crore from ₹1.28 crore a year ago. This was driven by a 60% reduction in product returns and a 9% increase in average order value after a website overhaul, as noted in an Alphatribe report.
These operational improvements are structural, not one-off. The company has maintained a lean cost structure, spending less than 1% of revenue on interest and 3.8% on employee costs for FY26, per The Economic Times. This discipline turned a revenue decline into a meaningful bottom-line gain.
A Full Year of Steady Growth
Zooming out, FY26 was a year of steady, if slower, expansion. Full-year revenue grew 7.9% to ₹26.95 crore, while profit inched up 1.3% to ₹5.15 crore. The annual net profit margin was a healthy 19.1%. The company has grown revenue at a blistering 141.8% CAGR over the past five years, albeit from a tiny base.
Live Chart
· RAVEL
(BSE)
ISIN: INE0W4D01018
Management is upbeat about the current fiscal year. An investor presentation highlighted by Alfafinder.com shows H1 FY27 revenue at ₹15.15 crore, up 20.7% from H2 FY26. Profit after tax nearly doubled to ₹3.84 crore. The company is debt-free with ₹26.6 crore in cash and plans to launch a personalised skincare range by December 2026.
Key Points
- Ravelcare's Q4 FY26 profit grew 30% year-on-year to ₹1.95 crore despite a 14% decline in revenue to ₹12.56 crore.
- A 26% reduction in total expenses drove a 520-basis-point expansion in net profit margin to 15.5%.
- Operational improvements, including a 60% drop in product returns, underpinned the margin gain.
- For the full year FY26, revenue grew 7.9% to ₹26.95 crore while profit rose 1.3% to ₹5.15 crore.
Hexa Perspective
This quarter presents a clear trade-off: profitability arrived ahead of scale. The margin expansion from cost control is impressive and suggests the business model can be lean. However, the revenue decline raises questions about demand saturation on its primary website, which still drives over 90% of sales. The upcoming skincare launch and expansion onto marketplaces through its PRO range are critical tests. They must reignite top-line growth without sacrificing the hard-won margin discipline. For now, the balance sheet is a strength, with zero debt and ample cash to fund this next phase.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.