Uniparts India (UNIPARTS) Q2 FY27 Profit Slips from Record High Despite 37% Revenue Growth
The auto parts maker posted its highest-ever quarterly sales, but a sequential profit dip reveals margin pressure from rising costs and expansion.
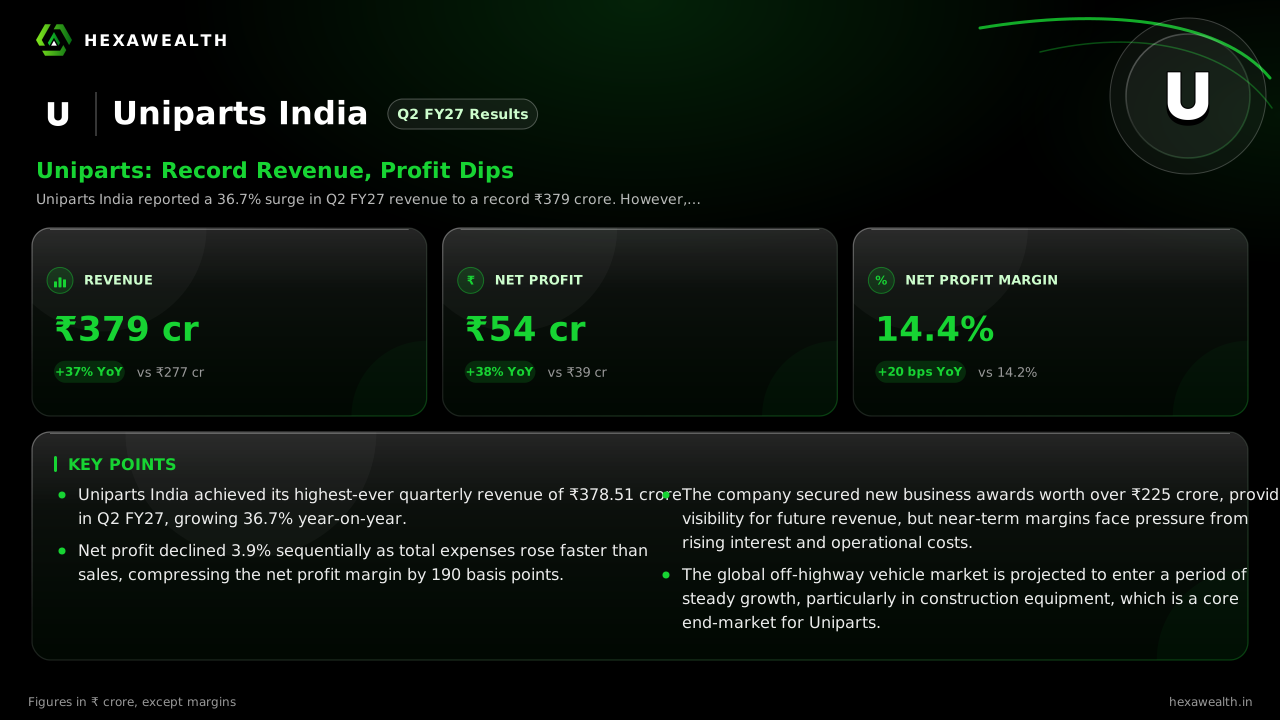
Uniparts India reported a 36.7% surge in Q2 FY27 revenue to a record ₹379 crore. However, net profit declined 3.9% sequentially as operational expenses grew faster than sales, squeezing margins.
Uniparts India’s business is built on supplying critical systems to global off-highway vehicle makers, a market emerging from a cyclical downturn. The September quarter delivered a record top line, but the bottom line tells a more nuanced story of growth meeting cost pressures.
Revenue rose 36.7% year-on-year to ₹378.51 crore, marking the company’s highest-ever quarterly sales according to its investor presentation. Sequentially, sales grew 9.0%. Net profit, however, declined 3.9% from the prior quarter to ₹54.43 crore, even as it rose 38.2% from a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 378.51YoY +37% | 347.38 | 276.83 |
| Profit (₹ Cr) | 54.43YoY +38% | 56.61 | 39.38 |
| Net Profit Margin (%) | 14.4YoY +1.4% | 16.3 | 14.2 |
Why the margin squeezed after a record quarter
Total expenses grew 10.8% quarter-on-quarter, outpacing the 9.0% revenue growth. This was driven by a 60.4% year-on-year jump in interest costs and a steady rise in employee costs, as reported by AutocarPro. The company’s net profit margin compressed by 190 basis points sequentially to 14.4%.
Management, in its presentation, highlighted new business awards exceeding ₹225 crore, primarily in construction and large agriculture. These wins, however, are yet to fully convert into revenue. The current quarter’s performance was supported by a stabilizing demand environment in key export markets.
The outlook rests on execution and costs
The company’s long-term margin guidance remains at 20%, according to its investor presentation. Near-term profitability will hinge on managing the cost inflation that dented the September quarter. A report by Interact Analysis forecasts strong growth for construction equipment in North America and Europe in 2027, which aligns with Uniparts’ key markets.
Capital is being deployed for expansion, including a Mexico warehouse and the restoration of a Ludhiana finishing shop. Arthneeti.com notes borrowings have increased, pushing the debt-to-equity ratio from 0.07 in FY24 to 0.11 in FY26, funding this growth.
Key Points
- Uniparts India achieved its highest-ever quarterly revenue of ₹378.51 crore in Q2 FY27, growing 36.7% year-on-year.
- Net profit declined 3.9% sequentially as total expenses rose faster than sales, compressing the net profit margin by 190 basis points.
- The company secured new business awards worth over ₹225 crore, providing visibility for future revenue, but near-term margins face pressure from rising interest and operational costs.
- The global off-highway vehicle market is projected to enter a period of steady growth, particularly in construction equipment, which is a core end-market for Uniparts.
Hexa Perspective
Uniparts is capturing the early stages of a sector recovery, evidenced by record sales and a robust order pipeline. The quarter’s margin squeeze, however, underscores the challenge of translating top-line momentum into bottom-line growth amid rising costs and expansionary investments. Investors are weighing strong revenue visibility against the pressure on profitability. The stock’s valuation, at a P/E of 12.7 against an industry average of 44.9, reflects this tension between cyclical recovery and execution risks on margins.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.