Steelman Telecom (STML) Q4 FY26's Q4 Loss Widens Despite Lower Expenses
Steelman Telecom's Q4 FY26 saw revenue fall 11.6% year-on-year, leading to a larger net loss, as high interest costs offset gains from exiting a loss-making subsidiary.
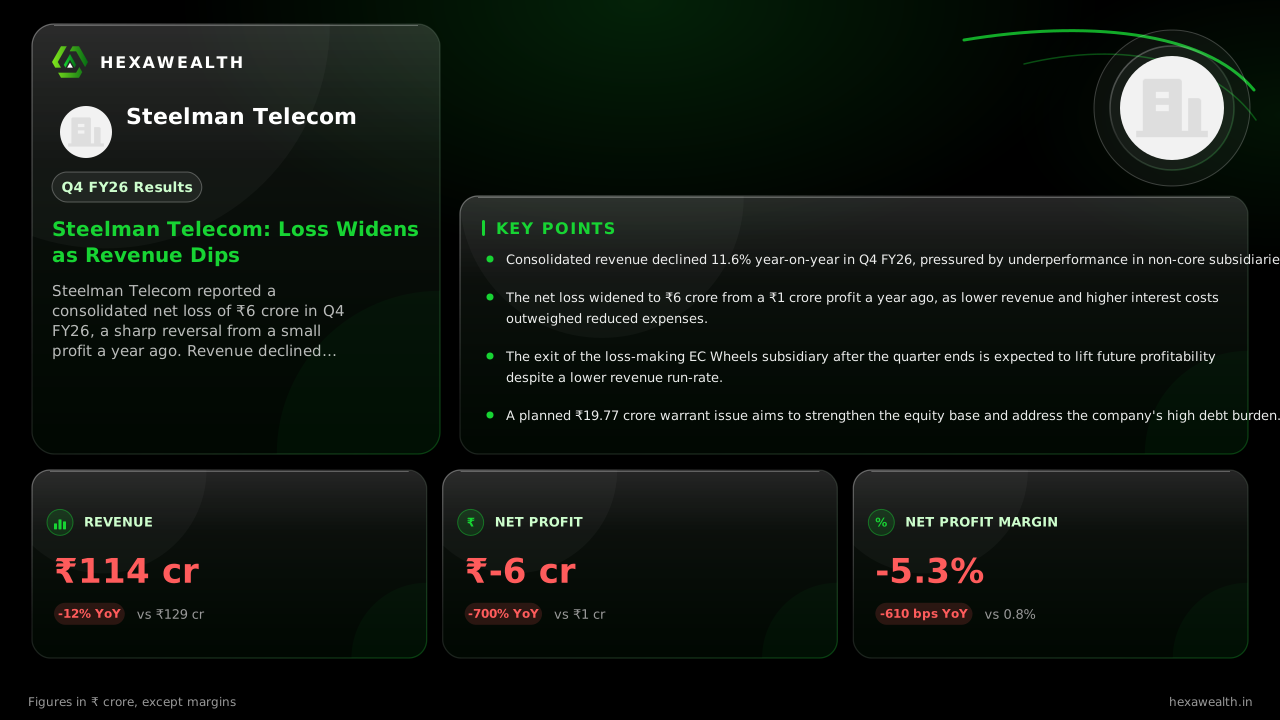
Steelman Telecom reported a consolidated net loss of ₹6 crore in Q4 FY26, a sharp reversal from a small profit a year ago. Revenue declined 11.6% YoY to ₹114 crore, with high debt costs and a shrinking top line pressuring the bottom line.
For a telecom services firm built on field maintenance for giants like Airtel and Jio, a shrinking top line is a direct challenge to its core business model. Steelman Telecom's March quarter delivered exactly that, with revenue falling and a small year-ago profit turning into a loss, despite a major strategic move to shed a money-losing division.
The numbers show a company caught between two stories. Revenue for Q4 FY26 was ₹114 crore, down 11.6% from a year earlier and 2.6% from the previous quarter. The net loss widened to ₹6 crore, a stark reversal from the ₹1 crore profit posted in Q4 FY25.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 116.0
- Revenue (₹ Cr), Q2 FY25: 102.0
- Revenue (₹ Cr), Q4 FY25: 129.0
- Revenue (₹ Cr), Q2 FY26: 117.0
- Revenue (₹ Cr), Q4 FY26: 114.0
- Profit (₹ Cr), Q4 FY24: -6.0
- Profit (₹ Cr), Q2 FY25: -10.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: -9.0
- Profit (₹ Cr), Q4 FY26: -6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 116.0
- Revenue (₹ Cr), Q2 FY25: 102.0
- Revenue (₹ Cr), Q4 FY25: 129.0
- Revenue (₹ Cr), Q2 FY26: 117.0
- Revenue (₹ Cr), Q4 FY26: 114.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: -6.0
- Profit (₹ Cr), Q2 FY25: -10.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: -9.0
- Profit (₹ Cr), Q4 FY26: -6.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY24: -5.2
- Net Profit Margin (%), Q2 FY25: -9.8
- Net Profit Margin (%), Q4 FY25: 0.8
- Net Profit Margin (%), Q2 FY26: -7.7
- Net Profit Margin (%), Q4 FY26: -5.3
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 114.0YoY -12% | 129.0 |
| Profit (₹ Cr) | -6.0YoY -700% | 1.0 |
| Net Profit Margin (%) | -5.3YoY -762% | 0.8 |
Why the top line shrank
Research from MarketPing shows the consolidated revenue decline was driven by steep losses at subsidiaries, particularly the EV cab-hiring unit EC Wheels India. This segment lost ₹19.1 crore in FY26, dragging down the group. While total expenses fell 16.5% year-on-year, reflecting cost control, it wasn't enough to offset the revenue drop and a 33% rise in interest costs.
The silver lining is that this drag is now history. According to mcapital.in, EC Wheels ceased to be a subsidiary in September 2026, becoming a 49.47% associate. This deconsolidation cuts reported revenue but removes the unit's heavy losses from the profit and loss statement.
A balance sheet under strain
Even with that fix, the core telecom business runs on a levered balance sheet. Net debt stood at an estimated ₹66 crore at the end of FY26, with a debt-to-equity ratio of 1.14. The high cost of carrying this debt is clear: interest expense rose to ₹4 crore in Q4, up a third from last year.
Live Chart
· STML
(BSE)
ISIN: INE0MSK01016
Management is addressing this through a planned equity infusion. The company has received BSE approval for a preferential issue of warrants worth about ₹19.77 crore, as reported by alfafinder.com. If fully subscribed, this would boost net worth and help pare down debt.
Key Points
- Consolidated revenue declined 11.6% year-on-year in Q4 FY26, pressured by underperformance in non-core subsidiaries.
- The net loss widened to ₹6 crore from a ₹1 crore profit a year ago, as lower revenue and higher interest costs outweighed reduced expenses.
- The exit of the loss-making EC Wheels subsidiary after the quarter ends is expected to lift future profitability despite a lower revenue run-rate.
- A planned ₹19.77 crore warrant issue aims to strengthen the equity base and address the company's high debt burden.
Hexa Perspective
The quarter closes a difficult year, but the subsequent deconsolidation of EC Wheels is a pivotal reset. The trade-off is clear: a smaller, cleaner telecom-focused company with a better shot at profitability, versus a larger consolidated entity that was consistently loss-making.
The path forward hinges on the core telecom maintenance business winning enough work from a healthy Indian capex cycle to grow its now-smaller revenue base. Success also requires the warrant issue to conclude, easing the interest burden that consumed a large part of operating profit this quarter. Investors are essentially betting that management's surgical removal of the biggest problem will allow the underlying business to finally shine.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.