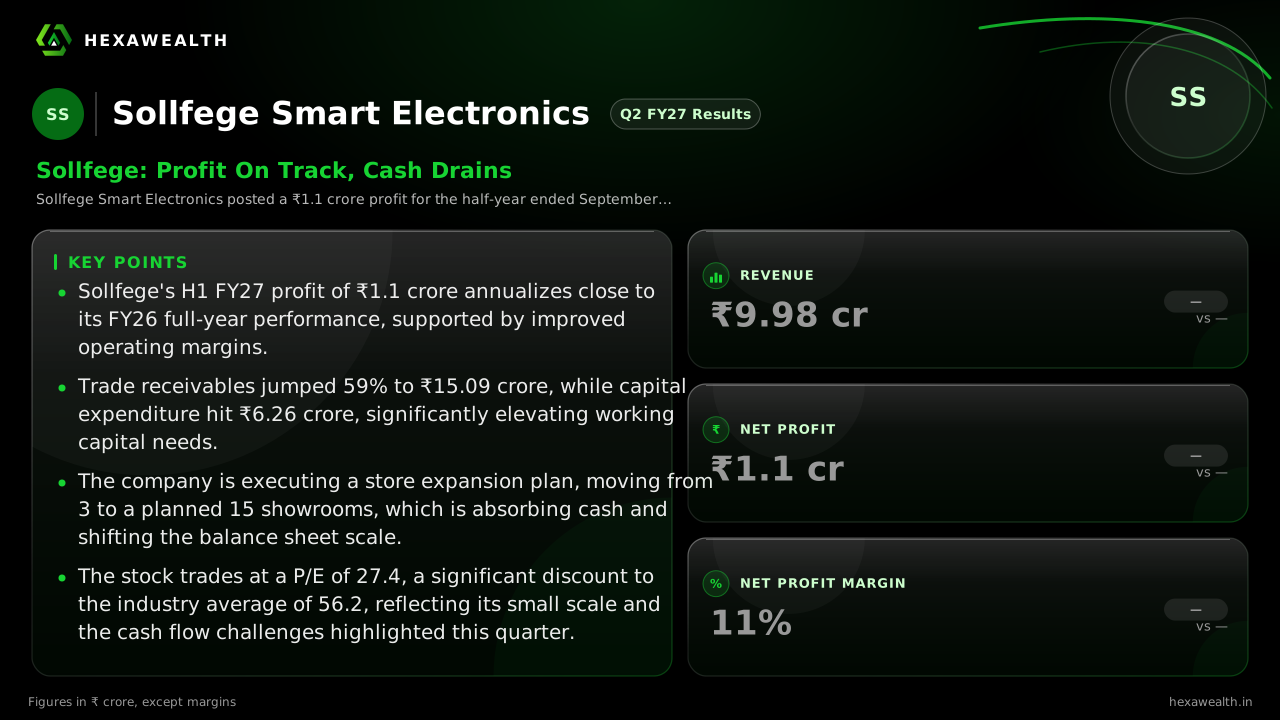
Sollfege (SOLLFEGE) Q2 FY27 Profit Holds as Receivables and Capex Soar
The electronics distributor reported a ₹1.1 crore H1 profit, but a 59% jump in receivables and heavy capital spending signal rising working capital needs.
Sollfege Smart Electronics posted a ₹1.1 crore profit for the half-year ended September 2026. While margins improved, trade receivables surged 59% and the company spent ₹6.26 crore on fixed assets, absorbing cash.
For a newly listed distributor of premium electronics, the first reported numbers set the tone for capital allocation. Sollfege Smart Electronics delivered a profit, but the balance sheet tells a story of cash being redirected into expansion and customer credit.
The company reported a standalone net profit of ₹1.1 crore on revenue of ₹9.98 crore for the half-year ended September 2026. This puts its annualized profit run-rate roughly in line with the ₹2.19 crore earned in the full year FY26.
| Period Ended | Revenue (₹ Cr) | Profit (₹ Cr) | Net Profit Margin |
|---|---|---|---|
| Sep 2026 (H1 FY27) | 9.98 | 1.1 | 11.0% |
The Margin Win and the Cash Catch
Operating performance showed strength, with one analysis by mCapital.in noting the half-year operating margin improved to about 22%, up from 18.9% in FY26. This margin expansion helped offset a revenue run-rate that is tracking about 10% below the prior full-year level.
The catch lies in how that profit is being realized. Trade receivables ballooned by 59% to ₹15.09 crore, according to a report by multibagg.ai. Simultaneously, the company deployed ₹6.26 crore into purchases of fixed assets, more than doubling its capital spending compared to all of last year.
Funding the Growth Engine
This combination—softer sales, longer customer payment cycles, and aggressive asset building—points to rising working capital and funding needs. The company's debt-to-equity ratio stands at 0.58, indicating moderate leverage. However, the recent surge in spending and receivables will test this structure.
Live Chart
· SOLLFEGE
(BSE)
ISIN: INE17HG01015
The capital expenditure aligns with an ambitious store rollout plan. As noted by sovrenn.com, the company aims to expand from 3 to 15 showrooms in FY27, funded partly by its recent IPO. The current half-year spend suggests this expansion is underway.
Key Points
- Sollfege's H1 FY27 profit of ₹1.1 crore annualizes close to its FY26 full-year performance, supported by improved operating margins.
- Trade receivables jumped 59% to ₹15.09 crore, while capital expenditure hit ₹6.26 crore, significantly elevating working capital needs.
- The company is executing a store expansion plan, moving from 3 to a planned 15 showrooms, which is absorbing cash and shifting the balance sheet scale.
- The stock trades at a P/E of 27.4, a significant discount to the industry average of 56.2, reflecting its small scale and the cash flow challenges highlighted this quarter.
Hexa Perspective
The quarter frames Sollfege's central tension: it can generate a profit, but converting that profit into sustainable cash flow is the immediate hurdle. The receivables surge, if it reflects slower collections rather than just sales timing, will pressure liquidity as the company funds its store rollout.
Investors are weighing margin improvement against the capital intensity of growth. The valuation discount to peers acknowledges these execution risks. The next few quarters will reveal whether the new stores can drive revenue acceleration fast enough to outpace the rising working capital cycle.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.