Superior Industrial Enterprises (SIEL) Q2 FY27 Profit Jumps 23x as Margins Widen
The packaging firm's Q2 FY27 profit surged over 2,300% year-on-year to ₹1.93 crore, driven by operating leverage and a zero tax charge, even as revenue fell sequentially.
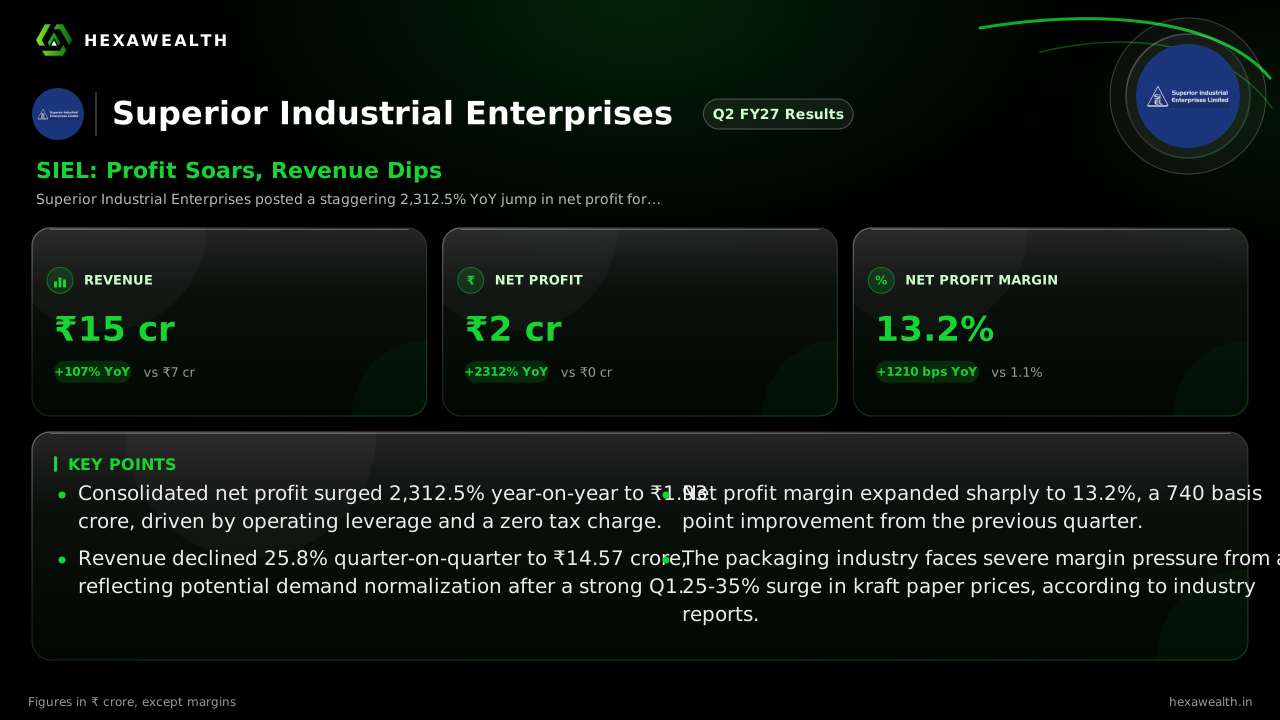
Superior Industrial Enterprises posted a staggering 2,312.5% YoY jump in net profit for Q2 FY27, reaching ₹1.93 crore. This leap was fueled by strong operating leverage and a zero tax charge, even though consolidated revenue declined 25.8% from the previous quarter.
For a corrugated box maker, the quarter is a tug-of-war between rising raw material costs and the ability to pass them on. Superior Industrial Enterprises just showed how powerful operating leverage can be when that balance tilts in its favor. Its consolidated net profit soared over 24 times from a low base, even as revenue retreated from a strong prior quarter.
The numbers tell a story of two different comparisons. Year-on-year, revenue more than doubled to ₹14.57 crore and profit leapt to ₹1.93 crore from just ₹0.08 crore. Sequentially, revenue fell 25.8% from Q1's ₹19.63 crore, yet profit still grew 69.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 14.57YoY +107% | 19.63 | 7.04 |
| Profit (₹ Cr) | 1.93YoY +2312% | 1.14 | 0.08 |
| Net Profit Margin | 13.2%YoY +1100% | 5.8% | 1.1% |
The Leverage Behind the Leap
The staggering profit growth stems from a powerful combination. According to a report by ScanX.trade, while consolidated revenue grew 107% YoY, total expenses rose only 81%. This operating leverage allowed profit before tax to expand over 24 times.
A zero tax charge for the standalone entity, noted in the same report, allowed all pre-tax profit to flow to the bottom line. This helped the net profit margin jump 740 basis points sequentially to 13.2%.
A Revenue Dip Amidst Industry Squeeze
The sequential revenue decline comes as the broader industry faces severe cost pressure. Reports from The Hindu BusinessLine and PrintWeek India detail a 25-35% surge in kraft paper prices, which constitutes about 75% of product cost.
Manufacturers are struggling to pass these hikes to large corporate customers quickly. This mismatch creates a working capital crunch, exacerbated by an inverted GST structure where input tax is higher than output tax.
The Outlook Hinges on Pricing Power
With net profit margin now well above its trailing twelve-month average of 6.5%, the key question is sustainability. The profit surge was built on operational efficiency from a higher revenue base and a favorable tax outcome.
The coming quarters will test whether Superior Industrial can maintain these margins as the full force of input cost inflation hits. Success depends on its ability to renegotiate prices with beverage clients like Coca-Cola bottlers, a core customer segment.
Key Points
- Consolidated net profit surged 2,312.5% year-on-year to ₹1.93 crore, driven by operating leverage and a zero tax charge.
- Revenue declined 25.8% quarter-on-quarter to ₹14.57 crore, reflecting potential demand normalization after a strong Q1.
- Net profit margin expanded sharply to 13.2%, a 740 basis point improvement from the previous quarter.
- The packaging industry faces severe margin pressure from a 25-35% surge in kraft paper prices, according to industry reports.
Hexa Perspective
This quarter showcases the potent earnings power when a packaging company manages costs effectively against a growing top line. The low year-ago base flatters the growth percentage, but the sequential margin expansion is a tangible operational win.
The sustainability of this performance is the real debate. With the industry reporting severe raw material inflation and slow price pass-through, the high margins of Q2 face a clear near-term threat. Investors are left weighing a stellar profit print against a looming cost squeeze that could pressure earnings in the next quarter or two.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.