Shri Ahimsa Naturals (SHRIAHIMSA) Q2 FY27 Profit Lags a 32% Revenue Surge as Costs Mount
The natural caffeine producer posted strong top-line growth but saw profitability erode sharply due to rising expenses and a surge in interest costs.
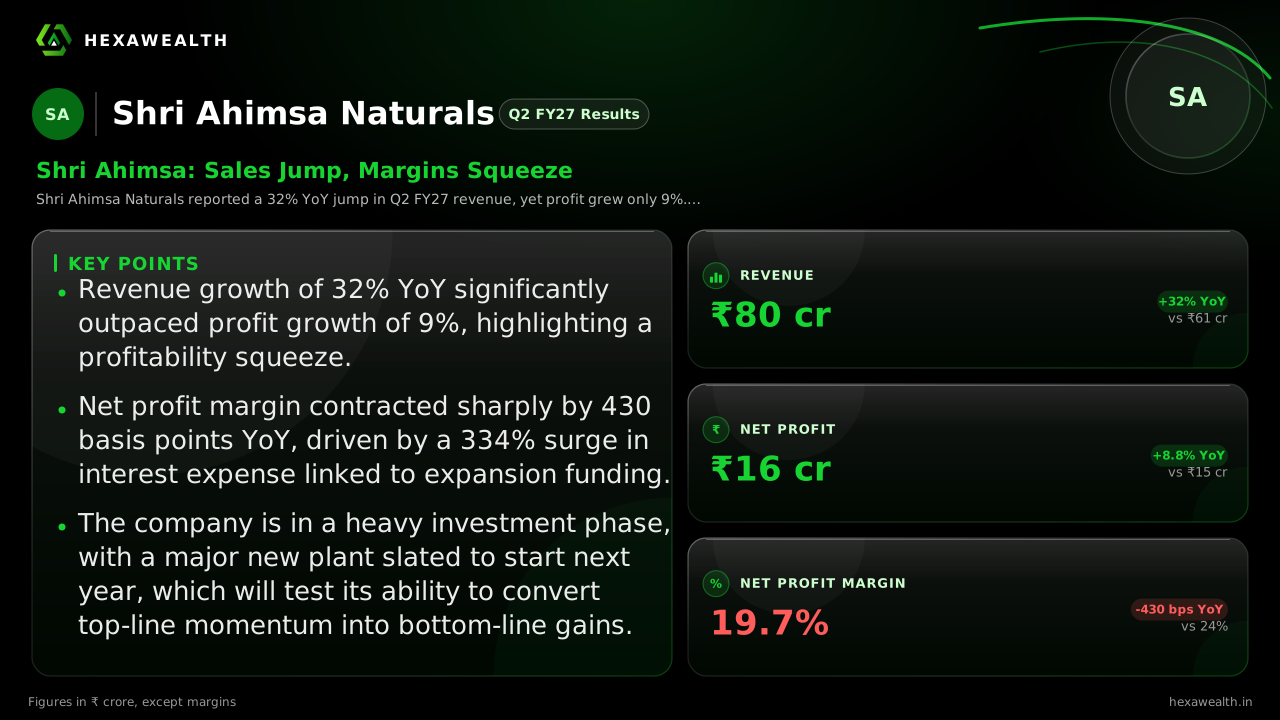
Shri Ahimsa Naturals reported a 32% YoY jump in Q2 FY27 revenue, yet profit grew only 9%. A steep rise in interest expense and other costs compressed the net profit margin by 430 basis points from a year ago.
For Shri Ahimsa Naturals, the story is one of powerful demand meeting the costs of funding its own growth. The company, which extracts natural caffeine from coffee industry waste for global energy drinks, saw revenue leap 32% from a year ago. Yet that sales surge translated into just 9% profit growth, as a sharp rise in interest expense and other costs took a heavy toll on margins.
The numbers tell the tension clearly. Revenue reached ₹80.05 crore, up 28% from the prior quarter. Profit rose to ₹15.8 crore, a more modest 8% sequential gain. The net profit margin fell to 19.7%, down 350 basis points from Q1 and 430 points from last September.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 80.05 | 62.8 |
| Profit (₹ Cr) | 15.8 | 14.59 |
| Net Profit Margin (%) | 19.7 | 23.2 |
Why the profit didn't keep up
A 334% year-on-year surge in interest expense was the primary culprit behind the margin compression. Interest cost jumped to ₹1.44 crore from just ₹0.33 crore a year earlier. According to a report from Newboard, this reflects higher borrowings to fund the company’s major greenfield expansion at Sawarda.
Total expenses grew 38% YoY, far outpacing revenue growth. Other income also fell 36%, providing less of a cushion. The company’s core business of selling natural caffeine remains strong, with exports making up 91% of revenue, as noted by Stockscans. But the financial cost of building for the future is now hitting the income statement.
The expansion behind the costs
The pressure is directly tied to a ₹60.7 crore capacity expansion. Minerva Capital Research notes the Sawarda plant will add 700 MTPA of natural caffeine capacity and is expected to start operations by March 2027. The project is funded partly by debt, explaining the interest spike, and aims to make the company the world's largest natural caffeine supplier.
Current capacity at the Bagru plant was about 74% utilized last year, leaving room for near-term volume growth before Sawarda comes online. The market is watching whether sales can continue their strong pace to absorb these new fixed costs when the plant is commissioned.
Key Points
- Revenue growth of 32% YoY significantly outpaced profit growth of 9%, highlighting a profitability squeeze.
- Net profit margin contracted sharply by 430 basis points YoY, driven by a 334% surge in interest expense linked to expansion funding.
- The company is in a heavy investment phase, with a major new plant slated to start next year, which will test its ability to convert top-line momentum into bottom-line gains.
Hexa Perspective
The quarter frames a classic growth-investment trade-off. Strong demand for Shri Ahimsa's core product is evident, but the cost of financing its ambitious expansion is now materially denting earnings. The margin compression is not a temporary blip; it is structural as long as debt funds the capex.
The investment case now hinges on execution. The new Sawarda plant must ramp up smoothly and find ready demand to generate the operating leverage needed to offset these higher financial costs. Until then, earnings growth is likely to remain subdued compared to the impressive sales momentum.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.