Sheraton Properties (ZSHERAPR) Q2 FY27 Profit Rises 14% on Volatile Investment Gains
The finance firm's Q2 profit grew 14% YoY, but the surge from Q1 masks a business model entirely reliant on unpredictable investment returns.
Sheraton Properties & Finance reported a 14% yearly rise in net profit for Q2 FY27. The headline growth, however, stems entirely from volatile 'other income' as the company reported zero revenue from operations.
For Sheraton Properties & Finance, quarterly results are less about running a business and more about timing its portfolio. The September quarter delivered a predictable outcome: profit rose 14% from a year ago, but the source was entirely investment gains, not a core lending operation.
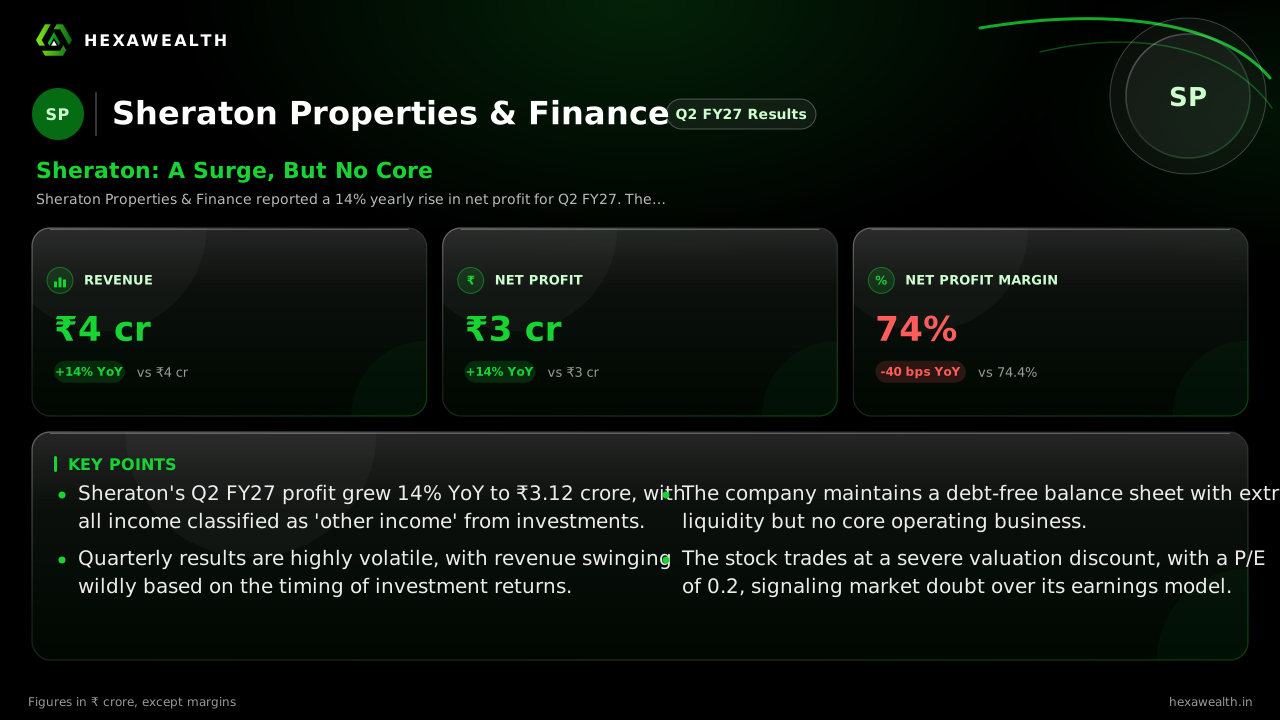
Revenue of ₹4.21 crore and profit of ₹3.12 crore both grew about 14% year-on-year. The more dramatic story is the quarter-on-quarter surge from an exceptionally low base in June. A ScanX report notes the company's total income consisted 100% of 'other income', with revenue from operations remaining nil.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 4.21YoY +14% | 0.80 | 3.69 |
| Profit (₹ Cr) | 3.12YoY +14% | 0.54 | 2.74 |
| Net Profit Margin | 74.0%YoY -0.5% | 67.4% | 74.4% |
The table reveals extreme volatility, with revenue swinging from near-zero to over ₹4 crore in consecutive quarters. This pattern confirms the company operates as an investment holding entity, as described by ScanX.
Why Profits Swing Wildly
Earnings depend on the scale and timing of returns from its financial assets. The 40 basis point dip in net profit margin year-on-year, despite higher profit, shows costs grew slightly faster than investment income. There is no operating leverage to smooth these results.
A Pristine But Passive Balance Sheet
The company's strength is its balance sheet, not its income statement. It carries no debt and holds a massive cash position, with a current ratio over 4,900. This positions it as a liquid holding company waiting for opportunities, not an active lender generating steady cash flow.
The Market's Verdict
The market heavily discounts this unpredictable model. Sheraton trades at a P/E of 0.2, a 99% discount to the industry average, according to Equifiz data. This reflects deep skepticism about the sustainability and value of earnings derived purely from portfolio moves.
Key Points
- Sheraton's Q2 FY27 profit grew 14% YoY to ₹3.12 crore, with all income classified as 'other income' from investments.
- Quarterly results are highly volatile, with revenue swinging wildly based on the timing of investment returns.
- The company maintains a debt-free balance sheet with extreme liquidity but no core operating business.
- The stock trades at a severe valuation discount, with a P/E of 0.2, signaling market doubt over its earnings model.
Hexa Perspective
The quarter underscores Sheraton's identity as a registered investment pool rather than a financial services firm. The extreme valuation gap shows the market assigns little value to tiny, erratic profits from portfolio activity. For the narrative to change, the company must deploy its cash hoard into a revenue-generating business or deliver consistently large investment returns. Until then, its financials will remain a series of unpredictable pulses.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.