Indo Borax (INDOBORAX) Q2 FY27 Profit Drops 71% as Acquisition Costs Bite
Indo Borax's Q2 profit fell 71% year-on-year as a major acquisition drove up employee and interest costs, sharply compressing margins despite stable revenue.
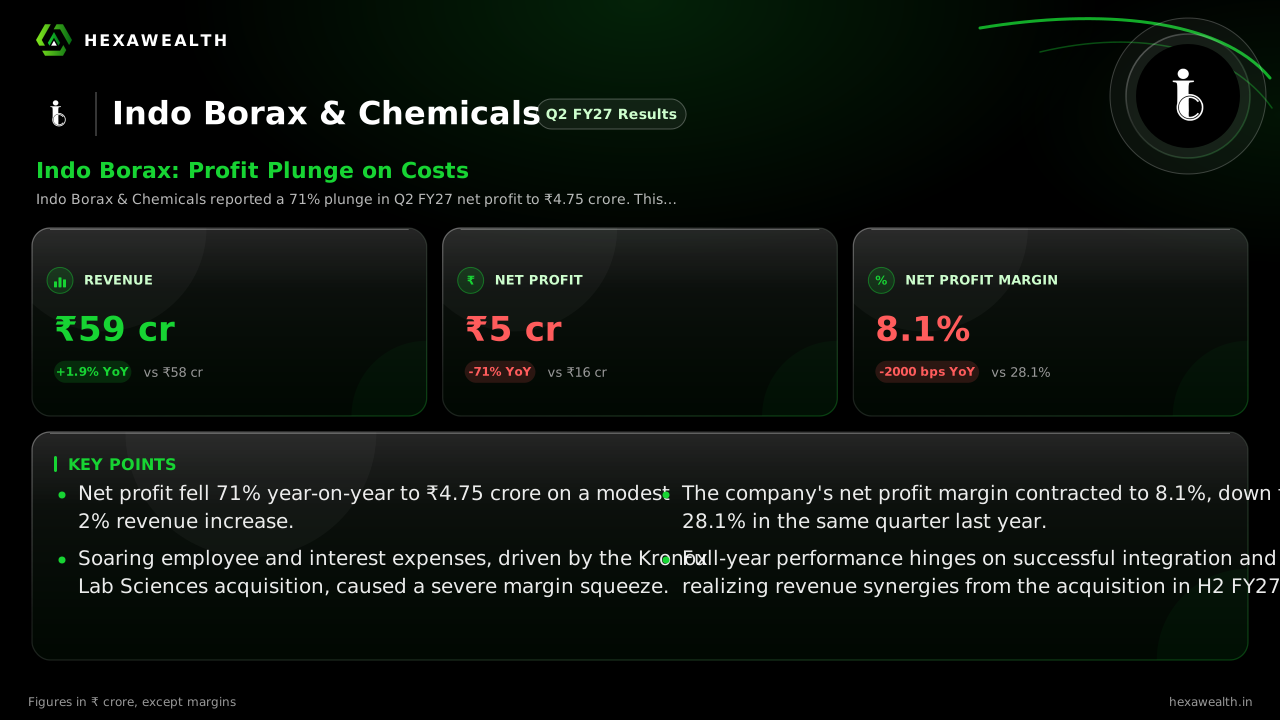
Indo Borax & Chemicals reported a 71% plunge in Q2 FY27 net profit to ₹4.75 crore. This sharp decline was driven by a surge in employee and interest expenses following the acquisition of Kronox Lab Sciences, which overwhelmed a modest 2% revenue increase.
Indo Borax & Chemicals entered the September quarter on a high note, with Q1 FY27 showing strong profit growth. The story for Q2, however, was one of costs overwhelming the top line. Revenue held steady, but a sharp rise in expenses linked to a major acquisition sent profitability tumbling.
The numbers tell a clear story of margin compression. Consolidated revenue was nearly flat at ₹58.94 crore, up just 1.9% from a year ago. Profit, however, collapsed 70.8% year-on-year to ₹4.75 crore. The net profit margin shrank to 8.1%, down 20 percentage points from the 28.1% margin in Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 58.94YoY +1.9% | 70.36 | 57.85 |
| Profit (₹ Cr) | 4.75YoY -71% | 16.25 | 16.26 |
| Net Profit Margin | 8.1%YoY -71% | 23.1% | 28.1% |
Why the bottom line collapsed
Two cost lines exploded. Employee benefit expense more than doubled year-on-year to ₹10.06 crore, according to a report by Multibagg.ai. Finance costs, negligible a year ago, surged to ₹1.13 crore. These jumps are directly tied to the company's acquisition of a 64.26% stake in Kronox Lab Sciences, which closed on September 29, 2026.
The acquisition was funded by new debt, adding ₹288.67 crore in borrowings to the balance sheet. A report from Sahi.com noted the resulting operational EBITDA margin plunged to 2.52% from 18.15% a year earlier, highlighting severe cost pressure. Management had flagged Q2 as a seasonally softer period, but the acquisition's financial impact was the dominant force.
The integration phase ahead
For investors, the key question is how long this margin squeeze lasts. The company is now in an integration phase, with the costs of consolidating Kronox hitting the income statement. The full benefit of the acquisition, including revenue from Kronox's high-purity specialty chemicals, will take time to materialize.
Management guidance, noted in a summary by guidance.fyi, targets FY27 revenue of ₹250-260 crore with a 20% EBITDA margin. Achieving that implies a significant recovery from Q2's depressed levels in the second half of the year. The stock, up 66.5% over the past year, already reflects long-term optimism around the strategic move.
Key Points
- Net profit fell 71% year-on-year to ₹4.75 crore on a modest 2% revenue increase.
- Soaring employee and interest expenses, driven by the Kronox Lab Sciences acquisition, caused a severe margin squeeze.
- The company's net profit margin contracted to 8.1%, down from 28.1% in the same quarter last year.
- Full-year performance hinges on successful integration and realizing revenue synergies from the acquisition in H2 FY27.
Hexa Perspective
This quarter is a clear case of strategic pain before potential gain. The acquisition of Kronox is a meaningful expansion into high-value specialty chemicals, but the near-term cost absorption is severe. The 20-percentage-point margin contraction shows how completely the new debt and consolidation costs have overwhelmed the core boron business's steady performance.
The path forward depends on execution. If management can stabilize the cost base and begin showing revenue growth from the combined entity in the coming quarters, the strategic rationale may hold. Until then, the stock's rich valuation—trading at a 56.7% discount to the industry PE per the payload—faces a reality check from sharply lower quarterly earnings.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.