Shivchem Agro (SHIVCHEM) Q2 FY27 Profit Jumps 87% as IPO Funds Expansion
The agrochemical formulator posted strong half-year growth, but higher input costs and stretched receivables highlight the cash demands of its expansion.
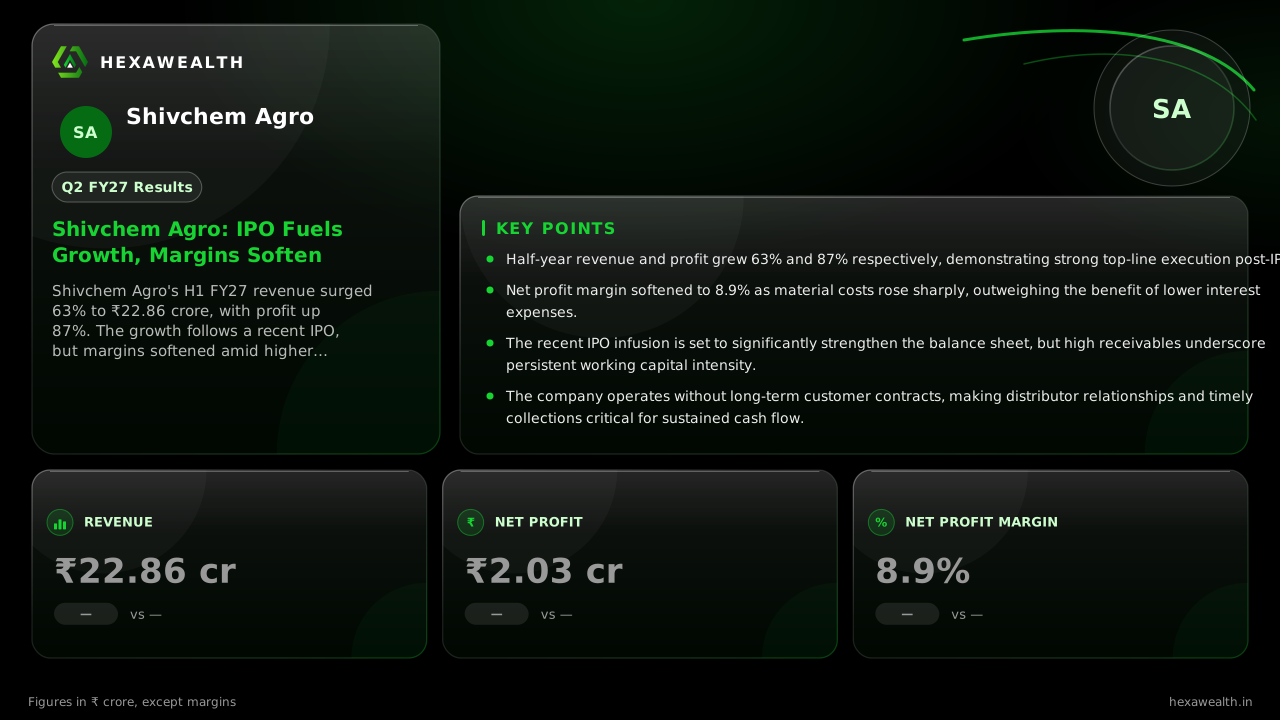
Shivchem Agro's H1 FY27 revenue surged 63% to ₹22.86 crore, with profit up 87%. The growth follows a recent IPO, but margins softened amid higher material costs and working capital remains a key focus.
For a newly listed agrochemical formulator, the first report card after an IPO is about proving growth can be funded. Shivchem Agro’s half-year to September 2026 shows exactly that, with revenue surging 63% to ₹22.86 crore and profit jumping 87% to ₹2.03 crore. The numbers, however, also reveal the cost of that expansion in a tight market.
The half-year scorecard shows a net profit margin of 8.9%, slightly below the 9.7% recorded for the full FY26. This came despite a helpful 25% drop in finance costs as borrowings were reduced.
| Metric | CurrentSep 2026 (H1 FY27) |
|---|---|
| Revenue (₹ Cr) | 22.86 |
| Profit (₹ Cr) | 2.03 |
| Net Profit Margin (%) | 8.9 |
The Cost of a Sales Surge
The primary driver behind the margin pressure was a sharp rise in input costs. According to Reports Radar, the cost of materials consumed nearly tripled to ₹15.86 crore. This reflects both higher sales volumes and the challenging price environment for agrochemical inputs noted by brokerages like Jefferies and Elara Securities. Weak monsoon conditions have suppressed industry-wide demand, limiting the company's ability to fully pass on cost increases.
A Balance Sheet in Transition
The recent ₹14.01 crore IPO is the quarter's defining event, completed in early October. Mcapital estimates the proceeds will more than double the company's net worth and cut net debt by 41–55%. This provides crucial funding for working capital, which remains a strain. Trade receivables nearly doubled to ₹22.48 crore, reports Radar notes, indicating cash collection continues to lag sales growth.
Key Points
- Half-year revenue and profit grew 63% and 87% respectively, demonstrating strong top-line execution post-IPO.
- Net profit margin softened to 8.9% as material costs rose sharply, outweighing the benefit of lower interest expenses.
- The recent IPO infusion is set to significantly strengthen the balance sheet, but high receivables underscore persistent working capital intensity.
- The company operates without long-term customer contracts, making distributor relationships and timely collections critical for sustained cash flow.
Hexa Perspective
Shivchem Agro has validated its growth story with a robust half-year performance, squarely addressing the scale question an IPO poses. The capital raise provides a necessary buffer against the working capital cycle that has historically consumed cash.
The test now is durability. Profit growth currently outpaces cash generation, and the margin dip shows vulnerability to input cost swings in a subdued demand environment. The company's prospects hinge on converting its expanded distributor network into predictable, collected sales, not just booked revenue.
Live Chart
· SHIVCHEM
(BSE)
ISIN: INE18CU01023
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.