Shipwaves (SHIPWAVES) Q4 FY26 Posts Q4 Loss Despite Revenue Uptick as Expenses Spike
A sharp quarterly loss capped a difficult year for the digital freight forwarder, with a surge in expenses and a heavy cash burn.
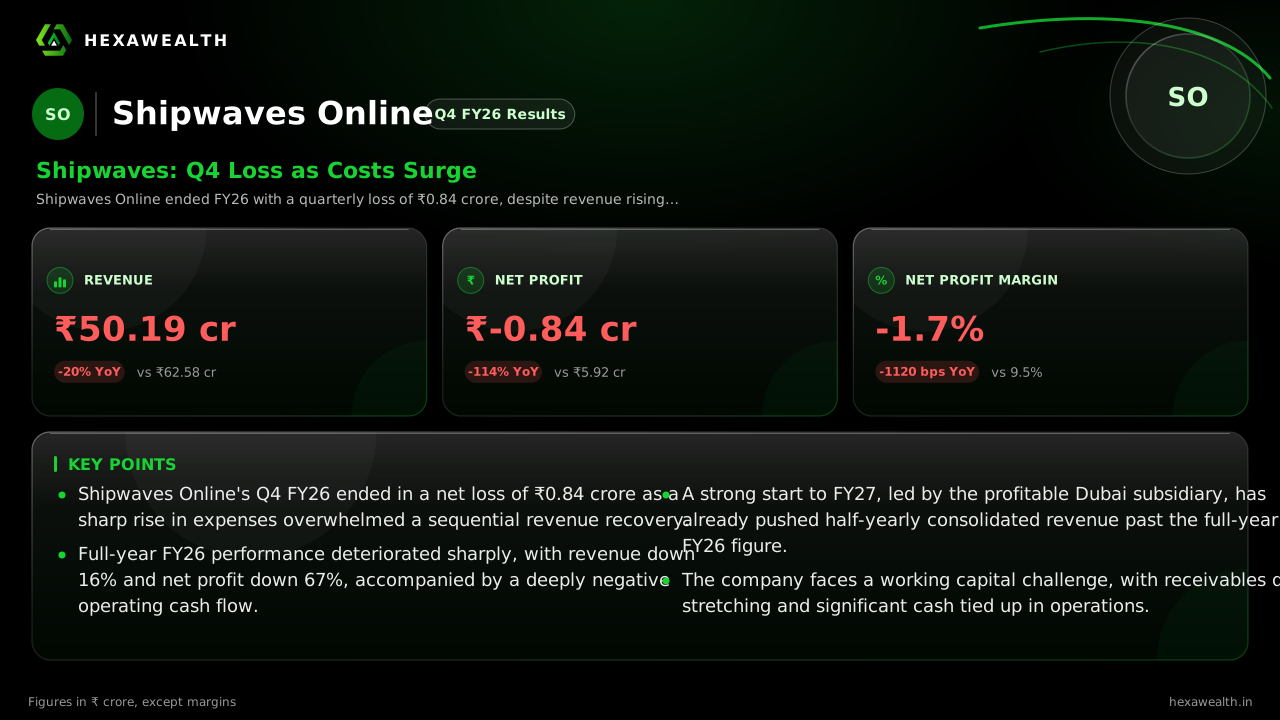
Shipwaves Online ended FY26 with a quarterly loss of ₹0.84 crore, despite revenue rising sequentially. The year saw a 16% revenue decline and a 67% profit drop, with operating cash flow deeply negative.
For a digital freight forwarder, the quarter ending the fiscal year should reflect steady execution and cash generation. Shipwaves Online's March quarter delivered the opposite, with a surprise loss capping a year of contracting revenue and profitability.
The numbers tell a story of pressure on both ends. Revenue for Q4 FY26 was ₹50.19 crore, down 20% from a year ago but up 23% from the previous quarter. The net loss of ₹0.84 crore, however, swung dramatically from a ₹4.69 crore profit in Q2 FY26. For the full year, revenue fell 16% to ₹91.17 crore, and net profit plunged 67% to ₹3.57 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 62.58
- Revenue (₹ Cr), Q2 FY26: 40.98
- Revenue (₹ Cr), Q4 FY26: 50.19
- Profit (₹ Cr), Q4 FY25: 5.92
- Profit (₹ Cr), Q2 FY26: 4.69
- Profit (₹ Cr), Q4 FY26: -0.84
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 62.58
- Revenue (₹ Cr), Q2 FY26: 40.98
- Revenue (₹ Cr), Q4 FY26: 50.19
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 5.92
- Profit (₹ Cr), Q2 FY26: 4.69
- Profit (₹ Cr), Q4 FY26: -0.84
Net Profit Margin
- Net Profit Margin, Q4 FY25: 9.5%
- Net Profit Margin, Q2 FY26: 11.4%
- Net Profit Margin, Q4 FY26: -1.7%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 50.19YoY -20% | 62.58 |
| Profit (₹ Cr) | -0.84YoY -114% | 5.92 |
| Net Profit Margin | -1.7%YoY -118% | 9.5% |
Why the bottom line vanished
A 46.5% quarter-on-quarter surge in total expenses erased the sequential revenue gain. Data from Newboard.in shows the operating profit margin collapsed to 0.8% in the second half of FY26 from 19.3% in the first half. Depreciation also jumped 35% sequentially, pointing to capitalised investments starting to weigh on the P&L.
The cash flow statement reveals a deeper strain. Operating cash flow was a negative ₹17.93 crore for FY26, against a modest profit. This was driven by a massive ₹42.84 crore increase in working capital, primarily from rising receivables. According to a report by Multibagg.ai, consolidated trade receivables ballooned further in the first half of FY27.
A pivot already in motion
Management action and subsidiary performance are scripting a different story for the new fiscal year. The company's H1 FY27 results, noted by M Capital, show consolidated revenue of ₹107.15 crore has already surpassed the entire FY26 figure. Profit for the half-year stood at ₹5.15 crore.
Live Chart
· SHIPWAVES
(BSE)
ISIN: INE0O9L01010
This rebound is fuelled by the Dubai subsidiary, which contributed a ₹9.75 crore profit while the standalone Indian business posted a loss. The board has approved an ₹11.63 crore corporate guarantee to secure credit facilities for this subsidiary, signalling a continued growth focus abroad.
Key Points
- Shipwaves Online's Q4 FY26 ended in a net loss of ₹0.84 crore as a sharp rise in expenses overwhelmed a sequential revenue recovery.
- Full-year FY26 performance deteriorated sharply, with revenue down 16% and net profit down 67%, accompanied by a deeply negative operating cash flow.
- A strong start to FY27, led by the profitable Dubai subsidiary, has already pushed half-yearly consolidated revenue past the full-year FY26 figure.
- The company faces a working capital challenge, with receivables days stretching and significant cash tied up in operations.
Hexa Perspective
The March quarter closes a chapter Shipwaves will want to move past quickly. The FY26 contraction and cash burn highlight execution challenges in its core market. The stark turnaround in H1 FY27, however, shows the model can work—but it is currently dependent on a single overseas subsidiary for profitability.
The valuation at a 74% discount to the industry P/E reflects the past year's struggles. Investors are now weighing the sustainability of the subsidiary-led growth against the persistent working capital drag and the recent resignation of the Head of Sales, which M Capital notes creates near-term revenue execution risk. The next few quarters must demonstrate that the consolidated profit run-rate can be maintained and that cash conversion improves.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.