Seemax Resources (SEEMAX) Q4 FY26 Profit Slips 12% as Revenue Declines 13% in Q4
Seemax Resources posted a 13.4% drop in Q4 revenue and an 11.7% fall in profit, though a one-off income surge helped the net margin inch up.
Seemax Resources' Q4 FY26 saw revenue and profit decline year-on-year. A sharp rise in other income provided a cushion, but higher interest and depreciation costs weighed on the bottom line.
For Seemax Resources, the March 2026 quarter capped a year where the top line softened. The material handling equipment provider saw both revenue and profit decline, a trend that has continued into the new fiscal year.
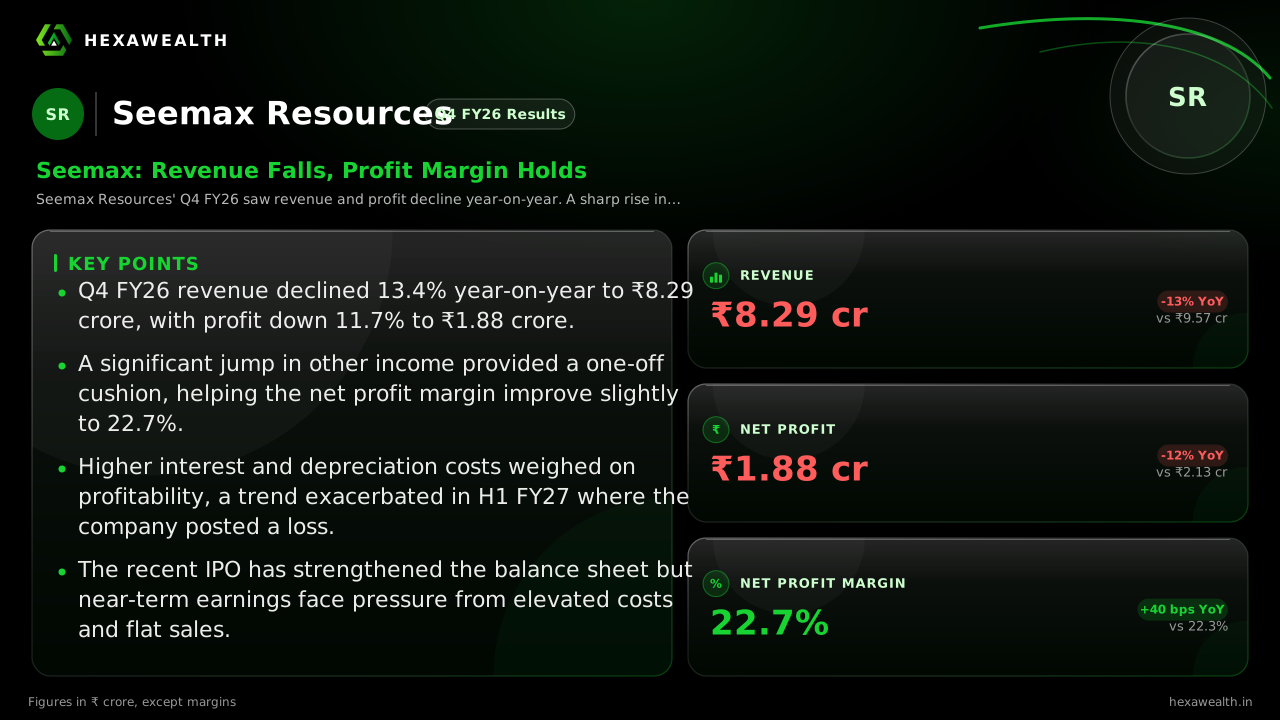
Revenue for Q4 FY26 stood at ₹8.29 crore, down 13.4% from the same quarter last year. Net profit followed, falling 11.7% to ₹1.88 crore. The net profit margin, however, edged up 40 basis points to 22.7%.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
- Revenue (₹ Cr.), Q4 FY25: 9.57
- Revenue (₹ Cr.), Q4 FY26: 8.29
- Profit (₹ Cr.), Q4 FY25: 2.13
- Profit (₹ Cr.), Q4 FY26: 1.88
Revenue (₹ Cr.)
- Revenue (₹ Cr.), Q4 FY25: 9.57
- Revenue (₹ Cr.), Q4 FY26: 8.29
Profit (₹ Cr.)
- Profit (₹ Cr.), Q4 FY25: 2.13
- Profit (₹ Cr.), Q4 FY26: 1.88
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 22.3
- Net Profit Margin (%), Q4 FY26: 22.7
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr.) | 8.29YoY -13% | 9.57 |
| Profit (₹ Cr.) | 1.88YoY -12% | 2.13 |
| Net Profit Margin (%) | 22.7YoY +1.8% | 22.3 |
The Cushion and the Squeeze
The slight margin improvement came from a sharp, one-time surge in other income. It jumped to ₹0.62 crore from just ₹0.02 crore a year ago, as reported by mcapital.in. This offset some pressure from the core business.
That pressure came from rising finance and depreciation costs. Interest expense climbed 49.2% year-on-year, reflecting a higher debt burden. Depreciation rose 32%, linked to capital expenditure from its recent IPO.
A Look Beyond the Quarter
The full-year picture shows a steeper profit decline. For FY26, profit fell 25.8% to ₹1.75 crore on a 4.7% drop in revenue. The company's operating profit margin for the year also contracted.
Live Chart
· SEEMAX
(BSE)
ISIN: INE1EVO01017
This weakness has extended into FY27. The company reported a ₹1.61 crore loss for H1 FY27, according to its November board meeting outcome. Employee and other expenses surged sharply, turning operating profit negative.
Key Points
- Q4 FY26 revenue declined 13.4% year-on-year to ₹8.29 crore, with profit down 11.7% to ₹1.88 crore.
- A significant jump in other income provided a one-off cushion, helping the net profit margin improve slightly to 22.7%.
- Higher interest and depreciation costs weighed on profitability, a trend exacerbated in H1 FY27 where the company posted a loss.
- The recent IPO has strengthened the balance sheet but near-term earnings face pressure from elevated costs and flat sales.
Hexa Perspective
Seemax's Q4 results highlight a transition phase. The company is investing for growth post-IPO, but these investments are hitting the P&L through higher depreciation and interest before showing up in revenue.
The immediate challenge is cost control. The H1 FY27 loss, which nearly wipes out FY26's full-year profit, signals that margin pressure is intensifying. Investors are weighing a stronger balance sheet against a clear deterioration in near-term earnings momentum.
The path forward hinges on whether the deployed capex can drive revenue growth sufficient to absorb these higher fixed costs. Until that happens, profitability is likely to remain under strain.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.