Safety Controls & Devices (SCDL) Q2 FY27 Profit Jumps 43% as Debt Costs Fall
The EPC firm's profit surged sequentially despite lower revenue, driven by a sharp drop in interest expense after aggressive debt repayment.
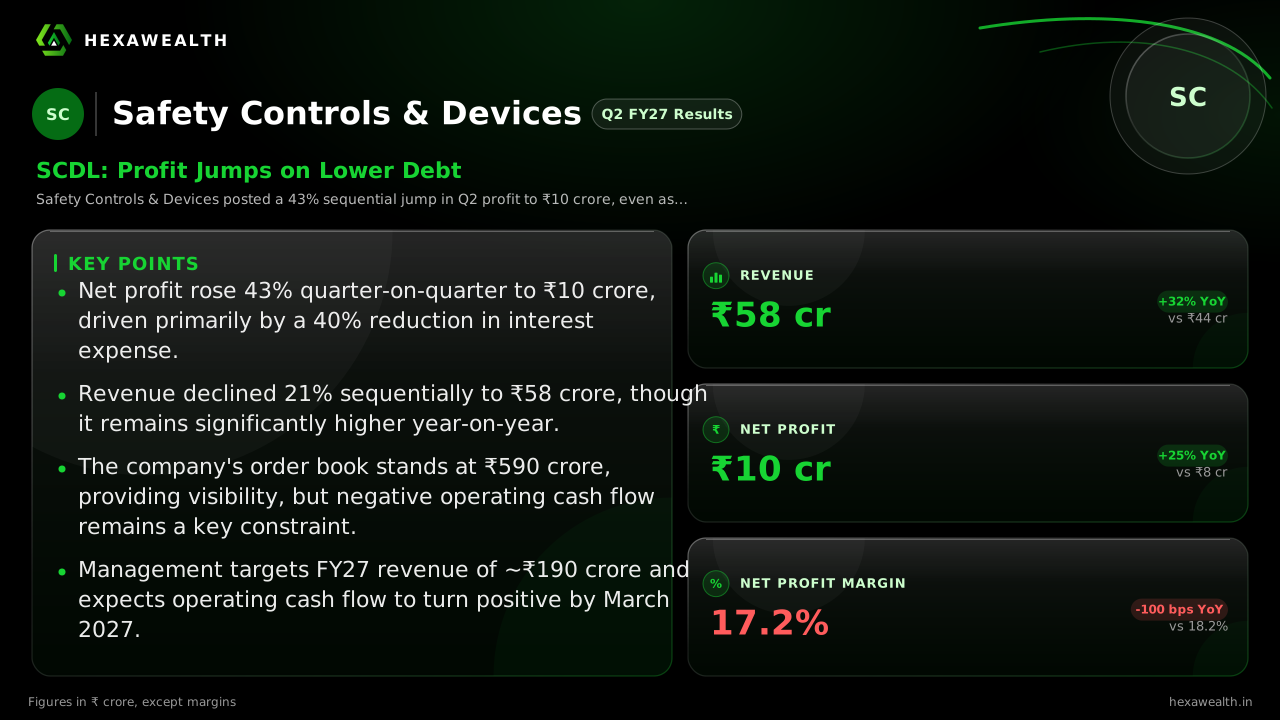
Safety Controls & Devices posted a 43% sequential jump in Q2 profit to ₹10 crore, even as revenue fell 21%. The profit surge was fueled by a 40% cut in interest costs following a major debt reduction.
For an EPC contractor, the quarter's story is often written in project completions and cash collected. Safety Controls & Devices delivered a different plot: profit surged on lower sales, a direct result of cleaning up its balance sheet.
Revenue of ₹58 crore was down 21% from the March quarter but still 32% higher than a year ago. Profit, however, leapt 43% sequentially to ₹10 crore. The net profit margin expanded sharply to 17.2%, recovering from 9.6% last quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY25: 61.6
- Revenue (₹ Cr), Q4 FY25: 57.0
- Revenue (₹ Cr), Q2 FY26: 44.0
- Revenue (₹ Cr), Q4 FY26: 73.0
- Revenue (₹ Cr), Q2 FY27: 58.0
- Profit (₹ Cr), Q1 FY25: 4.5
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q4 FY26: 7.0
- Profit (₹ Cr), Q2 FY27: 10.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY25: 61.6
- Revenue (₹ Cr), Q4 FY25: 57.0
- Revenue (₹ Cr), Q2 FY26: 44.0
- Revenue (₹ Cr), Q4 FY26: 73.0
- Revenue (₹ Cr), Q2 FY27: 58.0
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY25: 4.5
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 8.0
- Profit (₹ Cr), Q4 FY26: 7.0
- Profit (₹ Cr), Q2 FY27: 10.0
Net Profit Margin
- Net Profit Margin, Q1 FY25: 7.3%
- Net Profit Margin, Q4 FY25: 10.5%
- Net Profit Margin, Q2 FY26: 18.2%
- Net Profit Margin, Q4 FY26: 9.6%
- Net Profit Margin, Q2 FY27: 17.2%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 58.0YoY +32% | 44.0 |
| Profit (₹ Cr) | 10.0YoY +25% | 8.0 |
| Net Profit Margin | 17.2%YoY -5.5% | 18.2% |
The Interest Cost Windfall
The profit jump was powered by a 40% sequential drop in interest expense. According to reports from stockfin.ai and others, total borrowings fell 40.6% to ₹29.2 crore after the company used IPO proceeds to repay debt. This financial engineering provided a clear, one-time lift to the bottom line.
Growth Tempered by Cash Strain
While the balance sheet improved, operating performance showed strain. The blog.perivis.com noted that H1 EBITDA grew only 6.5% against a 33.4% revenue rise, indicating margin pressure. More critically, operating cash flow was negative ₹19 crore for the half-year, a persistent issue management expects to resolve by March as project retentions are collected.
Management, described as cautiously optimistic by blog.perivis.com, provided specific revenue guidance: approximately ₹190 crore for FY27 and ₹260-270 crore for FY28. This hinges on executing a ₹590 crore order book, which reports from stockfin.ai show is dominated by substation work for utilities like NTPC and Power Grid.
Live Chart
· SCDL
(BSE)
ISIN: INE0UMH01018
Key Points
- Net profit rose 43% quarter-on-quarter to ₹10 crore, driven primarily by a 40% reduction in interest expense.
- Revenue declined 21% sequentially to ₹58 crore, though it remains significantly higher year-on-year.
- The company's order book stands at ₹590 crore, providing visibility, but negative operating cash flow remains a key constraint.
- Management targets FY27 revenue of ~₹190 crore and expects operating cash flow to turn positive by March 2027.
Hexa Perspective
The quarter presents a financial repair job succeeding ahead of operational momentum. The debt reduction is a clear positive, lifting profitability now and reducing risk later. However, the path forward relies entirely on converting a large order book into cash-generative revenue without further margin erosion.
The guidance is ambitious, implying a steep ramp-up in second-half execution. Investors are left weighing a stronger balance sheet and solid backlog against the unresolved cash conversion cycle. The next few quarters will test whether the operational engine can match the financial tune-up.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.