Sandur Manganese (SANDUMA) Q2 FY27 Profit Soars 88% on Steel Margins and Debt Cut
The mining and steel group's Q2 FY27 profit surged as steel segment earnings more than doubled and a sharp fall in interest costs boosted margins.
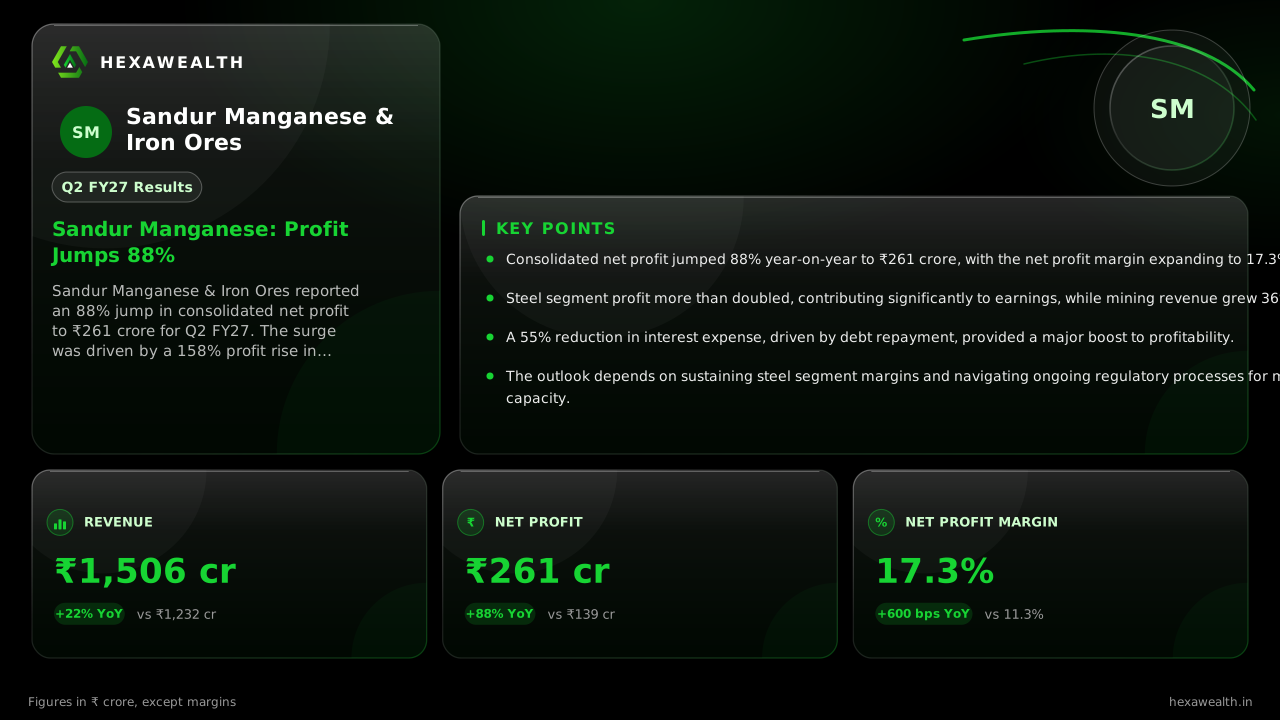
Sandur Manganese & Iron Ores reported an 88% jump in consolidated net profit to ₹261 crore for Q2 FY27. The surge was driven by a 158% profit rise in its steel segment and a 55% reduction in interest expense from debt repayment.
For Sandur Manganese, the September quarter was a story of two distinct strengths. Its steel business saw profits more than double, while its core mining operations delivered robust growth. This combination, amplified by a sharp reduction in debt costs, powered a significant earnings beat.
The numbers show a clear trajectory of improvement. Revenue grew 22% year-on-year to ₹1,506 crore, while net profit surged 88% to ₹261 crore. The net profit margin expanded to 17.3%, a 600 basis point jump from the same quarter last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1506.13YoY +22% | 1374.78 | 1232.34 |
| Profit (₹ Cr) | 261.25YoY +88% | 227.85 | 138.87 |
| Net Profit Margin (%) | 17.3YoY +53% | 16.6 | 11.3 |
Steel and Mining Drive the Surge
The profit leap was overwhelmingly a steel story. According to a report by Stockwatch, the steel segment's profit more than doubled year-on-year to ₹104 crore, far outpacing its 16% revenue growth. This points to stronger spreads or realisations in the segment during the quarter.
The core mining business also grew strongly. Mining segment revenue rose 36% year-on-year to ₹476 crore, as per the same report. This was supported by a 59% surge in iron ore sales volumes, according to data from Flash Finance.
The Interest Cost Tailwind
A major lever for margin expansion was a dramatic fall in interest expense. It dropped 55% year-on-year to ₹26 crore. This was due to active debt reduction, with cash flow statements showing net repayments of borrowings in the first half, as noted by Arthneeti.
The company's debt-to-equity ratio stands at a comfortable 0.31. This financial discipline directly boosted pre-tax profits, turning a cost centre into a source of earnings growth.
Outlook Hinges on Spreads and Regulation
The key question is whether the steel segment's improved spreads can be sustained. The domestic steel sector shows steady demand, with finished steel consumption up 7.7% year-on-year in the first half, per government data.
Regulatory clarity remains a watchpoint. The company is seeking an enhancement in its iron ore production capacity and is engaged in a legal process over a compensatory afforestation demand from the Karnataka Forest Department, as highlighted by Flash Finance.
Key Points
- Consolidated net profit jumped 88% year-on-year to ₹261 crore, with the net profit margin expanding to 17.3%.
- Steel segment profit more than doubled, contributing significantly to earnings, while mining revenue grew 36%.
- A 55% reduction in interest expense, driven by debt repayment, provided a major boost to profitability.
- The outlook depends on sustaining steel segment margins and navigating ongoing regulatory processes for mining capacity.
Hexa Perspective
The quarter demonstrates powerful operating leverage. Profit growth vastly outpaced revenue growth, showing what happens when volume gains, better realisations, and a lighter balance sheet converge.
The sustainability of this performance rests on two pillars. Steel spreads must hold in a stable demand environment, and the core mining business needs to maintain its volume momentum. The company's valuation at a 35% premium to the industry P/E suggests the market is pricing in this improved earnings profile, but also leaves less room for disappointment.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.