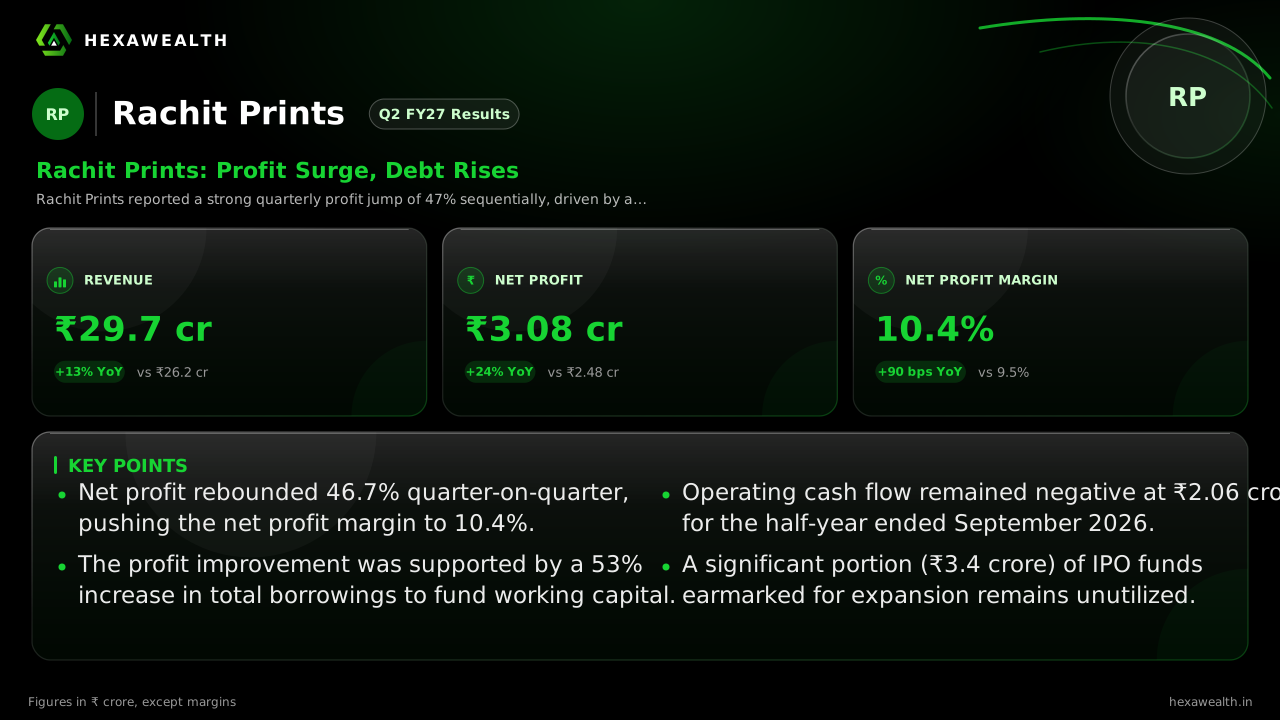
Rachit Prints (RACHIT) Q2 FY27 Profit Jumps 47% as Margins Recover
The textile printer's Q2 profit rebounded sharply, but the improvement was funded by a significant increase in working capital debt.
Rachit Prints reported a strong quarterly profit jump of 47% sequentially, driven by a recovery in net profit margins. However, this performance was supported by a 53% rise in borrowings to fund receivables and inventory.
For Rachit Prints, the September quarter was about efficiency after a period of cost pressure. The company delivered a sharp rebound in profitability, but the source of that improvement tells a more complex story about funding its own growth.
The numbers show a clear recovery. Revenue grew 13.4% year-on-year to ₹29.7 crore, while net profit jumped 24.2% to ₹3.08 crore. Sequentially, the profit surge was even sharper at 46.7%. The net profit margin expanded to 10.4%, a 260 basis point improvement from the previous quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 20.63
- Revenue (₹ Cr), Q4 FY25: 21.07
- Revenue (₹ Cr), Q2 FY26: 26.2
- Revenue (₹ Cr), Q4 FY26: 27.04
- Revenue (₹ Cr), Q2 FY27: 29.7
- Profit (₹ Cr), Q2 FY25: 2.23
- Profit (₹ Cr), Q4 FY25: 2.33
- Profit (₹ Cr), Q2 FY26: 2.48
- Profit (₹ Cr), Q4 FY26: 2.1
- Profit (₹ Cr), Q2 FY27: 3.08
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 20.63
- Revenue (₹ Cr), Q4 FY25: 21.07
- Revenue (₹ Cr), Q2 FY26: 26.2
- Revenue (₹ Cr), Q4 FY26: 27.04
- Revenue (₹ Cr), Q2 FY27: 29.7
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 2.23
- Profit (₹ Cr), Q4 FY25: 2.33
- Profit (₹ Cr), Q2 FY26: 2.48
- Profit (₹ Cr), Q4 FY26: 2.1
- Profit (₹ Cr), Q2 FY27: 3.08
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 10.8
- Net Profit Margin (%), Q4 FY25: 11.1
- Net Profit Margin (%), Q2 FY26: 9.5
- Net Profit Margin (%), Q4 FY26: 7.8
- Net Profit Margin (%), Q2 FY27: 10.4
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 29.7YoY +13% | 26.2 |
| Profit (₹ Cr) | 3.08YoY +24% | 2.48 |
| Net Profit Margin (%) | 10.4YoY +9.5% | 9.5 |
Where the margin gain came from
The margin recovery, despite a 21.6% quarterly rise in interest cost, points to better operational control. Data from mcapital.in suggests lower other expenses helped offset higher material and depreciation costs. The 76.5% yearly jump in depreciation itself signals new capacity coming online, a necessary cost for future growth.
The cost of funding growth
This operational improvement, however, was not cash-funded. Reports from mcapital.in and ForgeUp highlight a critical tension: borrowings rose 53% to ₹13.66 crore by September 2026. This debt financed a build-up in receivables and inventory, leading to negative operating cash flow of ₹2.06 crore for the half-year.
The company's expansion plans add another layer. ForgeUp notes ₹3.4 crore of IPO proceeds for plant and machinery remain unspent in bank deposits. This indicates a delay in planned capital expenditure, even as working capital needs surge.
Live Chart
· RACHIT
(BSE)
ISIN: INE0ZN101029
The market's muted reaction
The stock market absorbed these mixed signals with little movement. According to marketsmojo.com, the stock last traded at ₹158.35 on November 13, 2026, the day before the results. With no institutional holding and a P/E of 17.9 trading at a near 50% discount to the industry, the market seems to be pricing in the risks alongside the profit recovery.
Key Points
- Net profit rebounded 46.7% quarter-on-quarter, pushing the net profit margin to 10.4%.
- The profit improvement was supported by a 53% increase in total borrowings to fund working capital.
- Operating cash flow remained negative at ₹2.06 crore for the half-year ended September 2026.
- A significant portion (₹3.4 crore) of IPO funds earmarked for expansion remains unutilized.
Hexa Perspective
The quarter presents a textbook case of profit growth funded by balance sheet expansion. The margin recovery is encouraging and suggests the company has navigated past input cost pressures. Yet, the sustainability of this model hinges on converting the built-up inventory and receivables into cash. If sales momentum continues and the working capital cycle shortens, the debt-funded profit can transition into cash-funded growth. If not, the elevated borrowing costs could begin to erode the very margins that just recovered. The delayed capex spend adds another question about the timing of its next growth phase.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.