Popular Vehicles (PVSL) Q2 FY27 Profit Jumps 286% as Revenue Growth Accelerates
The auto retailer posted a 36.5% rise in revenue and a 286% jump in net profit, driven by strong volume growth and network expansion.
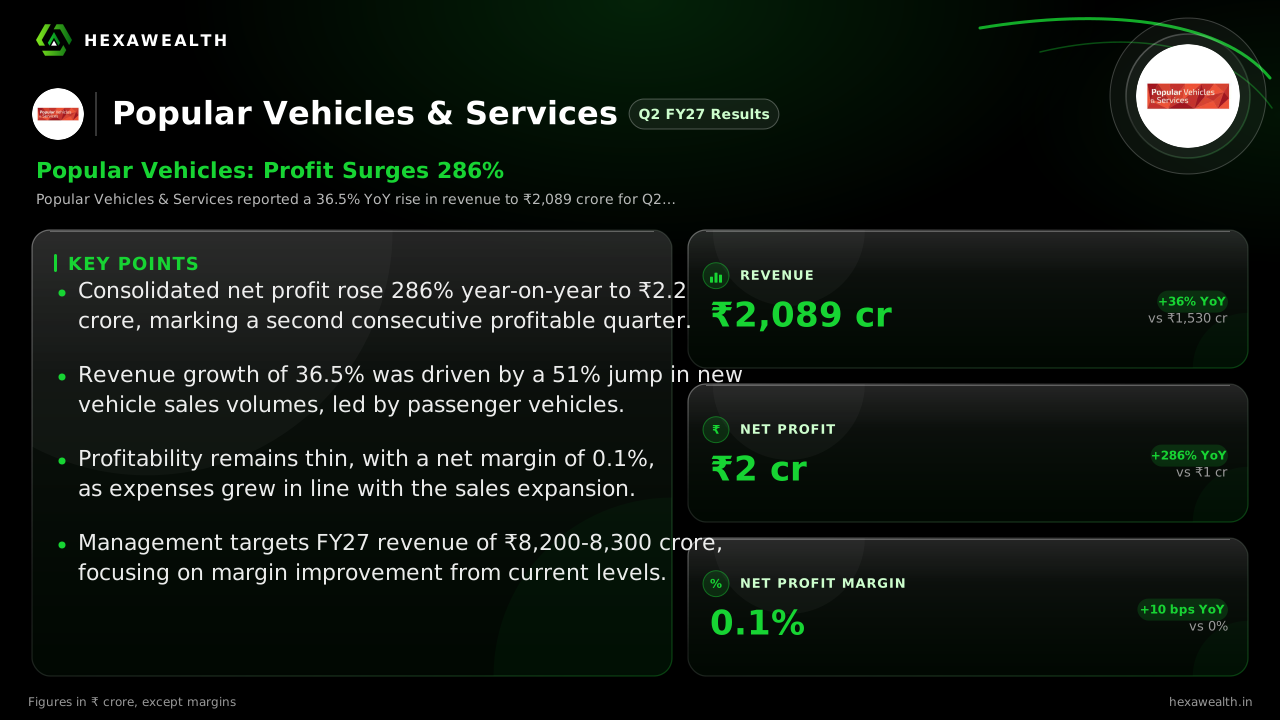
Popular Vehicles & Services reported a 36.5% YoY rise in revenue to ₹2,089 crore for Q2 FY27. Net profit surged 286% to ₹2.2 crore, marking a second consecutive profitable quarter.
For Popular Vehicles, the September quarter was about converting a broad market recovery into consistent profitability. The company delivered a second straight quarter of profit, with net income surging 286% year-on-year to ₹2.2 crore on the back of a 36.5% revenue jump.
The numbers show a clear growth trajectory. Revenue reached ₹2,089 crore, up 10.5% from the June quarter. Net profit margin, though thin at 0.1%, is a positive turn from the loss-making quarters of the past year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1,530.38
- Revenue (₹ Cr), Q3 FY26: 1,785.36
- Revenue (₹ Cr), Q4 FY26: 1,754.45
- Revenue (₹ Cr), Q1 FY27: 1,889.58
- Revenue (₹ Cr), Q2 FY27: 2,088.92
- Profit (₹ Cr), Q2 FY26: 0.57
- Profit (₹ Cr), Q3 FY26: 0.67
- Profit (₹ Cr), Q4 FY26: -4.96
- Profit (₹ Cr), Q1 FY27: 1.37
- Profit (₹ Cr), Q2 FY27: 2.20
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1,530.38
- Revenue (₹ Cr), Q3 FY26: 1,785.36
- Revenue (₹ Cr), Q4 FY26: 1,754.45
- Revenue (₹ Cr), Q1 FY27: 1,889.58
- Revenue (₹ Cr), Q2 FY27: 2,088.92
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 0.57
- Profit (₹ Cr), Q3 FY26: 0.67
- Profit (₹ Cr), Q4 FY26: -4.96
- Profit (₹ Cr), Q1 FY27: 1.37
- Profit (₹ Cr), Q2 FY27: 2.20
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 0.0
- Net Profit Margin (%), Q3 FY26: 0.0
- Net Profit Margin (%), Q4 FY26: -0.3
- Net Profit Margin (%), Q1 FY27: 0.1
- Net Profit Margin (%), Q2 FY27: 0.1
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,088.92YoY +36% | 1,889.58 | 1,530.38 |
| Profit (₹ Cr) | 2.20YoY +286% | 1.37 | 0.57 |
| Net Profit Margin (%) | 0.1 | 0.1 | 0.0 |
The Engine of Growth
New vehicle sales volumes, the core of the business, grew 51% year-on-year, according to a business update cited by Multibagg.ai. This was led by a 46% surge in non-luxury passenger vehicles. The growth is a mix of organic execution and contributions from recent acquisitions, which helped reduce the company's revenue dependence on its home state of Kerala below 50%.
The Profit Puzzle and Rising Costs
Despite the top-line surge, profit before tax fell 63% from the year-ago quarter. This is because last year's PBT of ₹11.7 crore was inflated by a one-off tax-related item, creating a high base. The underlying operating performance is improving, but costs are rising in step with sales.
Total expenses grew 36% YoY. Depreciation surged 51%, reflecting investments in new showrooms and service centres opened during the year. Interest costs also rose 25% as debt increased, partly to build inventory ahead of anticipated price hikes from manufacturers.
Live Chart
· PVSL
(BSE)
ISIN: INE772T01024
The Road Ahead and Market Discipline
Management has guided for full-year FY27 revenue of ₹8,200-8,300 crore, implying 20-25% growth, as reported by Multibagg.ai. The focus is now on converting scale into sustainable margins, with a target to reach a 4.3-4.4% operating margin by year-end.
The key test will be maintaining this momentum against tougher year-ago comparisons and potential headwinds from rising interest rates. The company's ability to manage working capital and integrate acquired businesses will be critical for the profit trajectory to hold.
Key Points
- Consolidated net profit rose 286% year-on-year to ₹2.2 crore, marking a second consecutive profitable quarter.
- Revenue growth of 36.5% was driven by a 51% jump in new vehicle sales volumes, led by passenger vehicles.
- Profitability remains thin, with a net margin of 0.1%, as expenses grew in line with the sales expansion.
- Management targets FY27 revenue of ₹8,200-8,300 crore, focusing on margin improvement from current levels.
Hexa Perspective
Popular Vehicles is in a clear turnaround phase, with revenue growth accelerating and losses turning to profit. The story is one of operational execution and successful network integration.
The sustainability of this recovery hinges on two factors. First, the company must navigate a rising interest rate environment and higher comparative bases in the coming quarters. Second, it needs to demonstrate that the recent margin improvement is structural, not just a function of low-base effects and one-off benefits. The guidance for steady margin expansion will be the metric to watch.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.