Piotex Industries (PIOTEX) Posts a Mere ₹1 Crore Revenue in Q2 FY27
The textile firm's quarterly revenue plunged over 98% year-on-year to just ₹1 crore, though a high margin figure masks the near-halt in operations.
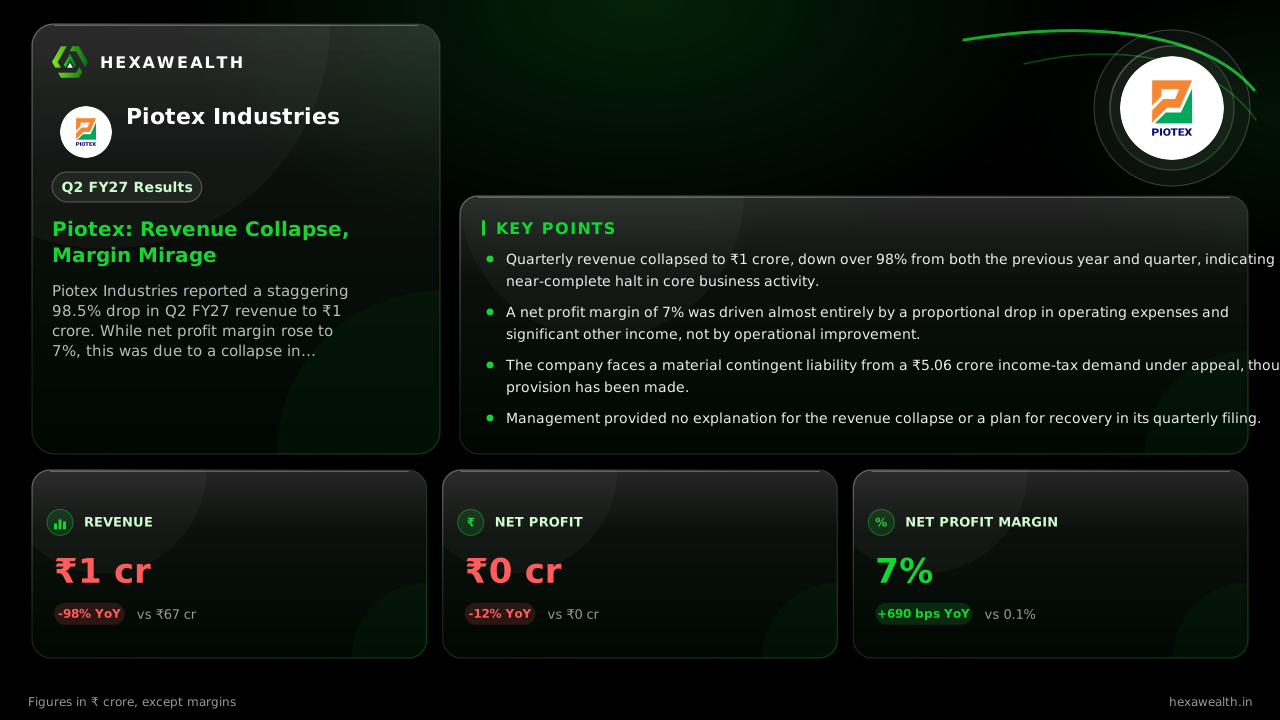
Piotex Industries reported a staggering 98.5% drop in Q2 FY27 revenue to ₹1 crore. While net profit margin rose to 7%, this was due to a collapse in operating expenses and other income, not a recovery in its core yarn and fabric business.
For a textile manufacturer, a quarter with just ₹1 crore in revenue signals a fundamental pause in operations. Piotex Industries' September quarter results show a business that has all but stopped selling its core cotton yarn and fabrics, with revenue collapsing 98.5% from a year ago.
The numbers tell a story of near dormancy. Revenue fell to ₹1 crore from ₹66.69 crore in Q2 FY26 and ₹23.51 crore last quarter. Net profit was ₹0.07 crore, down 12.5% year-on-year. The apparent bright spot—a net profit margin of 7%—is a mirage created by expenses falling in lockstep with sales.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 1.00YoY -99% | 66.69 |
| Profit (₹ Cr) | 0.07YoY -12% | 0.08 |
| Net Profit Margin | 7.0%YoY +6900% | 0.1% |
Why the margin expanded on vanishing sales
Profitability improved because costs shrank as fast as the top line. Total expenses fell 98% year-on-year to ₹1.33 crore. A sharp reduction in purchases of stock-in-trade, noted by Multibagg.ai, mirrored the revenue drop. Other income of ₹0.43 crore, nearly half the total income, provided crucial support to the bottom line.
The company's filing offered no management explanation for the decline, according to the same report. With no segment data provided, it is impossible to tell if this is a strategic winding down or a severe demand shock. The lack of commentary or recovery plan leaves investors with more questions than answers.
A clouded outlook with contingent risks
Beyond the operational stall, a contingent liability looms. The company disclosed a contested income-tax demand of ₹5.06 crore for assessment year 2024-25, as reported by Multibagg.ai. Management, after consulting experts, considers an outflow not probable and has made no provision.
The stock closed at ₹22.80 on the results date, up 3.68%. This muted reaction suggests the market had largely priced in the company's challenges. With a P/E of 17.7, trading at a 62% discount to the industry average, the valuation reflects deep uncertainty about a return to normalcy.
Key Points
- Quarterly revenue collapsed to ₹1 crore, down over 98% from both the previous year and quarter, indicating a near-complete halt in core business activity.
- A net profit margin of 7% was driven almost entirely by a proportional drop in operating expenses and significant other income, not by operational improvement.
- The company faces a material contingent liability from a ₹5.06 crore income-tax demand under appeal, though no provision has been made.
- Management provided no explanation for the revenue collapse or a plan for recovery in its quarterly filing.
Hexa Perspective
The quarter raises fundamental questions about Piotex's ongoing business model. A revenue line of ₹1 crore for a textile supplier is not a cyclical dip but suggests operations have effectively ceased. The improved margin is a mathematical artifact of minimal activity, not a turnaround.
The path forward is opaque. Investors must weigh the absence of management guidance against the material tax contingency. Until the company clarifies whether this quarter is an aberration or a new baseline, the stock's deep discount to the sector is likely to persist.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.