PAN HR Solution (PANHR) Q4 FY26 Doubles Q4 Profit as Cost Discipline Offsets Revenue Decline
The staffing firm's net profit surged 100% in the March quarter, driven by a sharp drop in service costs that more than offset a full-year revenue decline.
PAN HR Solution's Q4 FY26 profit doubled year-on-year to ₹4 crore, even as annual revenue fell 17%. The jump was powered by a disciplined cost structure, with service expenses falling faster than sales.
For a staffing company, the story is usually written in headcount and billing rates. PAN HR Solution’s FY26 narrative, however, was rewritten by its cost sheet. While annual revenue contracted, a sharper fall in expenses delivered a profit surge in the final quarter, setting a new efficiency benchmark.
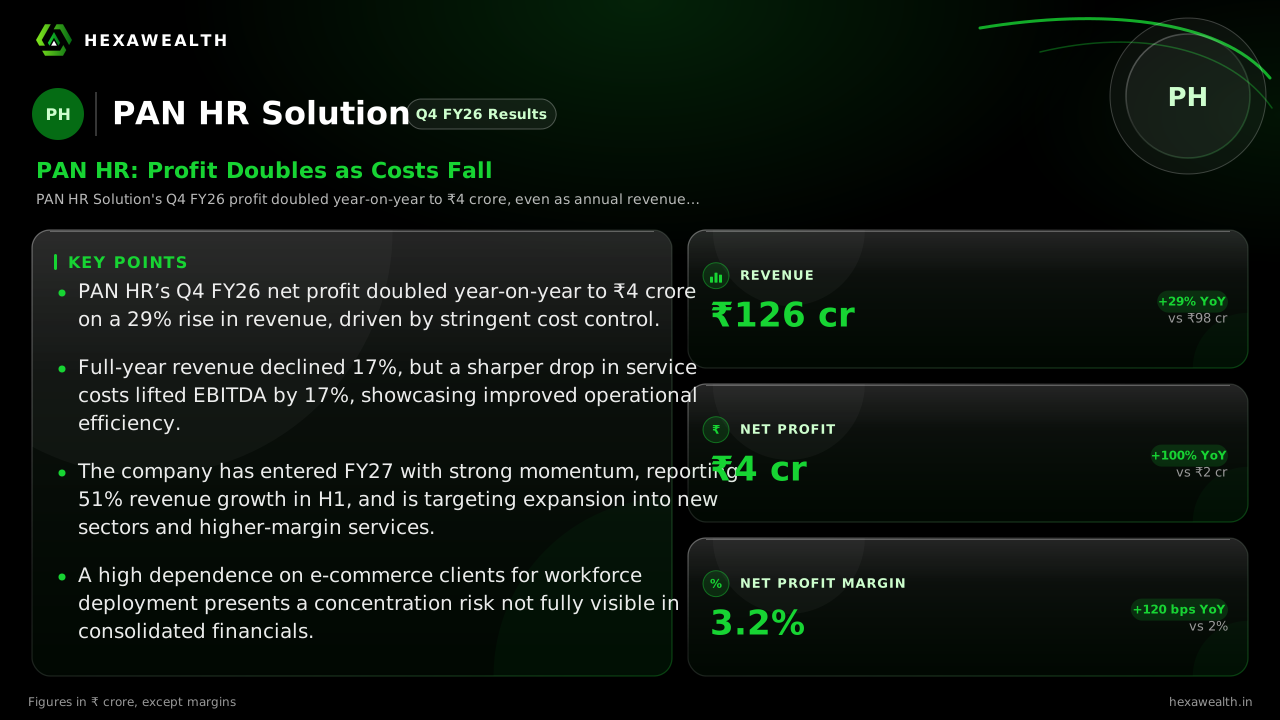
The fourth quarter saw revenue rise 29% year-on-year to ₹126 crore, with profit doubling to ₹4 crore. The net profit margin expanded 120 basis points to 3.2%. This quarterly strength, however, contrasts with the full year, where revenue fell 17% to ₹234.5 crore and profit declined 23% to ₹7.5 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 98.0
- Revenue (₹ Cr), Q4 FY26: 126.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q4 FY26: 4.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 98.0
- Revenue (₹ Cr), Q4 FY26: 126.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q4 FY26: 4.0
Net Profit Margin
- Net Profit Margin, Q4 FY25: 2.0%
- Net Profit Margin, Q4 FY26: 3.2%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 126.0YoY +29% | 98.0 |
| Profit (₹ Cr) | 4.0YoY +100% | 2.0 |
| Net Profit Margin | 3.2%YoY +60% | 2.0% |
The Efficiency Engine
The profit leap was not driven by a major new contract. Research from Multibagg.ai shows a recent solar staffing win is incremental, estimated to add just 1-3% to revenue. Instead, the gain came from costs falling faster than sales. According to the same analysis, service costs dropped ₹47 crore in FY26, exceeding the revenue decline.
This created operating leverage. EBITDA rose 17% for the year despite the lower sales base. The company’s shift to a more disciplined cost structure, as noted in an Alfafinder.com results update, was key. A lower effective tax rate also aided the quarterly bottom line.
A Year of Two Halves
Management attributed the annual revenue moderation to contract repricing and billing adjustments, per a Multibagg.ai report. The second half marked a clear turnaround, with the company reporting 28% year-on-year growth for H2 FY26. This momentum has carried into the new fiscal year.
Live Chart
· PANHR
(BSE)
ISIN: INE1N9E01015
PAN HR’s H1 FY27 results, reported in November 2026, show revenue up 51% year-on-year. The company, cited in a Tribune India release, says it is progressing toward a 'Pay & Collect' model to fund larger mandates and expand into tier-II cities and higher-margin services like payroll outsourcing.
The Concentration Question
Growth is concentrated. The company’s FY26 workforce deployment was heavily skewed toward e-commerce, which accounted for over 8,100 of its 10,000-plus personnel. While this ties PAN HR to a high-growth sector, it also represents a significant client concentration risk that is not detailed in revenue disclosures.
Key Points
- PAN HR’s Q4 FY26 net profit doubled year-on-year to ₹4 crore on a 29% rise in revenue, driven by stringent cost control.
- Full-year revenue declined 17%, but a sharper drop in service costs lifted EBITDA by 17%, showcasing improved operational efficiency.
- The company has entered FY27 with strong momentum, reporting 51% revenue growth in H1, and is targeting expansion into new sectors and higher-margin services.
- A high dependence on e-commerce clients for workforce deployment presents a concentration risk not fully visible in consolidated financials.
Hexa Perspective
The quarter confirms PAN HR can protect margins in a softer revenue environment, a crucial skill in the competitive staffing sector. The challenge now is scaling the top line without losing this hard-won cost discipline. The planned shift to 'Pay & Collect' and higher-margin services could improve returns, but will test working capital management. Investors are essentially betting the company can replicate its H1 FY27 growth rate while navigating its concentrated client exposure and a sector known for tight margins.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.