Oxygenta Pharmaceutical (OXYGENTAPH) Q2 FY27's Revenue Jumps 135% but Losses Deepen Sequentially
The pharma firm's Q2 FY27 sales more than doubled year-on-year, but a sharp rise in interest and material costs pushed its net loss wider from the previous quarter.
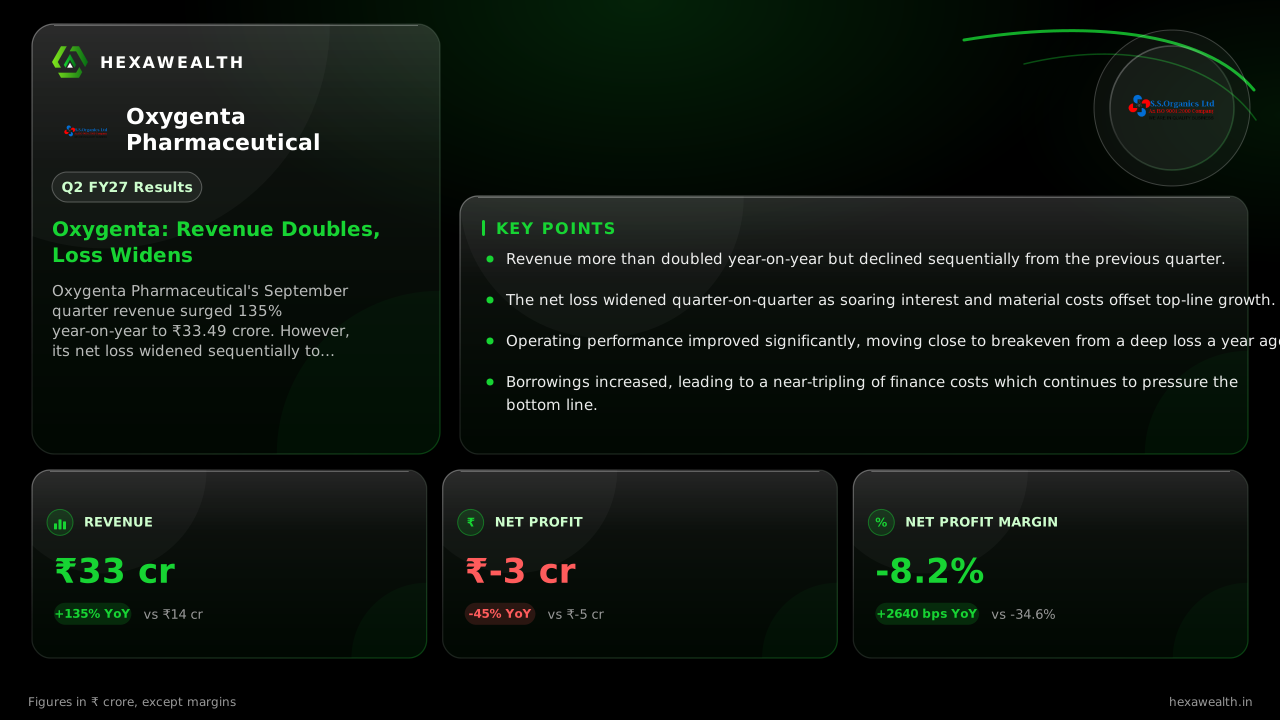
Oxygenta Pharmaceutical's September quarter revenue surged 135% year-on-year to ₹33.49 crore. However, its net loss widened sequentially to ₹2.73 crore as interest costs nearly tripled and material expenses rose sharply.
For Oxygenta Pharmaceutical, the September quarter presented a stark divergence. The company achieved a massive scale-up, with revenue more than doubling from a low base. Yet, this growth came at a steep cost, as the path to profitability remains blocked by rising financial and operational expenses.
The numbers tell a story of two opposing forces. Revenue jumped 135% year-on-year to ₹33.49 crore, a significant improvement from ₹14.25 crore in Q2 FY26. Sequentially, however, sales dipped 9.5% from ₹37.0 crore in the June quarter. The net loss of ₹2.73 crore was 44.6% narrower than the year-ago loss of ₹4.93 crore, but it widened by 30% from the ₹2.1 crore loss in Q1 FY27.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 14.25
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 33.93
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 49.61
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 37.00
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 33.49
- Profit (₹ Cr), Q2 FY26 (Sep 2025): -4.93
- Profit (₹ Cr), Q3 FY26 (Dec 2025): -4.84
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -1.70
- Profit (₹ Cr), Q1 FY27 (Jun 2026): -2.10
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -2.73
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 14.25
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 33.93
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 49.61
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 37.00
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 33.49
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): -4.93
- Profit (₹ Cr), Q3 FY26 (Dec 2025): -4.84
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -1.70
- Profit (₹ Cr), Q1 FY27 (Jun 2026): -2.10
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -2.73
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 33.49 | 37.00 |
| Profit (₹ Cr) | -2.73 | -2.10 |
| PAT Margin (%) | -8.2 | -5.7 |
The Cost of Growth
The revenue surge did not translate to the bottom line due to a severe margin squeeze. A report from ScanX.trade notes that the cost of materials consumed was approximately 73% of operating revenue. This, coupled with a near-tripling of finance costs to ₹2.73 crore, eroded any potential operating profit.
The spike in interest expense, up 187% year-on-year, points to higher borrowings funding working capital needs. FlashFinance data shows borrowings rose to ₹283 crore as of September 2026, up from ₹264 crore in March. This growing debt burden is a direct drag on earnings.
A Glimmer in Operations
Despite the net loss, there was a notable operational improvement. The company reported a near-break-even operating profit of ₹0.03 crore, a dramatic recovery from an operating loss of ₹4.57 crore a year ago. This suggests the core manufacturing business is scaling, but profitability is being swallowed by financing costs.
Live Chart
· OXYGENTAPH
(BSE)
ISIN: INE102E01018
Management commentary, as reported by StockWatch, was limited to announcing the results. The board did approve a strategic land acquisition in Telangana for ₹6.75 crore to support future expansion, indicating a focus on long-term infrastructure.
Key Points
- Revenue more than doubled year-on-year but declined sequentially from the previous quarter.
- The net loss widened quarter-on-quarter as soaring interest and material costs offset top-line growth.
- Operating performance improved significantly, moving close to breakeven from a deep loss a year ago.
- Borrowings increased, leading to a near-tripling of finance costs which continues to pressure the bottom line.
Hexa Perspective
The quarter underscores a company caught between scaling operations and a strained balance sheet. The operational turnaround from last year's deep losses is evident, showing the business can generate revenue. However, the sustainability of this model is in question.
Profitability hinges on two factors: stabilizing revenue at these higher levels to absorb fixed costs, and managing the cost of capital. Until the company demonstrates an ability to generate consistent operating profits that can cover its financing expenses, the net loss trend is likely to persist. Investors are left weighing the operational progress against the financial leverage that currently funds it.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.