Ola Electric (OLAELEC) Q2 FY27's Revenue Crashes 39% as Losses Narrow on Cost Cuts
Ola Electric's Q2 revenue fell sharply on lower volumes, but aggressive cost-cutting helped narrow its net loss year-on-year.
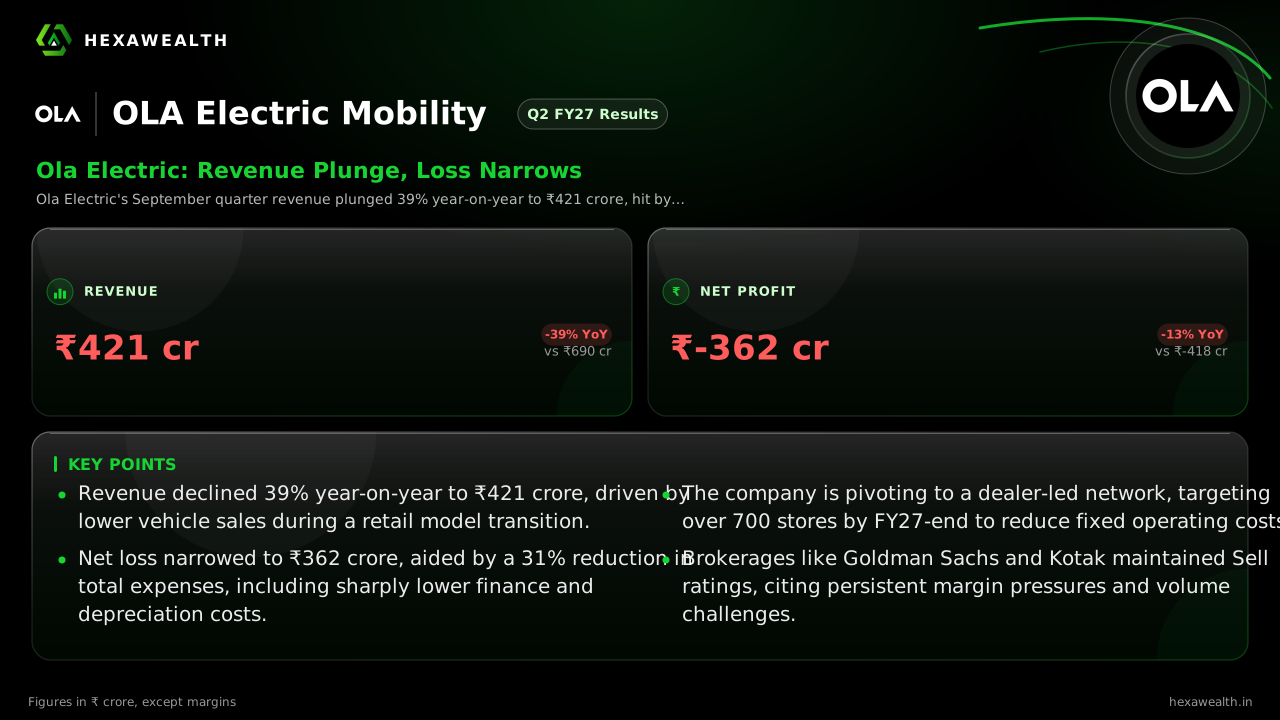
Ola Electric's September quarter revenue plunged 39% year-on-year to ₹421 crore, hit by lower vehicle registrations. The net loss narrowed to ₹362 crore, aided by a sharp drop in total expenses and lower finance costs.
For Ola Electric, the September quarter was about managing a painful transition. The electric scooter maker is pivoting from a direct-sales model to a dealer-led network while ramping up its own battery cell production. This shift, against fierce competition, defined its latest numbers.
Revenue fell 39% from a year ago to ₹421 crore, extending a decline from the June quarter. The net loss, however, narrowed 13% to ₹362 crore. A year earlier, revenue was ₹690 crore with a loss of ₹418 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep '25): 690
- Revenue (₹ Cr), Q3 FY26 (Dec '25): 470
- Revenue (₹ Cr), Q4 FY26 (Mar '26): 265
- Revenue (₹ Cr), Q1 FY27 (Jun '26): 455
- Revenue (₹ Cr), Q2 FY27 (Sep '26): 421
- Profit (₹ Cr), Q2 FY26 (Sep '25): -418
- Profit (₹ Cr), Q3 FY26 (Dec '25): -487
- Profit (₹ Cr), Q4 FY26 (Mar '26): -500
- Profit (₹ Cr), Q1 FY27 (Jun '26): -336
- Profit (₹ Cr), Q2 FY27 (Sep '26): -362
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep '25): 690
- Revenue (₹ Cr), Q3 FY26 (Dec '25): 470
- Revenue (₹ Cr), Q4 FY26 (Mar '26): 265
- Revenue (₹ Cr), Q1 FY27 (Jun '26): 455
- Revenue (₹ Cr), Q2 FY27 (Sep '26): 421
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep '25): -418
- Profit (₹ Cr), Q3 FY26 (Dec '25): -487
- Profit (₹ Cr), Q4 FY26 (Mar '26): -500
- Profit (₹ Cr), Q1 FY27 (Jun '26): -336
- Profit (₹ Cr), Q2 FY27 (Sep '26): -362
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 421 | 455 |
| Profit (₹ Cr) | -362 | -336 |
Why Revenue Fell Sharply
Sales volumes dropped as the company restructured its retail network. Vehicle registrations fell to 41,651 units from 51,775 a year ago, reports Ventura Securities. Management told BusinessWorld Auto that supply-chain constraints, not demand, now limit output. The company is closing its own stores and routing all new production through dealers.
The Cost-Cut Story
Despite lower sales, the loss narrowed because total expenses fell 31% year-on-year. Finance costs dropped 42% and depreciation fell 37%, according to the analysis. Business Standard notes workforce restructuring and lower warranty expenses also contributed. These cuts provided a financial cushion as the top line shrank.
The Dealer Transition and Outlook
The shift to dealers is central to the turnaround plan. Ola had 319 dealer stores by early November and targets over 700 by March 2027. Management expects gross margin to dip in the coming quarters due to dealer commissions. But operating margin should improve as company-owned stores close, saving fixed costs.
Live Chart
· OLAELEC
(BSE)
ISIN: INE0LXG01040
The newly commissioned 6 GWh Gigafactory is the other pillar. Management expects its own cells to provide a cost advantage as yields improve. The company targets using 2-3 GWh of these cells for its vehicles in FY28.
Market Reaction and Broker View
The stock fell nearly 6% after the results. Brokerages remain skeptical. Goldman Sachs maintained a Sell rating, cutting its target to ₹22, citing gross margin pressure and weak volumes. Kotak Institutional Equities also kept a Sell, with a target of ₹18, flagging concerns over cash breakeven.
Key Points
- Revenue declined 39% year-on-year to ₹421 crore, driven by lower vehicle sales during a retail model transition.
- Net loss narrowed to ₹362 crore, aided by a 31% reduction in total expenses, including sharply lower finance and depreciation costs.
- The company is pivoting to a dealer-led network, targeting over 700 stores by FY27-end to reduce fixed operating costs.
- Brokerages like Goldman Sachs and Kotak maintained Sell ratings, citing persistent margin pressures and volume challenges.
Hexa Perspective
Ola Electric is executing a high-stakes pivot. The narrowing loss shows cost discipline is taking hold, but the severe revenue contraction reveals the operational disruption of moving to dealers. The next few quarters will test whether this new channel can stabilize sales off a lower base.
The promised benefits from in-house cells and a leaner cost structure are still ahead. For now, the path to cash breakeven depends on a fragile balance: scaling production, improving cell yields, and winning back market share in a market now led by TVS and Bajaj.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.