NSB BPO (NSBBPO) Q4 FY26 Revenue Jumps 29% but Profit Margins Shrink
NSB BPO's Q4 FY26 saw a sharp revenue rise, but costs grew faster, squeezing net profit margins and raising questions about cash flow.
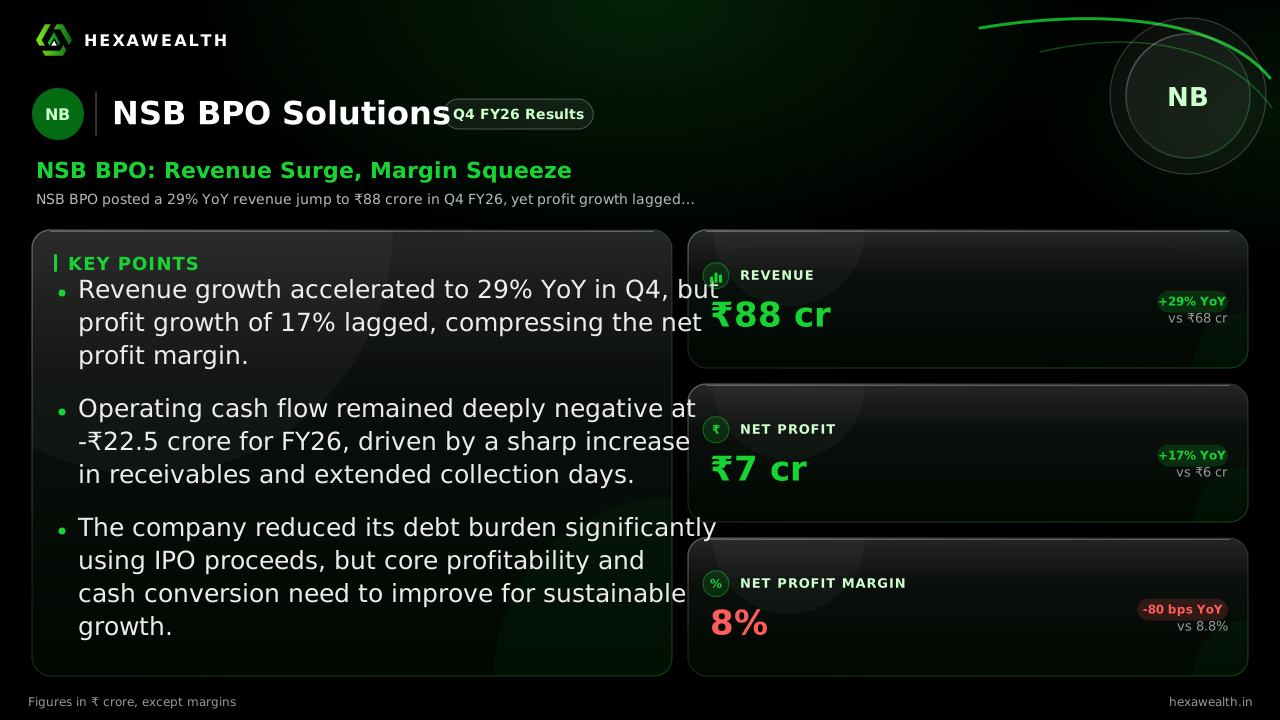
NSB BPO posted a 29% YoY revenue jump to ₹88 crore in Q4 FY26, yet profit growth lagged at 17%. The margin squeeze, driven by rising costs and a negative operating cash flow, defines the quarter's challenge.
For NSB BPO, the quarter was a story of strong top-line momentum meeting stubborn cost pressures. The company delivered its highest quarterly revenue in recent periods, but the profit that reached shareholders grew at a slower pace, highlighting a squeeze that management must now address.
Revenue for the March 2026 quarter rose 29% year-on-year to ₹88 crore, accelerating from the 22% sequential growth. Profit followed, increasing 17% to ₹7 crore. However, the net profit margin contracted 80 basis points from a year ago and 30 points from the previous quarter, settling at 8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 70.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 72.0
- Revenue (₹ Cr), Q4 FY26: 88.0
- Profit (₹ Cr), Q2 FY25: 5.0
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 7.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 70.0
- Revenue (₹ Cr), Q4 FY25: 68.0
- Revenue (₹ Cr), Q2 FY26: 72.0
- Revenue (₹ Cr), Q4 FY26: 88.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 5.0
- Profit (₹ Cr), Q4 FY25: 6.0
- Profit (₹ Cr), Q2 FY26: 6.0
- Profit (₹ Cr), Q4 FY26: 7.0
Net Profit Margin
- Net Profit Margin, Q2 FY25: 7.1%
- Net Profit Margin, Q4 FY25: 8.8%
- Net Profit Margin, Q2 FY26: 8.3%
- Net Profit Margin, Q4 FY26: 8.0%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 88.0YoY +29% | 68.0 |
| Profit (₹ Cr) | 7.0YoY +17% | 6.0 |
| Net Profit Margin | 8.0%YoY -9.1% | 8.8% |
Where the growth went
Total expenses surged 32% YoY, outpacing revenue growth. Data from newboard.in shows employee costs as a percentage of sales were 26% in Q4, an improvement from 49% in Q2 FY26 but still a significant operational outlay. This suggests that while staffing efficiency may be improving, the cost of delivering higher sales volumes is pressuring profitability.
The full-year picture shows a similar trend. FY26 revenue grew 16% to ₹160 crore, with profit up 16% to ₹12.8 crore. Yet the operating margin, as reported by Investing.com, fell 140 basis points to 12.3%, indicating that cost pressures are a sustained, not quarterly, challenge.
The cash flow conundrum
A deeper concern lies in cash generation. Operating cash flow for FY26 was deeply negative at -₹22.5 crore, a deterioration from -₹6.7 crore in FY25. According to newboard.in, debtor days stretched to 181, meaning customers are taking nearly six months to pay on average.
Live Chart
· NSBBPO
(BSE)
ISIN: INE0SLP01017
This working capital drain saw receivables swell by over ₹20 crore during the year. While the company used IPO proceeds to cut borrowings by ₹13.9 crore, the core business is not yet generating the cash to fund its own growth or reduce reliance on external capital.
The road ahead
Management, as noted by KnowYourCompany.ai, indicated business momentum would strengthen in the second half of FY27 but provided no specific numeric revenue guidance. The industry backdrop from a Kotak Institutional Equities report cautions about deflationary pressures in customer management services, a core BPO segment.
For NSB BPO, the path to sustaining growth while improving shareholder returns hinges on converting sales into cash and defending margins in a competitive pricing environment. The recent IPO has provided a balance sheet cushion, but operational discipline is the next test.
Key Points
- Revenue growth accelerated to 29% YoY in Q4, but profit growth of 17% lagged, compressing the net profit margin.
- Operating cash flow remained deeply negative at -₹22.5 crore for FY26, driven by a sharp increase in receivables and extended collection days.
- The company reduced its debt burden significantly using IPO proceeds, but core profitability and cash conversion need to improve for sustainable growth.
Hexa Perspective
The quarter confirms NSB BPO's ability to win business and grow the top line, a positive in a sector where scale matters. Yet, the margin contraction and severe cash burn reveal the cost of that growth. Investors are left weighing a cheap valuation—the stock trades at a 71% discount to the industry P/E—against the operational challenge of turning revenue into reliable cash profit.
The next few quarters will show if management can leverage the cleaner balance sheet to tighten costs and collections. Until operating cash flow turns positive, the company's growth will remain dependent on the capital it has already raised, not the earnings it generates.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.