Nexxus Petro (NEXXUS) Q4 FY26 Profit Doubles as Supply Shock Halves Revenue
Geopolitical disruptions slashed Nexxus Petro's Q4 revenue by 45%, but sharp cost control and a new plant doubled profit sequentially.
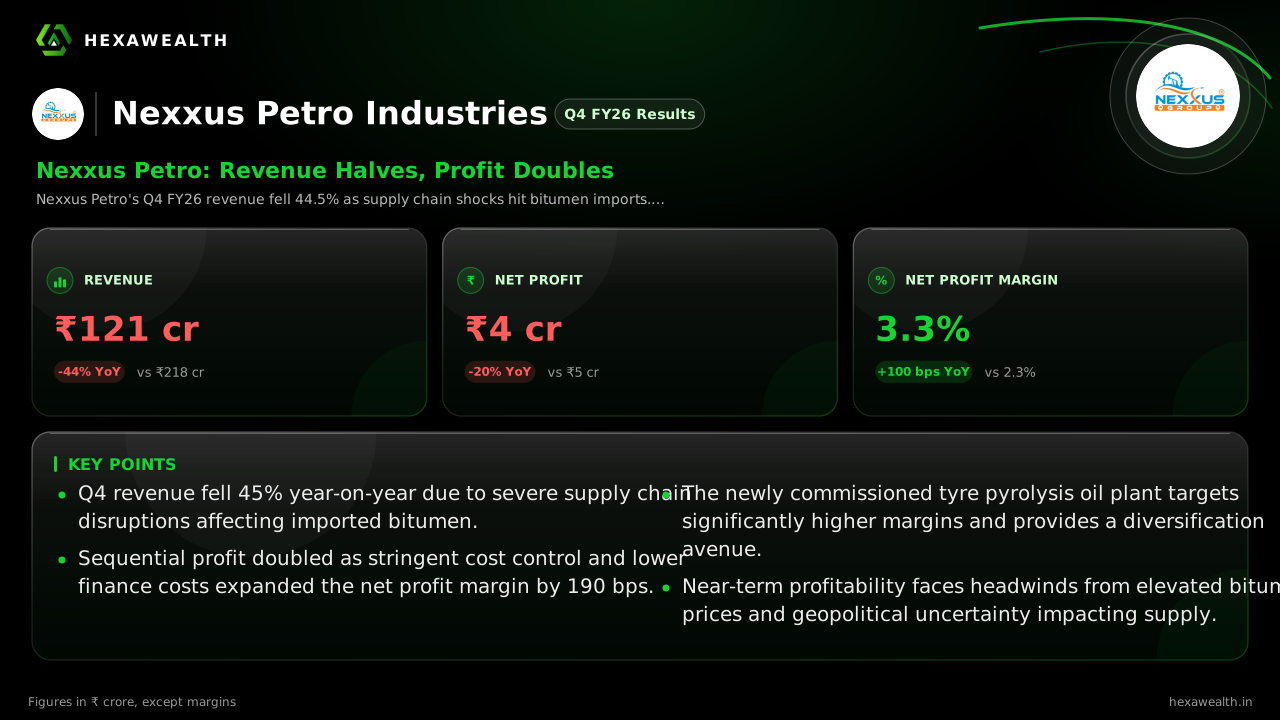
Nexxus Petro's Q4 FY26 revenue fell 44.5% as supply chain shocks hit bitumen imports. Yet, net profit doubled from the previous quarter as margins expanded sharply, aided by a new pyrolysis oil facility.
For a bitumen supplier, the quarter is a race between road-building demand and the cost of getting the material to site. Nexxus Petro Industries lost that race in the March quarter, as geopolitical conflict choked its supply lines just as India's road construction season was peaking.
Revenue fell 44.5% from a year ago to ₹121 crore. Profit, however, doubled sequentially to ₹4 crore, as the company cut costs faster than sales fell. The net profit margin expanded 190 basis points from the September quarter to 3.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 99.0
- Revenue (₹ Cr), Q2 FY25: 87.0
- Revenue (₹ Cr), Q4 FY25: 218.0
- Revenue (₹ Cr), Q2 FY26: 141.0
- Revenue (₹ Cr), Q4 FY26: 121.0
- Profit (₹ Cr), Q4 FY24: 1.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 5.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 4.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 99.0
- Revenue (₹ Cr), Q2 FY25: 87.0
- Revenue (₹ Cr), Q4 FY25: 218.0
- Revenue (₹ Cr), Q2 FY26: 141.0
- Revenue (₹ Cr), Q4 FY26: 121.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 1.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 5.0
- Profit (₹ Cr), Q2 FY26: 2.0
- Profit (₹ Cr), Q4 FY26: 4.0
Net Profit Margin
- Net Profit Margin, Q4 FY24: 1.0%
- Net Profit Margin, Q2 FY25: 1.1%
- Net Profit Margin, Q4 FY25: 2.3%
- Net Profit Margin, Q2 FY26: 1.4%
- Net Profit Margin, Q4 FY26: 3.3%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 121.0YoY -44% | 218.0 |
| Profit (₹ Cr) | 4.0YoY -20% | 5.0 |
| Net Profit Margin | 3.3%YoY +43% | 2.3% |
Why the top line collapsed
Management, in its annual report, squarely blamed the war situation and geopolitical tensions. These disrupted international trade routes and the availability of imported bitumen, which is central to the company's operations. The impact was most severe towards the end of the financial year, preventing Nexxus from capitalising on the normally strong second half for road construction.
The margin rescue act
With sales volumes down, the company's focus shifted to preserving profitability. According to the scanx.trade report, finance costs fell by about 19% year-on-year. Other income also rose significantly. More importantly, cost of materials consumed fell 17.7%, a sharper drop than the revenue decline, indicating disciplined procurement and inventory management.
The real strategic shift is a new 30-tonne-per-day used tyre pyrolysis oil (TPO) plant at its Pali facility. The company expects this to generate ₹50-60 crore in annual revenue. Crucially, the TPO segment targets an 8-10% net profit margin, far above the core bitumen business, as noted in the same report.
Live Chart
· NEXXUS
(BSE)
ISIN: INE0QUL01011
A volatile road ahead
The near-term outlook is a tug-of-war. Structural demand from India's massive road infrastructure outlay remains strong. However, input cost volatility is a persistent threat. The Economic Times reported that bitumen prices had nearly doubled from earlier levels, squeezing contractor economics.
Nexxus's own guidance, cited by knowyourcompany.ai, suggests a challenging EBITDA margin outlook for FY27 due to war-led inflation. The new pyrolysis business offers a path to higher margins, but its contribution is still scaling up.
Key Points
- Q4 revenue fell 45% year-on-year due to severe supply chain disruptions affecting imported bitumen.
- Sequential profit doubled as stringent cost control and lower finance costs expanded the net profit margin by 190 bps.
- The newly commissioned tyre pyrolysis oil plant targets significantly higher margins and provides a diversification avenue.
- Near-term profitability faces headwinds from elevated bitumen prices and geopolitical uncertainty impacting supply.
Hexa Perspective
This quarter reveals a company navigating extreme external volatility with operational discipline. The margin expansion amidst a revenue collapse shows cost levers are being pulled effectively. The long-term story hinges on whether the high-margin pyrolysis business can scale fast enough to offset the inherent volatility of the core bitumen trade.
The valuation, at a P/E of 6.6 against an industry average of 12.2, prices in the supply-side risks. Investors are weighing the promise of downstream integration against the reality of a business still exposed to the whims of global freight and crude oil markets.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.