Neelam Linens (NEELAM) Q2 FY27 Profit Holds Steady Despite a 24% Revenue Slump
The home textile exporter's profit stayed flat year-on-year at ₹1 crore, but a sharp revenue drop and rising debt signal a challenging year ahead.
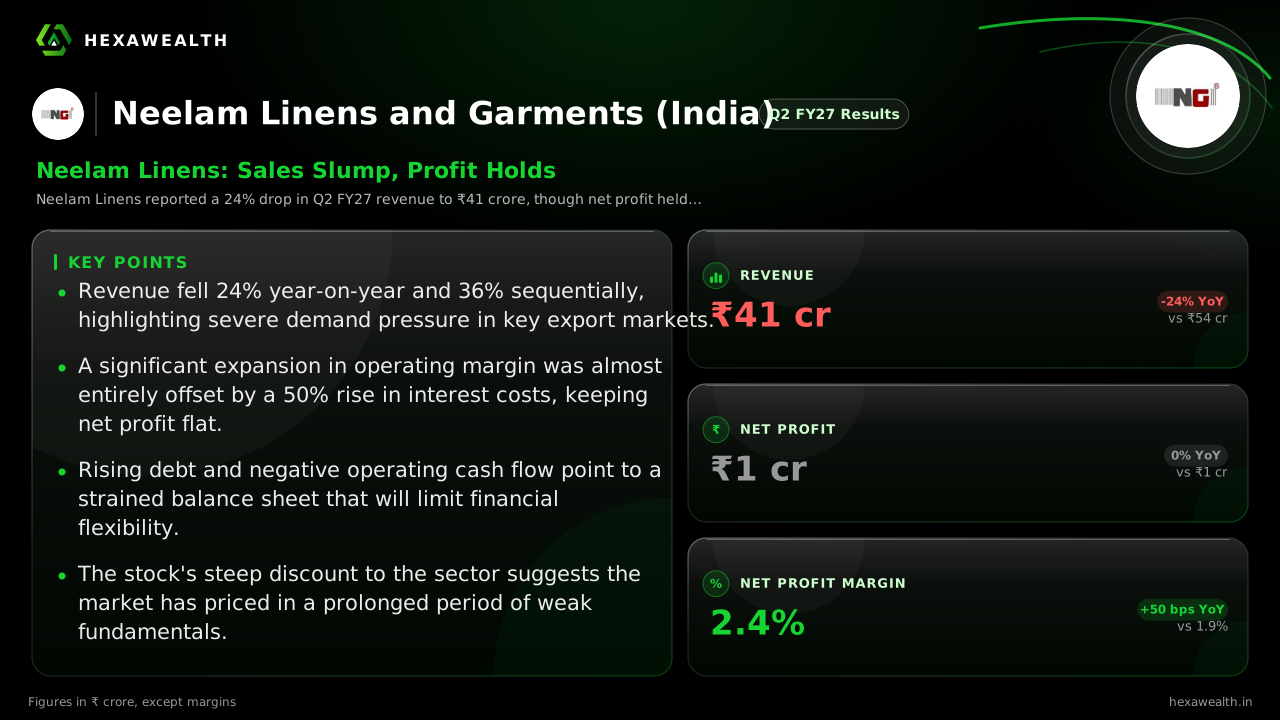
Neelam Linens reported a 24% drop in Q2 FY27 revenue to ₹41 crore, though net profit held at ₹1 crore. Improved operating margins were offset by higher interest costs and soft export demand, pointing to a weaker full year.
For an exporter like Neelam Linens, a sharp drop in sales usually drags profit down with it. This quarter, revenue fell 24% from a year ago to ₹41 crore, yet net profit held flat at ₹1 crore, a result of two opposing forces.
The numbers show a business under pressure. Revenue was down 36% from the previous quarter, continuing a volatile trend.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 37.0
- Revenue (₹ Cr), Q4 FY25: 73.0
- Revenue (₹ Cr), Q2 FY26: 54.0
- Revenue (₹ Cr), Q4 FY26: 64.0
- Revenue (₹ Cr), Q2 FY27: 41.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 1.0
- Profit (₹ Cr), Q4 FY26: 0.0
- Profit (₹ Cr), Q2 FY27: 1.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 37.0
- Revenue (₹ Cr), Q4 FY25: 73.0
- Revenue (₹ Cr), Q2 FY26: 54.0
- Revenue (₹ Cr), Q4 FY26: 64.0
- Revenue (₹ Cr), Q2 FY27: 41.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 1.0
- Profit (₹ Cr), Q4 FY26: 0.0
- Profit (₹ Cr), Q2 FY27: 1.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25: 2.7
- Net Profit Margin (%), Q4 FY25: 2.7
- Net Profit Margin (%), Q2 FY26: 1.9
- Net Profit Margin (%), Q4 FY26: 0.0
- Net Profit Margin (%), Q2 FY27: 2.4
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 41.0YoY -24% | 54.0 |
| Profit (₹ Cr) | 1.0YoY 0% | 1.0 |
| Net Profit Margin (%) | 2.4YoY +26% | 1.9 |
Why margins widened as sales shrank
Operating efficiency provided a crucial buffer. According to Flash Finance, the operating margin expanded by 232 basis points year-on-year to 9.7%. This suggests better cost management, possibly from lower raw material prices, even as sales to discount retailers in the US and EU softened.
That margin gain, however, was largely consumed by a 50% increase in interest expense. Reports from mCapital.in indicate total borrowings rose to around ₹84 crore by September 2026 from ₹69 crore in March. The higher finance cost kept pre-tax profit in check.
The debt load that won't lighten soon
With a debt-to-equity ratio of 1.0, interest is a persistent headwind. The company's negative operating cash flow and rising working capital days, noted by mCapital.in, mean borrowings are funding operations, not expansion. This structural pressure leaves little room for error if demand stays weak.
Live Chart
· NEELAM
(BSE)
ISIN: INE0N1401016
What the market is pricing in
The stock closed at ₹6.25 ahead of the results, down 71% over the past year. The valuation, at a P/E of 8.8, trades at a 75% discount to the industry average, reflecting deep skepticism. No formal management guidance was found, but mCapital.in projects full-year revenue could fall 12-18% and profit could drop 30-50%.
Key Points
- Revenue fell 24% year-on-year and 36% sequentially, highlighting severe demand pressure in key export markets.
- A significant expansion in operating margin was almost entirely offset by a 50% rise in interest costs, keeping net profit flat.
- Rising debt and negative operating cash flow point to a strained balance sheet that will limit financial flexibility.
- The stock's steep discount to the sector suggests the market has priced in a prolonged period of weak fundamentals.
Hexa Perspective
The quarter presents a clear trade-off: operational discipline against a worsening financial structure. The margin improvement shows the company can control what it spends, but it cannot control soft demand or the cost of its capital.
The path forward hinges on a recovery in export orders, particularly as broader Indian textile exports showed growth in August. Without a top-line rebound, the benefits of cost control will continue to be funneled to lenders, not shareholders, making the current profitability fragile.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.